October Monthly Roundup: Navigating the Tech Pullback. What We Bought and Our Shopping List.

October started on a high note, with the S&P 500 and the Nasdaq Composite both hitting record highs on October 6, but that proved to be the high-water mark for the month. As concerns over how the AI buildout will be funded took hold, and inflation data continued to move in the wrong direction, both indices retreated, and a brutal final session, in which the Nasdaq suffered its biggest one-day drop since June and Intel ($INTC) fell nearly 29%, made sure October ended with a thud.
In full, the S&P 500 fell 0.9% in October, while the more tech-heavy Nasdaq Composite dropped 5.3%, its worst month since March 2025 and leaving it roughly 8% below its closing high. Those developments weighed heavily on the Portfolio’s October performance, but it also brought with it some windows to put capital to work and build up some cash.
Despite the market’s drop in October, the demand side of the AI story got stronger during the month, not weaker. Microsoft ($MSFT) said demand still exceeds available capacity, Amazon ($AMZN) CEO Andy Jassy said AWS capacity for 2027 is largely sold out, Alphabet’s ($GOOGL) Cloud backlog climbed to $561 billion, and SK Hynix ($SKHY) said memory shortages should persist through at least 2030. Asia echoed that message on the final day of the month, with Tokyo Electron forecasting an 87% jump in operating profit and its CFO saying there are “no signs that this is slowing down.”
What changed was the market’s focus. In the first half of October Broadcom ($AVGO) CEO Hock Tan said capital will be the biggest constraint on AI development, and the hyperscalers’ September-quarter results put numbers to that. Meta’s ($META) free cash flow turned negative, Alphabet’s was negative for a second straight quarter, and Amazon posted its third straight quarter of negative free cash flow as capex consumed roughly 1.8x its operating cash flow. With all of them pointing to another step up in capex in 2027, Wall Street shifted from asking how much AI infrastructure is needed to asking how it will be paid for.
Capital Economics notes that the four hyperscalers account for more than a third of the capital spending by S&P 500 companies over the past 12 months, with that share likely to rise, and that is a concentration investors are struggling with. The result was pressure on the Tech sector and the Nasdaq, with AI infrastructure names, from chips and chip equipment to networking and power, taking the brunt of it.
Late in the month, we started to see those funding concerns addressed. Meta launched an equity raise that it boosted to almost $98 billion, and Microsoft followed with a $25 billion bond sale that drew roughly $115 billion in orders. With both offerings subscribed multiple times over, the market clearly has an appetite for them, and Amazon has now joined in.
In its 10-Q, Amazon disclosed supplier financing arrangements that allow it to borrow as much as $80 billion against the hardware it buys, a secured facility it can tap at its discretion from the start of 2027 through the third quarter of 2028, with lenders getting collateral rights over some of the assets purchased. Until now, Amazon had funded its buildout with cash from AWS and retail and its biggest-ever bond sales, steering clear of the creative structures some rivals have used, such as joint ventures with investment groups or chip leasing, so this is a notable step.
AWS CEO Matt Garman said the company is looking to “responsibly fund” the opportunity so it can “go as big as possible” for customers. It also underscores the scale of the commitments, as Amazon’s total spending commitments ballooned to $883 billion at the end of September, up 36% from the prior quarter, which is why we would not be surprised to see Alphabet follow suit. Our thinking is that one by one, as these funding questions are answered and measured against multi-year backlogs, Wall Street will revisit the AI infrastructure trade. Our intention is to be right there as that happens.
The second weight on the market was inflation. September CPI came in at 3.7% year over year, up from 3.4% in August and a tick above expectations, while the September PCE Price Index, the Fed’s preferred inflation gauge, rose to 3.6%, with core PCE at 3.1%. Both headline and core PCE hit their highest annual rates since May, and September marked the 68th straight month that PCE inflation has exceeded the Fed’s 2% target. Those figures came alongside a better-than-expected 3.4% Q3 GDP print, the fastest pace in a year, but the September jobs report showed just 29,000 jobs added, with July and August revised down by a combined 60,000. With average hourly earnings up 3.0% year over year, wage growth continues to lag inflation, and that’s a pinch consumers are feeling.
That combination has the Fed squarely focused on inflation. At its October 28 meeting, the Fed held rates at 3.75%-4.00%, but Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favor of a hike, and the statement noted that inflation remains elevated. Fed Chair Warsh pointed out that energy prices have moved higher again in recent weeks and suggested rates might already be at an appropriate level, although a growing group of his colleagues doesn’t seem convinced. On Friday, Dallas Fed President Lorie Logan, a voter this year, said she’d like to see two more quarter-point hikes, St. Louis Fed President Alberto Musalem said additional firming will be necessary “and soon,” and Richmond Fed President Tom Barkin, a voter in 2027, said the direction of travel is “pretty straightforward.”
The market exited October pricing in roughly a 73% chance, per the CME FedWatch tool, of a 25-basis-point hike at the December 8-9 meeting, one that would come after Tuesday’s midterm elections. Should the October data keep running hot, we suspect expectations could shift toward something more than 25 basis points.
Fueling those inflation concerns is oil. With the Iran war and the U.S. naval blockade keeping the Strait of Hormuz front and center, WTI crude climbed 15.2% in October to settle at $104.12 a barrel, while Brent rose 13.6% and finished the month above $113, the highest levels since the end of April and a fourth straight monthly gain for oil.
The month ended with fresh reminders of the risk. A tanker in the Strait of Hormuz was hit by limpet mines on Friday, the first known strike of its kind in the waterway since the war began in February, Houthi militants claimed attacks on Saudi oil facilities, and the U.S. ordered non-emergency staff to leave Saudi Arabia. Reports late in the month that the U.S. told Gulf countries to prepare for possible strikes on Iran after the midterms kept that risk premium firmly in place, even as Qatari mediators returned to Tehran in an effort to revive talks.
One of the things we’ve seen during the Q3 2026 earnings season to date is that higher energy costs are working their way through the economy. ISM’s September manufacturing prices index jumped to 77.9 from 71.1, and its services prices index rose to 74.0, the highest since July 2022, with fuel the most-cited issue. That’s showing up in corporate commentary as well. Coca-Cola ($KO) said cost pressures could extend into 2027, Procter & Gamble ($PG) raised its expected hit from raw materials, energy and freight to $1.4 billion and said the industry is pricing up to offset it, and both Reckitt and Nestlé ($NSRGY) pointed to more pricing ahead. As more companies target price increases in the coming months, we don’t see a meaningful downtick in ISM’s pricing figures for October. If anything, we wouldn’t be surprised to see them move higher.
Putting it all together, we enter November facing the midterm elections, a fresh round of inflation-related data and another wave of earnings. Democrats are widely expected to win the House, with the Senate more in doubt, and with prediction markets pointing to Democrats taking at least one chamber, we’ll assess the outcome and its likely impact on policy, keeping in mind that gridlock in Washington tends to be a good friend to Mr. Market.
The one wrinkle is AI. Public opposition to data centers over their energy and environmental impact is growing, and a significant Democratic showing could bring more scrutiny to the buildout. We see this similar to how people pushed back on the cell towers, but ultimately none of those people were willing to compromise on their connectivity.
While past performance isn’t a reliable predictor, since 1930, midterms resulting in a Republican president and a Democratic Congress have produced average S&P 500 gains of 15% in the following 12 months. Earnings have been the market’s foundation this year, with Q3 growth running around 30%, but the bar is high, as Caterpillar’s ($CAT) 9% drop after sticking with its sales forecast showed. Label us cautious, but we’d rather make higher-conviction moves once we have more data in hand. As the AI funding questions get answered, we’ll be looking to put capital to work in the names on our shopping list.
We’ll be watching the market and the Portfolio closely this week, and we’ll be back with our refreshed Portfolio table and pick-up points near-term.
Catching Up on the Portfolio
For October, the Portfolio outshined the major indices early in the month, but as the market’s focus on AI’s buildout came front and center, subsequent pressure on the Portfolio led it to outperform to the downside relative to those benchmarks.
Leading the way on the positive side were defensive holdings that benefited from the market’s rotation away from Tech, including Waste Management ($WM), Costco ($COST), the Health Care Select Sector SPDR Fund ($XLV) and TJX Companies ($TJX). The biggest drags were the AI infrastructure names caught up in the funding concerns, including Marvell ($MRVL), Applied Materials ($AMAT), Alphabet ($GOOGL), Arista Networks ($ANET) and Meta Platforms ($META), along with the EPS All-Stars basket.
We exited October with roughly 9% of the Portfolio’s assets in cash.
Portfolio Moves
We were active during the month, using the AI-related pullback to put capital to work where the data points kept building. In the AI infrastructure space, we added to AMAT near $426 on October 15 and again near $402 on October 28, resetting our checkpoint to $360. We picked up Broadcom ($AVGO) shares near $335 on October 19 and near $340 on October 27 and added to MRVL near $239 and $238 on those same days, upgrading it to a One rating and resetting our checkpoint to $175. We also added to ANET near $173 on October 23, Eaton ($ETN) near $395 on October 19 and the ROBO Global Robotics & Automation Index ETF ($ROBO) at $76.11 on October 27.
Outside of AI, we added to Axon Enterprise ($AXON) near $408 on October 8 and $412 on October 15, resetting our checkpoint to $360, and picked up Paccar ($PCAR) shares at $107.16 on October 23 with a new $95 checkpoint. Following the flurry of IPO, M&A and financing activity late in the month, we added to Morgan Stanley ($MS) near $184.50 on October 26 and reset our checkpoint to $165. After Welltower ($WELL) delivered a beat-and-raise quarter, we used post-earnings weakness to add at $227.73, upgraded the shares to One and lifted our price target to $270 from $265.
Our Shopping List
As we fine-tune our shopping list, here’s what’s on it, listed alphabetically: Alphabet, Amazon, Eaton, Meta, Microsoft and ROBO.
For Amazon, we’re watching support near $240 on the weekly chart, and for Alphabet, we’re eyeing that same moving average near $265 also on the weekly chart. Eaton shares slipped below our checkpoint late in the month, and we’ll be listening closely to its Q3 2026 report on November 3.
With Meta, we’re watching to see if the shares deliver a positive test relative to their 50-day moving averages near $630, while with Microsoft, we’ll wait for a pullback that improves the risk-to-reward trade-off to our new $600 price target.
Marvell could make it onto that list, but the determining factors are whether a deal for Lumentum goes through, and if so, at what price. We discussed the various levers we’ll be watching should such a combination be announced.
While those are some of the existing holdings on our shopping list, two stocks that are not on the shopping list at this time are Broadcom and XLV. With AVGO, the Portfolio’s position is the largest among its chip holdings, but if there is no Marvell-Lumentum deal, odds are AVGO shares move higher on that news. As far as XLV goes, its current RSI level has the shares overbought, and if our position size were larger and the market mood different than it is currently, we’d look to trim. If the scenario we discussed in our Amazon earnings note plays out as we suspect it will, we’ll have an opportunity to pick up more XLV shares at better prices in the coming weeks.
Following the oversubscribed offerings from Meta and Microsoft, which bode well for investment banking fees, we’re contemplating adding to Bank of America ($BAC) as the shares build a base amid an oversold condition. With Nvidia ($NVDA), a move toward the 200-day moving average near $203 would have us considering adding to the position, and with Apple, a pullback near $331 would be a place to consider picking up shares, while a move near $320 offers a more compelling spot. We also have room to add more PCAR shares as clarity on the 2027 emissions rules and the October and November Class 8 order data arrive.
We also continue to do our work on SpaceX ($SPCX) and will have more to say on that in due course.
Ratings, Targets and Checkpoints
During October, we upgraded the First Trust Nasdaq Cybersecurity ETF ($CIBR) to a One rating, boosting our price target to $115 from $105 and our checkpoint to $85 from $75. Following the strong pre-order demand for the iPhone Duo, we lifted our Apple ($AAPL) price target to $375 from $350 and our checkpoint to $305. Microsoft’s ($MSFT) September-quarter beat led us to boost our price target to $600 from $500, while Alphabet’s free cash flow and funding questions led us to trim our GOOGL target to $380 from $410.
With an RSI reading above 78, we sold roughly one fifth of the Portfolio’s WM position near $240 on October 26, downgraded the shares to a Two and lifted our checkpoint to $210. After the company’s earnings miss on October 27, we trimmed our price target to $255 from $265.
Following Boeing’s ($BA) disappointing production outlook, we downgraded BA shares to a Three rating and removed our checkpoint. Rather than sell into an oversold condition, we will bide our time and as needed, use near-term strength in BA shares to reduce our exposure, treating them as a source of cash or funding for other Portfolio moves. Given our Three rating, should more favorable data points emerge, we’d be inclined to reconsider BA’s role in the Portfolio.
Upcoming Dividends
American Express ($AXP) will pay its next quarterly dividend on November 20 followed by Costco doing the same on November 13 as does Morgan Stanley ($MS). In the second half of November, we can look forward to dividend payments from Welltower ($WELL) on November 19 and just as you are recovering from your Thanksgiving meal, Eaton on November 27.
Key Global Economic Readings
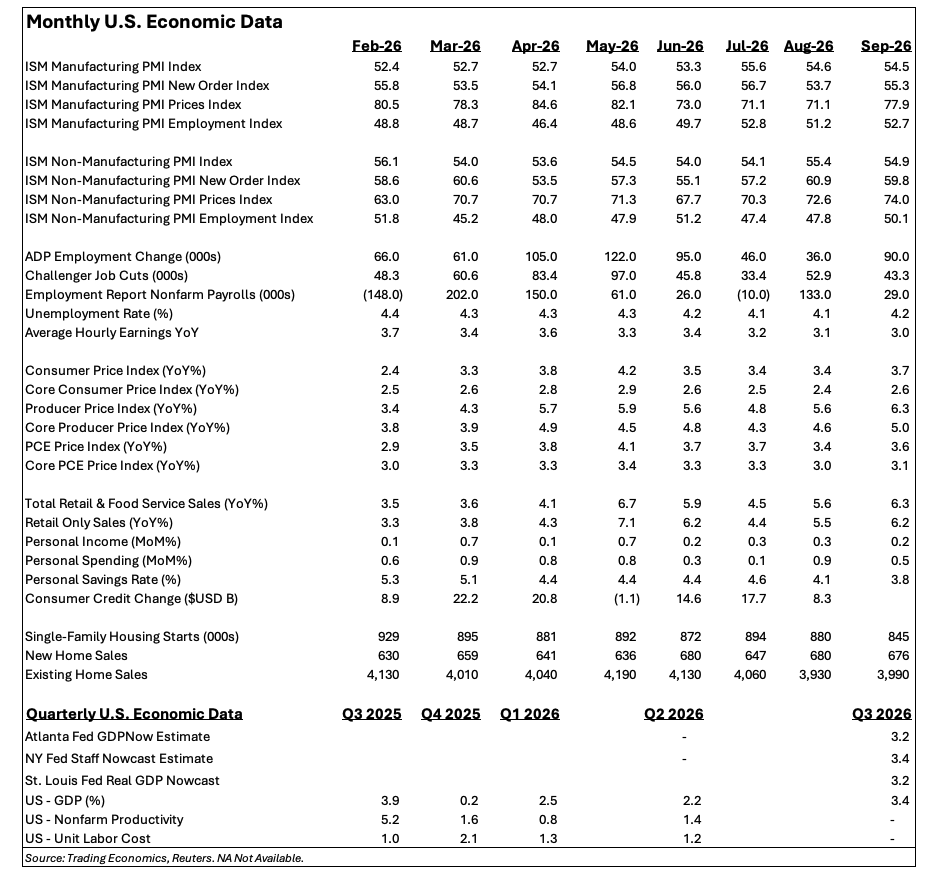
Chart of the Week: The SPY and RSP Come Together
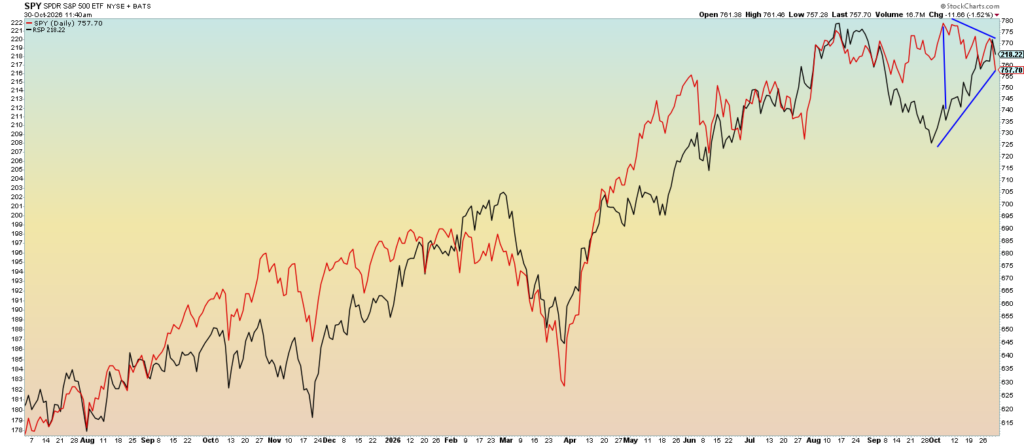
As the Beatles once said, ‘Come Together…Right Now’. The $SPY and $RSP have come back to join hands, the RSP being the beneficiary of money flows into “anything but tech” recently. Remember, the RSP is simply an equal-weighted S&P 500 index, where each member carries one vote. It is not predicated on market cap weighting like the SPY, which is top-heavy for technology names.
For a while this fall the two ETFs were separated, diverging in a way that focused more on the advent of AI, energy, IPOs (following SpaceX and the coming Anthropic/OpenAI) to drive the SPY to new highs. But you can’t leave all stocks behind, and while financial conditions have been relatively tight and liquidity not bountiful, money has been rotated around from the tech names to the “other” more “boring” groups.
First, the staples and homebuilders got some money flows and started to run, just after Labor Day. Retail stocks were next to follow, then defense names and consumer discretionary. Most of these groups lagged badly since the start of the year but have now made up some lost ground.
Yet, even as the RSP has now caught up to the SPY, they are both coming down as the markets face a corrective phase. If this happens, we could see the RSP outperforming the SPY but “down is down,” and if these ETFs decide to pull back together, we’ll be watching for some sort of bottoming pattern first. Not there just yet.
Other charts we shared with you this past week were:
Monday, October 26: Charting the Markets: Poor Weekly Closes Become a Pattern
Monday, October 26: Chart of the Day: Can Microsoft Save the Magnificent Seven?
Tuesday, October 27: Chart of the Day: Waste Management Proves Garbage Is Hot
Wednesday, October 28: Chart of the Day: Is This the Right Spot for Applied Materials?
Thursday, October 29: Chart of the Day: Hiding Out in Healthcare Has Been Profitable
The Week Ahead
November kicks off with a busy week, and it could be a pivotal one for a market that has spent the last several days digesting AI-related disappointments. Along with Tuesday’s midterm elections, we’ll get the October ISM Manufacturing and Services reports on Monday and Wednesday, respectively. Given the continued climb in energy prices and the growing number of companies discussing pricing action, we’ll be paying particularly close attention to their prices components.
The week also brings a heavy dose of labor market data, including September JOLTS on Tuesday, October ADP on Wednesday, Q3 productivity and unit labor costs on Thursday and the October Employment Situation report on Friday, which is expected to show roughly 65,000 jobs added and an unemployment rate of 4.2%. With GDP growing at its fastest pace in a year and hiring barely moving, the labor market is the missing piece of the growth story, so Friday’s report matters.
All of it will be read through the lens of a Fed that held rates in October but has a December rate hike priced in, following Friday’s hawkish comments from Logan, Musalem and Barkin, and should the data run hot, expectations could shift toward something more than a 25-basis-point move.
Also on the docket are the Fed’s Senior Loan Officer Survey on Monday, the Treasury’s quarterly refunding, the Eurozone flash October CPI on Wednesday and the Bank of England’s decision on Thursday.
Here’s a closer look at the economic data coming at us next week:
U.S.
Monday, November 2
S&P Global U.S. Manufacturing PMI – Final (Oct.) – 9:45 AM ET
ISM Manufacturing Index (Oct.) – 10:00 AM ET
Construction Spending (Sept.) – 10:00 AM ET
Senior Loan Officer Opinion Survey on Bank Lending Practices (Oct.) – 2:00 PM ET
Tuesday, November 3
ADP Employment Change Report (Weekly) – 8:15 AM ET
JOLTS Job Openings (Sept.) – 10:00 AM ET
Factory Orders (Sept.) – 10:00 AM ET
Wednesday, November 4
MBA Mortgage Applications (Weekly) – 7:00 AM ET
ADP Employment Change (Oct.) – 8:15 AM ET
International Trade in Goods & Services (Sept.) – 8:30 AM ET
S&P Global U.S. Services & Composite PMI – Final (Oct.) – 9:45 AM ET
ISM Services Index (Oct.) – 10:00 AM ET
EIA Crude Oil Inventories (Weekly) – 10:30 AM ET
Thursday, November 5
Challenger Job Cuts (Oct.) – 7:30 AM ET
Initial & Continuing Jobless Claims (Weekly) – 8:30 AM ET
Productivity & Unit Labor Costs – Preliminary (Q3) – 8:30 AM ET
EIA Natural Gas Inventories (Weekly) – 10:30 AM ET
Friday, November 6
Employment Situation Report (Oct.) – 8:30 AM ET
University of Michigan Consumer Sentiment – Preliminary (Nov.) – 10:00 AM ET
Consumer Credit (Sept.) – 3:00 PM ET
International
Saturday, October 31
China: NBS Manufacturing & Non-Manufacturing PMI (Oct.)
Monday, November 2
China: RatingDog Manufacturing PMI (Oct.)
Germany: Retail Sales (Sept.)
Germany: Manufacturing PMI – Final (Oct.)
Eurozone: Manufacturing PMI – Final (Oct.)
U.K.: Manufacturing PMI – Final (Oct.)
Wednesday, November 4
China: RatingDog Services & Composite PMI (Oct.)
Germany: Services & Composite PMI – Final (Oct.)
Eurozone: Services & Composite PMI – Final (Oct.)
Eurozone: CPI – Flash (Oct.)
U.K.: Services & Composite PMI – Final (Oct.)
Thursday, November 5
Japan: Manufacturing PMI – Final (Oct.)
Japan: Bank of Japan Monetary Policy Meeting Minutes
Germany: Factory Orders (Sept.)
Eurozone: Producer Price Index (Sept.)
U.K.: Construction PMI (Oct.)
U.K.: Bank of England Interest Rate Decision & Monetary Policy Report
Friday, November 6
Japan: Average Cash Earnings (Sept.)
Japan: Services & Composite PMI – Final (Oct.)
Germany: Industrial Production (Sept.)
Eurozone: Retail Sales (Sept.)
U.K.: Halifax House Price Index (Oct.)
This week, earnings season shifts from the hyperscalers to chips, industrials and the consumer, with more than 100 S&P 500 companies reporting. Five Portfolio holdings report during the week: Apple ($AAPL) and Palantir Technologies ($PLTR) after Monday’s close, Eaton ($ETN) before Tuesday’s open, Arista Networks ($ANET) after Tuesday’s close and Axon (AXON) after Thursday’s close.
With Apple, our focus will be December-quarter guidance, the iPhone Duo’s contribution and what management says about memory costs and margins. For Palantir, it’s U.S. commercial revenue growth and remaining deal value; for Eaton, data center orders and its electrical backlog. At Arista, backlog, deferred revenue, component constraints and 2027 visibility will be top of mind, while for Axon it will be future contracted bookings, annual recurring revenue and margins.
CIBR holding Check Point Software ($CHKP) reports on Monday. Tuesday, we have EPS All-Stars residents Advanced Micro Devices ($AMD) and Astera Labs ($ALAB) with Lumentum ($LITE) on Thursday. Lumentum management has already said the company is sold out through 2029, but news on a potential deal with Marvell ($MRVL) will be front and center for us next week. Read-throughs from Qualcomm ($QCOM), Super Micro Computer ($SCCI), Cummins ($CMI) and Parker-Hannifin ($PH) will be on our radar too, as will Costco’s ($COST) October sales report, which we expect after Wednesday’s market close. Across all of them, we’ll be listening for how management teams talk about capex funding and returns, since that’s the question that drove the market in October.
Here’s a closer look at the earnings reports coming at us next week:
Monday, November 2
Open: Check Point Software (CHKP), Entergy (ETR), Estée Lauder (EL), Fox Corp. (FOXA), Marriott International (MAR)
Close: Apple (AAPL), Diamondback Energy (FANG), ON Semiconductor (ON), Palantir Technologies (PLTR), Realty Income (O), Vertex Pharmaceuticals (VRTX), Williams Companies (WMB)
Tuesday, November 3
Open: Ametek (AME), Apollo Global Management (APO), Eaton (ETN), Fiserv (FISV), Keurig Dr Pepper (KDP), Marathon Petroleum (MPC), Pfizer (PFE), Sysco (SYY), Waters (WAT), Yum! Brands (YUM)
Close: Advanced Micro Devices (AMD), American International Group (AIG), Amgen (AMGN), Arista Networks (ANET), Astera Labs (ALAB), Block (XYZ), Booking Holdings (BKNG), Mosaic (MOS), Prudential Financial (PRU), Super Micro Computer (SMCI)
Wednesday, November 4
Open: Cencora (COR), CVS Health (CVS), Datadog (DDOG), Emerson Electric (EMR), Kraft Heinz (KHC), McDonald’s (MCD), Uber Technologies (UBER), W.W. Grainger (GWW), Zimmer Biomet (ZBH)
Close: Aflac (AFL), Allstate (ALL), AppLovin (APP), CF Industries (CF), DoorDash (DASH), Edwards Lifesciences (EW), Expedia (EXPE), McKesson (MCK), MetLife (MET), Motorola Solutions (MSI), Qualcomm (QCOM)
Thursday, November 5
Open: Air Products & Chemicals (APD), Becton Dickinson (BDX), Cardinal Health (CAH), Cigna (CI), ConocoPhillips (COP), Cummins (CMI), Duke Energy (DUK), Global Payments (GPN), Parker-Hannifin (PH), Ralph Lauren (RL), Rockwell Automation (ROK), Sempra (SRE), Southern Company (SO), Tapestry (TPR), Targa Resources (TRGP), Zoetis (ZTS)
Close: Airbnb (ABNB), Axon Enterprise (AXON), Devon Energy (DVN), EOG Resources (EOG), Lumentum (LITE), Microchip Technology (MCHP), Simon Property Group (SPG), Wynn Resorts (WYNN)
Friday, November 6
Open: Humana (HUM), Moderna (MRNA)
Portfolio Investor Resource Guide
Economic Data: Here’s a List of Links to the Key Economic Data We Closely Watch
Investing Terminology: 16 Key Terms Club Members Should Know
10-Ks: Want to Know About a Stock? Read the Company’s Reports
10-Qs: Unlock the Numbers and Key Information Behind Your Stock With the 10-Q
Income Statement: Our Cheat Sheet to Understanding This Financial Document
Balance Sheet, Cash Flow Statements, and Dividends: How to Know If a Company Is Off-Kilter? Read Its Balance Sheet
Valuation Metrics: Everyone Wants a Value. Here’s How Investors Can Find
Thematic Investing 101 Webinar
Like the Benefits of ETFs? Let’s Talk About Models
The Portfolio Ratings System
1 – Buy Now (BN): Stocks that look compelling to buy right now.
2 – Stockpile (SP): Positions we would add to on pullbacks or a successful test of technical support levels.
3 – Holding Pattern (HP): Stocks we are holding as we wait for a fresh catalyst to make our next move.
4 – Sell (S): Positions we intend to exit.
ONES
American Express AXP; $319.11; 760 shares; 4.16%; Sector: Financial Services
UPDATE: Shares of American Express ($AXP) climbed mid-single digits in October, making them a strong performer for the Portfolio as they outperformed the major market indices. The month started with a regulatory overhang being resolved. On October 8, Amex agreed to consent orders with the Federal Reserve and the OCC tied to its financial crimes compliance program, with American Express National Bank paying a $350 million civil penalty. Importantly, there’s no asset cap, and management later confirmed the penalty doesn’t affect its 2026 guidance, nor are remediation costs expected to weigh on 2027. That set the stage for Amex’s October 23 report, in which it delivered record Q3 2026 revenue of $20.1 billion, up 9% year over year, and adjusted EPS of $4.68, up 13% and $0.18 ahead of consensus expectations. Amex lifted its GAAP EPS guidance to $18.30–$18.60, which equates to $17.60–$17.90 on an adjusted basis vs. the prior $17.30–$17.90, while reaffirming 10% revenue growth for the year. The key metric for us, net card fee revenue, accelerated to 17% growth on an FX-adjusted basis from 15% in Q2, the second-half inflection management called for at the start of the year. The average fee per card climbed to $136, Amex acquired 3.1 million new cards with a record 76% on fee-paying products, and billed business rose 8%, led by travel and entertainment. Amex also unveiled an exclusive partnership with Airbnb that brings more than 1 million listings into Amex Travel, and it’s eliminating about 5% of its positions as it leans on AI across customer acquisition, servicing and payments. To us, that combination of accelerating fee revenue and a leaner cost structure sets the stage for favorable operating leverage and EPS growth in 2027. With net card fees accelerating and Amex’s membership model far less dependent on cardholder spending than Visa or Mastercard, we reiterated our $400 price target and One rating. We’ll also point out that exiting October, AXP shares were trading at 15.8x expected 2027 consensus EPS compared to more than 24x for Visa and more than 27x for Mastercard despite double-digit EPS growth prospects at Amex. Because the position is rather full near 4% of the Portfolio’s assets, we aren’t inclined to add more AXP shares, but a pullback near $300 would be a compelling pick-up point for patient investors. As we head into the holiday spending season, we’ll be watching for continued gains in the average fee per card and cards in force.
October Price Change: 4.94%; Yield: 1.25%
INVESTMENT THESIS: American Express is a globally integrated, membership-driven payments company, providing customers with access to products, insights, and experiences that enrich lives and build business success. The company has four reportable operating segments: U.S. Consumer Services (USCS), Commercial Services (CS), International Card Services (ICS), and Global Merchant and Network Services (GMNS). American Express targets the premium consumer space by continuing to deliver membership benefits that span our customers’ everyday spending, borrowing, travel, and lifestyle needs, expanding its roster of business partners around the globe, and developing a range of experiences that attract high-spending customers. In 2025, the company’s net card fee revenue accounted for 72% of its pre-tax income, which we see as providing a differentiated business model that should continue to grow as Amex wins new card members and drives its average fee per card higher.
Target Price: Reiterate $400; Rating: One
Checkpoint: $275
RISKS: Slowdown in consumer spending, competition, membership growth, merchant acceptance, and lack of new product innovation.
Applied Materials AMAT; $390.09; 545 shares; 3.64%; Sector: Semiconductors
UPDATE: Applied Materials ($AMAT) tumbled more than 20% in October as the shares were caught in the month’s pronounced selloff in chip and AI infrastructure stocks despite a string of positive industry data points. The key company event was Applied’s SEMICON West investor breakfast on October 13, where it set new 2030 targets calling for roughly 54% non-GAAP gross margin, 40% operating margin, more than two points of WFE share gains, services revenue above $12 billion and returning 80%-100% of free cash flow. Management also shared that leading-edge logic and DRAM fabs are running at 100% utilization and that Applied is raising prices. Shortly thereafter, AMD CEO Lisa Su said chip demand is higher than supply, Samsung guided to a near nine-fold jump in Q3 operating profit, TSMC posted a 51% jump in September-quarter revenue, and ASML said orders for its tools reach into 2030 and that it can’t fully meet demand in 2027-2028. With those data points in hand and the shares well off their highs, we added to the Portfolio’s AMAT position near $426 on October 15, reiterated our One rating and reset our checkpoint to $375. Later in the month, Lam Research delivered record revenue and called for 2026 WFE spending in the mid-$150 billion range and more than $200 billion in 2027, led by DRAM, with 10 new Tier 1 fabs next year. That 2027 call bodes well for Applied. Late in the month, Applied said it plans to raise its stake in BE Semiconductor Industries (BESI) to about 20% from 9%, subject to U.S. antitrust review, expanding a hybrid bonding collaboration that dates back to 2020 into new chip-connection and packaging technologies for next-generation AI semiconductors. To us, this deepens Applied’s reach in advanced packaging, a smaller but fast-growing business that management has guided to grow more than 70% this year. The chip shortage commentary only intensified on October 28, when SK Hynix said memory shortages should persist through at least 2030 as it invests heavily in capacity after selling out through 2029, and ASM International said it would reach its 2030 sales target three years early as customers move quickly to increase output. Seeing that as pointing to another leg up in chip equipment spending, we added more AMAT shares near $402, well below the Portfolio’s cost basis, and reset our checkpoint to $360. Our view is that chip capacity will remain tight for some time, which supports pricing and margin expansion even if growth proves lumpy given cleanroom and supply chain constraints. Put another way, full fab utilization and higher pricing should give way to operating leverage as WFE spending climbs toward that $200 billion level in 2027. The month closed with Intel saying data center chip supply is constrained into 2028, that its 2026 capex remains on track for $20 billion and that 2027 capital spending should be up strongly. Add in Amazon flagging higher memory costs, and those comments keep us bullish on AMAT, as Applied supplies the equipment memory makers need to add capacity. Next up is Applied’s October-quarter report, expected around November 12, where we’ll look for order and backlog commentary as well as its initial view on 2027.
October Price Change: -23.72%; Yield: 0.41%
INVESTMENT THESIS: The outlook for semiconductor capital equipment, an industry that delivered ~$133 billion in 2025, remains very bright. SIA sees industry deliveries rising to $145 billion this year and $156 billion in 2027, and others see a continued step function higher through 2030. Underpinning that forecast is continued spending on AI and data centers, and corresponding equipment, as well as other connected devices, including appliances as well as cars and trucks. Applied Materials holds a leading position in the global semiconductor wafer fabrication equipment (WFE) market, with a market share estimated at approximately 19% in 2025. As a broad-portfolio supplier, it dominates in deposition (44% share) and maintains a strong presence in etch, CMP, and ion implantation tools. Major customers include TSMC, Samsung, Intel, SK Hynix, and Micron, along with key partnerships involving Apple and Texas Instruments.
Target Price: Reiterate $800; Rating: One
Checkpoint: $360
RISKS: Customer capital spending levels, currency, and economic risk.
Axon Enterprise AXON; $427.77; 535 shares; 3.92%; Sector: Aerospace & Defense
UPDATE: Shares of Axon Enterprise ($AXON) were little changed in October, but that masks their fall near $380 mid-month and the sharp snapback in the following weeks. Fueling that rebound was a series of project win announcements, including ones in corrections and the federal space. Axon announced corrections deployments in New York, Ohio, Maryland and North Carolina, with New York’s deployment spanning 42 facilities and 15,000 officers, and Maryland adopting Body 4 cameras across all 17 facilities after a trial that saw staff assaults fall 40%. With the shares near oversold territory, we used those wins to add to the Portfolio’s position near $408 on October 8 and reset our checkpoint to $360 from $380. A week later, Axon shared that federal agencies have added more than 22,000 body-worn cameras and digital evidence management licenses this year, DHS selected the Dedrone counter-drone platform under an IDIQ contract, and the VA added more than 1,600 TASER 10 devices. Those wins add to future contracted bookings and speak to Axon’s push into federal, one of its key growth vectors alongside international and enterprise, which led us to round out the position at $410 on October 15. The Dedrone award also fits with the U.S. Army’s testing of counter-drone technology on the U.S.-Mexico border, with the counter-UAS market forecast to grow from $6.6 billion in 2025 to $20.3 billion in 2030. At the IACP 2026 conference in Orlando, Axon launched Axon Body 5, which offers roughly 25 times the AI processing power and about 20% longer battery life than its predecessor, along with Axon Guardian, a set of real-time officer safety tools. To us, each new hardware generation and AI feature lifts the value of Axon’s software bundles, and that’s what drives annual recurring revenue and margin expansion over time. As for the reported Flock Safety sale process, there were no updates during the month. As we’ve discussed, we see the PEG ratio as the right way to value AXON shares. At roughly $428, the shares trade at a PEG near 1.1 on 2028 consensus EPS of $14, which reinforces our view that the risk-to-reward trade-off remains compelling. Next up is Axon’s Q3 2026 report after the market close on November 5, where we’ll be focused on future contracted bookings, which stood at $15.1 billion exiting Q2, as well as annual recurring revenue and software attach rates.
October Price Change: 1.24%; Yield: N/A
INVESTMENT THESIS: Axon Enterprise develops, manufactures, and sells conducted energy devices and cloud-based digital evidence management software designed for use by law enforcement, corrections, military forces, private security personnel, and private individuals for personal defense. The company operates in two segments: Taser (recently renamed Connected Devices) and Software & Sensors (recently renamed Software & Services). Taser develops and sells CEDs used for protecting users and virtual reality training. Software & Sensors manufactures fully integrated hardware and cloud-based software solutions such as body cameras, automated license plate reading, and digital evidence management systems. Axon delivers its products worldwide and gets most of its revenue from the United States. According to Mordor Intelligence, the wearable and body-worn cameras market on its own was valued at $1.62 billion in 2020 and is expected to reach $424.63 billion by 2026. Public safety organizations are increasingly adopting cloud solutions, leading to significant spending in this area. The digital spending in public safety is projected to reach $201 billion by 2027.
Target Price: Reiterate $700; Rating: One
Checkpoint: $360
RISKS: Manufacturing and supply chain, competitive factors, government regulation, and technology change.
Broadcom Inc. AVGO; $326.08; 665 shares; 3.72%; Sector: Technology
UPDATE: Shares of Broadcom ($AVGO) moved up and down during October, hitting a high near $380 and a low near $320 before rebounding to close the month down mid-single digits. That volatile performance reflects the shares getting caught in the crosshairs of the market’s growing concerns over AI financing and capital needs. On October 12, CEO Hock Tan said at a Singapore conference that capital will be the biggest constraint as AI development continues, even as he described compute demand as insatiable through the end of the decade. Those comments added to the pressure on chip stocks, but we saw that more as a sentiment hit than a demand issue. Applied Materials’ comments about tight chip capacity at SEMICON West bode well for Broadcom’s custom silicon and networking businesses. With the shares retreating, we added more to the Portfolio near $335 on October 19. Anthropic’s S-1 disclosures showed obligations of more than $160 billion to lease Google chips in a deal involving Broadcom, and its public S-1 filing on October 26 put those commitments near $161 billion. That reaffirms that Anthropic is expected to become Broadcom’s largest XPU customer in 2027. The financing behind that relationship came into focus on October 27, when Bank of America, Blackstone, Citi and Morgan Stanley agreed to provide $63 billion to fund Anthropic’s purchases of Broadcom’s AI chips and networking gear. Pairing those funding announcements with Celestica’s beat-and-raise quarter, including an initial 2027 revenue outlook of $40 billion, up 90%, and Cadence Design’s record backlog, we added another slug of AVGO shares near $340 on October 27, keeping our $300 checkpoint. Nokia’s comments that AI and cloud networking demand exceeds supply also point to a robust opportunity for Broadcom’s networking business. On October 28, reports that OpenAI plans to buy Google’s AI chips pointed to more customers turning to suppliers beyond the sold-out Nvidia, a clear positive for the TPUs Broadcom builds with Google. The hyperscalers then confirmed that demand. Alphabet said TPU system sales were a meaningful contributor to Google Cloud’s 103% revenue growth, nearly 100 customers now use TPUs, including Anthropic both directly and via Broadcom, and TPU sales should ramp meaningfully in 2027. Alphabet also expects capex to rise significantly in 2027 from this year’s $195 billion-$205 billion, while Microsoft and Amazon both pointed to higher spending in 2027 and said demand still exceeds available capacity. Here’s the thing: all of that capacity needs high-speed networking, and Microsoft alone added 24 new data centers in the September quarter. Next up are the Anthropic IPO roadshow and Broadcom’s October-quarter report in December, where we’ll look for an update on its 2027 AI revenue outlook. We’ll stay mindful of the Portfolio’s overall chip exposure across AVGO, MRVL, NVDA and AMD in the EPS All-Stars basket, but a pullback toward the low $320s, where the shares bottomed this month, would have us considering adding to the position.
October Price Change: -7.15%; Yield: 0.74%
INVESTMENT THESIS: We became shareholders in Broadcom to participate as the company benefits from the buildout of digital infrastructure, including AI, data center, and custom AI chips, as well as demand for its software and services segment, which includes private cloud, mainframe software, cybersecurity, and enterprise software. Broadcom reports its business in two segments – Semiconductor Solutions (58% of sales and 51% of operating income) and Infrastructure Software (42%, 49%). The Broadcom management team has developed a track record of delivering organic growth and growth by acquisition, with the latter positioning the company to better position itself to meet developing demands. More recent acquisitions include Brocade Communications, CA, Inc., Symantec Enterprise Security, and VMware.
Target Price: $525; Rating: One
Checkpoint: $300
RISKS: Economic, governmental regulations, geopolitical developments, cyclical, and investment risk.
Costco Wholesale COST; $1,015.94; 230 shares; 3.99%; Sector: Consumer Staples
UPDATE: Shares of Costco Wholesale ($COST) climbed low-double digits in October as the shares rebounded from just above our $900 checkpoint exiting September back above $1,000. One of the key catalysts behind that outsized rebound was Costco’s September sales report on October 7. Net sales for the five weeks rose 13% to $30.02 billion, and adjusted comparable sales accelerated to 7.6% for the total company and 8.0% in the U.S., up from 5.4% and 5.6% in August. Those figures were on top of 6.0% adjusted total comps in September 2025, and digitally enabled sales climbed 19%. As we noted at the time, it’s hard to argue Costco isn’t taking consumer wallet share, especially compared to PepsiCo’s organic revenue decline and the anemic same-store sales from Domino’s and Albertsons. That share-taking perspective was further reinforced by the 6.2% year-over-year gain captured in Retail-only sales in the September Retail Sales report. Looking to the holidays, the National Retail Federation forecasts sales will rise 4.2% to $1.013 trillion, up from last year’s 3.1% increase. With wage growth lagging inflation, we expect consumers will spread their holiday shopping between October and December and lean further into value. That plays to Costco’s strengths, as does its gasoline business with diesel and gas prices well above year-ago levels. Rising food inflation, with the FAO Food Price Index up more than 5% year over year in September, is another reason we see more shoppers turning to Costco to stretch their spending dollars. In September, we said that depending on what the September sales report brought, we may top off our COST exposure. The strength in that report and the rebound in the shares meant we did not get the opportunity at the levels we were targeting, but we will continue to evaluate. Costco will pay its quarterly dividend of $1.47 per share on November 13 to shareholders of record as of October 30. As we move into the heart of the holiday shopping season, we’ll be watching Costco’s October sales report in early November and the November one in early December for continued comp strength, traffic trends and the pace of warehouse growth, which remains the key to membership fee income now that the benefit from the 2024 fee increase has lapped.
October Price Change: 11.60%; Yield: 0.65%
INVESTMENT THESIS: We like Costco’s long-term prospects, driven by a club-based operating model that focuses on volumes, not margins, and therefore offers its customers a value proposition of everyday low prices. The strength of this model has created an incredibly loyal customer base with low churn and continued share gains in both brick-and-mortar and e-commerce. This is a global concept, evidenced by the strength of sales both in the U.S. and abroad, which includes an emerging China opportunity. We see the company’s membership model as a key differentiator versus other retailers, and its plans to open additional warehouse locations in the coming quarters should drive retail volumes and the higher-margin membership fee income as well. We also appreciate management’s approach to capital returns and their willingness to return cash.
Target Price: Reiterate $1,150; Rating: One
Checkpoint: $900
RISKS: Inability to pass through higher costs, fuel prices, weaker consumer, and membership churn.
First Trust Nasdaq Cybersecurity ETF CIBR; $100.26; 2,435 shares; 4.22%; Sector: Cybersecurity
UPDATE: Shares of the First Trust Nasdaq Cybersecurity ETF ($CIBR) gave back some of their Q3 2026 gains, slipping 2.8% even after a string of thesis confirming developments. Early in the month, Zscaler reaffirmed its fiscal Q1 and 2027 guidance at its investor day and called agentic AI its biggest opportunity. Cybersecurity M&A also continued, with IonQ agreeing to buy Elisity in a deal valued at up to $1.3 billion and Momentum Cyber forecasting more than 450 cybersecurity deals this year, up from 404 in 2025. Mid-month, a report that OpenAI plans to buy a cybersecurity startup weighed on the group. Then came a wave of AI-driven attacks. An AI agent-driven hacking spree hit more than 100 companies, including Deere, SharkNinja and Cummins, and Ahold Delhaize’s Albert Heijn online delivery outage stretched to at least 11 days. Despite that string of positive developments, CIBR shares fell sharply in a matter of days from the $110 area to $100, prompting us to upgrade the shares to a One rating, boost our price target to $115 from $105 and lift our checkpoint to $85 from $75 on October 19. Because the position was already just over 4% of the Portfolio’s assets, we did not add shares, but we flagged the pullback as a good entry point for those underweight CIBR. Days later, critical PHP vulnerabilities uncovered using AI triggered millions of hacking attempts, prompting governments to take websites offline and the NSA to issue an advisory, while U.S. banks reported detecting unauthorized third-party AI agents inside customer accounts. Closing out the month, Anthropic disclosed that its Claude model accessed publicly available Georgia voter data without human authorization, another reminder of the growing concerns over AI security. Then on October 30, Binance suspended all deposits and withdrawals as it investigated a roughly $6.3 billion hack, the biggest cyber heist on record, a sharp reminder of how cyberattacks can hobble a company’s business and why companies will need to pony up to protect their crown jewels. As we see it, AI usage by bad actors is expanding both the vector and the velocity of attacks, which reaffirms our view that cybersecurity should be a part of every investor’s portfolio. As the shares rebounded in the back half of the month, the position grew to more than 4.4% of the Portfolio’s assets, and we flagged that should it breach 4.5%, some prudent action will be required. Upcoming catalysts include quarterly results from CIBR holdings Check Point Software on November 2, followed by Palo Alto Networks, CrowdStrike and Zscaler later in the quarter. We will be listening for comments on new orders, backlog and how AI is reshaping demand. As we assess those results, we’ll review our $115 price target as needed.
October Price Change: -2.75%; Yield: 0.29%
INVESTMENT THESIS: The First Trust Nasdaq Cybersecurity ETF seeks investment results that correspond generally to the price and yield (before the fund’s fees and expenses) of an equity index called the Nasdaq CTA Cybersecurity Index. The Nasdaq CTA Cybersecurity Index is designed to track the performance of companies engaged in the cybersecurity segment of the technology and industrial sectors. It includes companies primarily involved in the building, implementation, and management of security protocols applied to private and public networks, computers, and mobile devices to protect the integrity of data and network operations. To be included in the index, a security must be listed on an index-eligible global stock exchange and classified as a cybersecurity company as determined by the Consumer Technology Association. Each security must have a worldwide market capitalization of $250 million, have a minimum three-month average daily dollar trading volume of $1 million, and have a minimum free float of 20%.
Target Price: $115; Rating: One
Checkpoint: $85
RISKS: Cybersecurity spending, technology and product development, the timing of the product sales cycle, new products, and services in response to rapid technological changes and market developments, as well as evolving security threats.
Marvell Technology MRVL; $196.40; 945 shares; 3.18%; Sector: Technology
UPDATE: Shares of Marvell Technology ($MRVL) tumbled in October, as a strong start gave way to the AI infrastructure selloff, but it was the October 29 speculative report about the company acquiring EPS All-Stars resident Lumentum that dragged the shares down mor than 20% for the month. At its October 6 Investor Day, Marvell raised its fiscal 2028 revenue forecast to about $20 billion and introduced a fiscal 2031 forecast of $70-$90 billion, with the midpoint well above the $46.85 billion Street estimate. We held our $340 price target, preferring to first hear custom silicon comments from Amazon, Meta and Alphabet later in the month when they reported their Q3 2026 results. As MRVL shares gave back those gains and then some on AI capital and financing concerns, we added to the Portfolio’s MRVL position near $239 on October 19 and reset our checkpoint to $175. With the shares back in the $226-$234 range we flagged in September, the funding deals for Anthropic-Broadcom, Meta and SpaceX, along with Celestica’s beat-and-raise quarter, gave us the confidence to add again near $238 on October 27 and upgrade MRVL shares to One from Two. The custom silicon data points soon followed. On October 28, reports that OpenAI plans to buy Google’s AI chips showed customers looking beyond the sold-out Nvidia, and Alphabet said nearly 100 customers now use its TPUs, with sales set to ramp meaningfully in 2027. Despite that, MRVL shares came under renewed pressure on October 29 following a report that Marvell is in advanced talks to buy Lumentum. Strategically, a deal would secure direct access to Lumentum’s sold-out optical capacity and strengthen Marvell’s footing inside Google’s TPU efforts. But as we laid out in our note discussing the speculative report, it comes down to how much Marvell is willing to pay or even if it proceeds with the transaction. Per market reports, we may hear more on this potential move next week. If a deal emerges, we’ll judge it on price paid, synergies and dilution. If it doesn’t, we’d be inclined to use the renewed pressure to round out the Portfolio’s MRVL position, with Google’s TPU comments, Amazon’s Trainium outlook and rising AI capex providing ample cover. During Amazon’s Q3 2026 earnings call on October 29, it was clear that custom silicon is a big part of the story, with Trainium and Graviton revenue commitments each up more than 20x and plans to sell Trainium outside of AWS starting late 2027. Given Marvell’s custom AI work with AWS, that’s a positive read for our MRVL position.
October Price Change:-25.67%; Yield: 0.09%
INVESTMENT THESIS: Marvell is a fabless supplier of high-performance standard and semi-custom infrastructure semiconductor solutions. These solutions power the data economy, enabling the data center, carrier infrastructure, enterprise networking, consumer, and automotive/industrial end markets. With roughly 75% to 80% of Marvell’s revenue stream tied to digital infrastructure, we see it continuing to benefit from rising content consumption and creation. Pointing to that rising demand that necessitates network densification and the build of digital infrastructure, Ericsson sees global monthly average usage per smartphone reach 46 gigabytes (GB) by the end of 2028, versus 19 GB in 2023 and 15 GB in 2022.
Target Price: $340; Rating: One
Checkpoint: $175
RISKS: Technology risk, customer risk, competition risk, reliance on manufacturing partners, and supply chain constraints.
Nvidia Corp. NVDA; $204.64; 970 shares; 3.40%; Sector: Technology
UPDATE: Like other holdings benefiting from the build of AI and data center infrastructure, shares of Nvidia ($NVDA) had a favorable start to October, hitting a record high early in the month. However, they retreated as the market grew concerned over AI financing, a spike in CoreWeave bond yields and Meta’s negative free cash flow. Quarterly results from Alphabet and Amazon added to those concerns, and NVDA finished the month down more than 10%. Early in the month, Nvidia agreed to acquire Hugging Face for about $12.9 billion, and SpaceX was reported to be seeking $40 billion to buy Nvidia chips. On October 20, Reuters reported that ByteDance, Alibaba and Tencent ordered more than 3 million RTX PRO 5500 cards worth more than $35 billion, but Nvidia warned it may fill only 5%-10% of those orders. To us, that confirms Nvidia is running flat out and remains capacity constrained. Anthropic then agreed to spend up to $86 billion renting Nvidia chips through Nscale and Lambda, and CEO Jensen Huang told CNBC that neocloud demand is “off the charts” and that capital, not demand, is the constraint, a view echoed by SpaceX closing $40 billion in debt financing for GPUs. The month closed with hyperscaler reports that pointed to more spending, not less. Microsoft installed its first Vera Rubin GPUs and expects capex to total about $170 billion in calendar 2026 before accelerating again in the first half of 2027, while Alphabet and Meta signaled significant capex step-ups for 2027. So did Amazon, which is installing an AI accelerator about every 14 seconds and continues to deploy Nvidia GPUs even as its own Trainium chips take on more of AWS’s AI work. Meanwhile, SK Hynix said shortages of the memory crucial to Nvidia’s accelerators should persist through at least 2030, and Samsung said its HBM supply is sold out for next year. Oracle is adding Google and Cerebras chips alongside Nvidia’s, and Google now counts nearly 100 TPU customers, but to us, customers diversifying is less a demand issue than a reflection of how sold out Nvidia remains. Next up is Nvidia’s October-quarter report, likely around November 18, for which the company has guided revenue of $108 billion, plus or minus 2%. With the shares well off their early-month record, a move toward the 200-day moving average near $203 would have us consider adding additional NVDA shares. That said, we’ll stay mindful of the Portfolio’s overall AI chip exposure across Broadcom, Marvell and Nvidia as well as AMD in the EPS All-Stars basket.
October Price Change: -10.39%; Yield: 0.44%
INVESTMENT THESIS: Nvidia is well-positioned to benefit from ramping AI and data center spending. The company pioneered accelerated computing to help solve the most challenging computational problems. Nvidia is now a full-stack computing infrastructure company with data-center-scale offerings that are reshaping the industry. The company’s full stack includes the foundational CUDA programming model that runs on all Nvidia GPUs, as well as hundreds of domain-specific software libraries, software development kits, or SDKs, and Application Programming Interfaces, or APIs. This deep and broad software stack accelerates the performance and eases the deployment of Nvidia accelerated computing for computationally intensive workloads such as artificial intelligence, model training and inference, data analytics, scientific computing, and 3D graphics, with vertical-specific optimizations to address industries ranging from healthcare and telecom to automotive and manufacturing. Nvidia reports in two business segments: Compute & Networking and Graphics. The Compute & Networking segment (78% of revenue, 85% of operating income) is comprised of Data Center accelerated computing platforms and end-to-end networking platforms, including Quantum for InfiniBand and Spectrum for Ethernet; NVIDIA DRIVE automated-driving platform and automotive development agreements; Jetson robotics and other embedded platforms; Nvidia AI Enterprise and other software; and DGX Cloud software and services. The Graphics segment (22% of revenue, 15% of operating income) includes GeForce GPUs for gaming and PCs, the GeForce NOW game streaming service and related infrastructure; Quadro/NVIDIA RTX GPUs for enterprise workstation graphics; virtual GPU, or vGPU, software for cloud-based visual and virtual computing; automotive platforms for infotainment systems; and Omniverse Enterprise software for building and operating metaverse and 3D internet applications.
Target Price: $300; Rating: One
Checkpoint: $175
RISKS: Market and interest rate risk, credit risk, country risk, and operational risk, including cybersecurity.
Paccar Inc. PCAR; $101.91; 1,470 shares; 2.57%; Sector: Industrials
UPDATE: Shares of Paccar ($PCAR) fell 7.2% in October, as the shares remained under pressure for much of the month. The first data point came on October 5 with preliminary September Class 8 orders, the first full month of model-year 2027 ordering. As we explained in our October 20 alert, roughly 73% of domestic freight tonnage moves by truck, and new heavy-duty trucks are 15%-25% more fuel-efficient than 2014 models. The October Flash PMI data from S&P Global confirmed sustained strong expansion in manufacturing production and new orders, and AB Volvo reported North American truck deliveries up 42%. Those data points led us to pick up additional PCAR shares for the Portfolio on October 23 at $107.16 and reset our checkpoint to $95. On October 27, Paccar reported Q3 2026 revenue up 19% to $7.94 billion and net income up 44% to $847.5 million, with gross margins of 14.5%, record Paccar Parts revenue of $1.78 billion and a 9.4% increase in Paccar Financial Services pre-tax income. In between those figures we saw not only higher sequential and year-over-year operating margins for the company’s Truck & Parts business, but incremental margins north of 20%. This tells us that as Paccar’s production levels rise, the company is benefiting from economies of scale, improving price realization and other production synergies. Truck deliveries for the quarter rose to 40,100, and Paccar guided fourth-quarter deliveries to 41,000-43,000 with gross margins of 14%-15%. Management expects the U.S. and Canadian Class 8 market to grow to 240,000-280,000 trucks in 2027 from 240,000-260,000 this year, citing economic growth, infrastructure investment, a recovering freight market and fleets that have been buying below replacement levels. However, until the nonconformance penalties (NCPs) tied to the 2027 emissions rules are finalized, which management hopes will happen in four to eight weeks, some customers are holding back on 2027 orders. That diminished near-term visibility weighed on PCAR shares near the end of October. We see NCP clarification and the October and November preliminary Class 8 order data as potential catalysts, and with the position near 2.5% of the Portfolio’s assets, we have room to add more PCAR shares as those data points arrive. As we’ve said before, the key with PCAR shares is that higher truck production levels give way to operating leverage and higher EPS. Meanwhile, firmer pricing in the company’s truck backlog should improve further as truck demand heats up, driving greater operating leverage and incremental margins in 2027. It should also lift the higher-margin Financial Services segment.
October Price Change: -7.19%; Yield: 1.27%
INVESTMENT THESIS: Paccar is a multinational company that reports in three operating segments: Truck (68% of sales), Parts (24%), and Financial Services (8%). Paccar’s heavy-duty and medium-duty trucks are marketed under the Kenworth, Peterbilt, and DAF nameplates. Key factors affecting the Truck segment earnings include the number of new trucks sold in the markets served and the margins realized on the sales. The Portfolio’s play with Paccar shares is the pull forward in truck demand ahead of the EPA 2027 mandate that will result in tougher 2027 NOx engines regulations and add ~$10,000 to the cost of truck. Helping soften that blow, business owners and owner-operators can utilize 100% bonus depreciation (restored by the One Big Beautiful Bill Act) or Section 179 expensing to write off the entire purchase price of a qualifying heavy commercial vehicle, including new Class 8 and Class 5-7 trucks. With data from ACT Research finding the average age of a U.S. Class 8 tractor is 6.3 years, the highest in more than a decade, the ability to fully depreciate a new truck in its first year is likely a factor helping to drive replacement demand. The pull forward in demand should drive favorable operating leverage inside Paccar, and that is what we aim to benefit from by owning the shares.
Target Price: $155; Rating: One
Checkpoint: $95
RISKS: Commercial truck demand, competition and industry pricing, inflation, and interest rate risks.
TJX Companies TJX; $140.28; 1,750 shares; 4.21%; Sector: Consumer Discretionary
UPDATE: TJX Companies ($TJX) returned 6.0% in October, as the shares extended their September stabilization and rebounded nicely from the oversold level where we added to the position in mid-September at $127.86. Company-specific news was light during the month, with Marshalls opening new stores across six states as TJX continues to march toward its long-term store count target. The bigger story was a macro backdrop that continues to favor off-price retail. As we noted early in the month, wage growth lagging inflation reaffirms our thinking on TJX, and we expect a highly promotional holiday season spread across October to December along with stronger clearance activity. Inflation data gathered during the month points to continued pressure on consumers, especially the 62%-63% reportedly living paycheck to paycheck. September CPI came in hotter than expected at 3.7% year over year, up from 3.4% in August, while the FAO Food Price Index rose more than 5% year over year and the University of Michigan’s consumer sentiment reading fell more than 13% year over year in October. Put it together, and we see cash-strapped consumers looking to stretch their spending dollars this holiday season, the backdrop that TJX is built for. Meanwhile, the pressure on discretionary budgets is showing up at full-price and specialty retailers, which should help TJX’s buyers find quality branded merchandise at attractive prices heading into the holidays. Next up is TJX’s October-quarter report, currently scheduled for November 18, where we’ll be looking for evidence that the fixes at Marmaxx are taking hold, along with comps, merchandise margin trends, inventory positioning heading into the holidays and any update on its long-term store growth plans. While the Portfolio has a relatively full plate of TJX shares, we will continue to identify compelling risk-to-reward levels for members who are underweight TJX shares relative to the Portfolio’s position size.
October Price Change: 6.02%; Yield: 1.45%
INVESTMENT THESIS: The TJX Companies is the leading off-price apparel and home fashions retailer in the United States and worldwide. It has over 5,200 stores and six branded e-commerce sites that offer a rapidly changing assortment of quality, fashionable, brand-name, and designer merchandise at prices generally 20% to 60% below full-price retailers’ regular prices on comparable merchandise. The company operates in four segments: Marmaxx and HomeGoods, both in the U.S.; TJX Canada, and TJX International. TJX looks to capitalize on opportunities to acquire merchandise at substantial discounts that regularly arise from the production and flow of inventory in the apparel and home fashions marketplace. These opportunities include, among others, closeouts from brands, manufacturers, and other retailers; special production direct from brands and factories; order cancellations; and manufacturer overruns. We see that positioning TJX extremely well, as consumers feel the pinch of ongoing inflation pressures and their efforts to stretch the disposable spending dollars they do have, including tapping discounted shopping locations. When TJX reported its January 2026 quarter, management shared plans to grow the company’s footprint. During the May 2026 earnings call, management signaled they are actively evaluating raising their long-term store count target beyond 7,000, pointing to adjacent markets and new ventures. Exiting the July 2026 quarter, TJX’s total store count stood at 5,285 locations.
Target Price: $185; Rating: One
Checkpoint: $110
RISKS: Operational, strategic buying programs, and competitive risks, as well as consumer spending patterns.
Welltower Inc. WELL; $234.60; 790 shares; 3.18%; Sector: Real Estate
UPDATE: Shares of Welltower ($WELL) returned just under 2% in October, closing the month at $234.60. For much of the month, the shares were influenced more by moves in Treasury yields than company-specific news, with the 10-year Treasury yield climbing to its highest level since 2002 early in the month before easing back below 5.1% by mid-month. Industry data continued to support our thesis, with senior housing demand rising while new construction remains limited. On October 27, Welltower reported Q3 2026 normalized FFO of $1.67 per share, up 24.6% year over year and ahead of the $1.64 consensus, and raised its 2026 normalized FFO guidance to $6.47-$6.53 per share from $6.36-$6.44, vs. the $6.41 consensus. Same-store net operating income rose 15.8% across the portfolio and 21% in its Seniors Housing Operating segment, its 16th straight quarter above 20%, driven by a 320-basis-point occupancy gain and 5.3% growth in revenue per occupied room (RevPOR), while expenses per occupied room rose just 80 basis points. That lifted the segment’s margin 310 basis points to 31.7%. On the earnings call, management said the growth driver is shifting from filling units to raising rates, with communities above 90% occupancy posting RevPOR growth north of 6% in the strongest pricing environment it has seen in roughly 11 years. That bodes well for further margin leverage in coming quarters and rising FFO per share levels. Year-to-date investment activity totals $21 billion across 196 transactions, of which $13.3 billion had closed by the end of September, and management expects rising senior housing debt maturities in 2027 and 2028 to produce more sellers as higher borrowing costs bite. Even so, WELL shares moved lower after the report, which we attributed to net income attributable to common stockholders of $0.54 per share missing the $0.62 consensus, even though FFO is the better metric for a REIT. We used that weakness to add to the Portfolio’s WELL position at $227.73. We also lifted our price target to $270 from $265 and upgraded the shares to a One rating from Two, while keeping our $190 checkpoint for now. The company also declared its quarterly dividend of $0.85 per share, payable November 19 to shareholders of record on November 10. Going forward, the barometer we’re watching is RevPOR growth in Welltower’s 90%-plus occupied communities, as that’s where the handoff from occupancy to pricing will show up first. We intend to lift our checkpoint as the shares move higher.
October Price Change: 1.89%; Yield: 1.48%
INVESTMENT THESIS: Welltower, a real estate investment trust (REIT), owns interests in properties concentrated in major, high-growth markets in the United States, Canada, and the United Kingdom, consisting of senior housing, post-acute communities, and outpatient medical properties. We see the company benefiting from the intersection of the demographic shift that is the aging population and the looming pain point that is the shortage of inventory for senior housing, which fell below 1% in Q2 2025, according to the National Investment Center for Seniors Housing & Care. Over the next five years, more than 4 million boomers will hit age 80, and that’s in addition to the roughly 4% of the U.S. population that was 80-plus years old in 2024. As this demographic shift unfolds, we should see a relatively steady growth rate in Welltower’s revenue, NOI, and FFO, which, in turn, given its REIT status, should drive its payable dividend stream higher. Because of the favorable demographic tailwind and lower interest rate path telegraphed by the Federal Reserve, which should reduce construction costs over time, as well as bring REIT stocks back into favor, we intend to be long-term holders of WELL shares. Our plan is to build the position size methodically, increasing the Portfolio’s dividend stream along the way.
Target Price: $270; Rating: One
Checkpoint: $190
RISKS: Operational risk, operator and tenant risk, competitive risks, and acquisition risk.
TWOS
Alphabet GOOGL; $279.84; 600 shares; 2.88%; Sector: Communication Services
UPDATE: Shares of Alphabet ($GOOGL)) put in a nice showing during the first half of October but then trended lower with the Nasdaq Composite. Leading into the company’s Q3 2026 earnings report on October 28, the shares were in the red for the month, and the market’s reaction to what it heard that night pushed the shares down even further, with GOOGL falling almost 13% to $282.32 the day after the report and shedding roughly $560 billion of market value in a single session. That leaves the shares more than 30% below their May high of $404.47. In full, GOOGL shares fell more than 18% in October, placing them back near their February lows. Heading into the report, the market’s focus on the funding needs of the AI buildout weighed on the stock, overshadowing positives such as Waymo’s $5 billion loan to double its fleet by year-end and Anthropic’s S-1, which detailed a commitment of about $114.5 billion to Google for computing power through mid-2033. For its Q3 2026, Google’s revenue, advertising revenue and Search all missed expectations, and free cash flow came in at negative $9.1 billion, a second straight negative quarter, vs. expectations for something closer to breakeven. Even excluding the $5.2 billion European Commission fine payment, free cash flow would have been roughly negative $3.9 billion. Capex rose to $51.4 billion, and while the 2026 forecast of $195 billion-$205 billion was unchanged, management expects capex to rise “significantly” in 2027 without putting a number on it. But those misses overshadow a 30% increase in operating income and continued margin improvement. Google Cloud revenue roughly doubled to $30.7 billion while its operating income tripled to $11.1 billion, the Cloud backlog grew to $561 billion, and nearly 100 customers now use Google TPUs, with demand “strong and accelerating.” The part of the miss that matters most to us is advertising. Search ad spending grew 12%, down from 17% in the June quarter, and YouTube grew 9%, down from 13%, and that has the market asking whether AI is eating into Search. Analyst opinion is split, with Melius calling the quarter evidence of secular decline, while Citi, KeyBanc and Deutsche Bank see AI Mode monetization as just beginning and the headwinds as transitory. We lean toward the latter camp, since Deutsche Bank points to AI driving the strongest Search query growth in five years, but we’ll need to see ad growth stabilize to be sure. Still, with funding questions likely to be an overhang much like they have been for other hyperscalers, we trimmed our price target to $380 from $410 and kept our Two rating. To us, Google’s Cloud profit stream, its opportunity to bring ads to Google AI Mode and the $42.3 billion in operating cash flow it generated in the quarter mean it will return to free cash flow in a big way as capex eventually peaks and then falls. We’d prefer Google monetize part of its SpaceX or Anthropic stakes to help fund the buildout, but with the Meta and Microsoft offerings subscribed multiple times over, we would not be surprised to see Google follow their lead to address those funding concerns. Valuation is another reason we’re not rushing for the exits. At roughly 18 times forward earnings, GOOGL trades at a discount to the S&P 500’s 19 times and at less than half of Apple’s 36 times, the widest gap between the two in five years. A return to the 25% discount to Apple that has been normal in recent years would put the shares near $400. The question to ask is if GOOGL shares will be higher 12 months from now? In our view the answer to that is yes, but in the near term that means letting the shares absorb some pain and waiting for a buying opportunity. As we enter November, the shares are oversold on the daily chart, and a look at the weekly chart shows support near $265, the 100-day moving average. We’ll keep an eye on that as well as watch for a turn in the MACD indicator, while we wait for Google to address market concerns over its planned step up in 2027 capex and how it will fund that spending.
October Price Change: -18.67%; Yield: 0.26%
INVESTMENT THESIS: We believe that while search and digital ad dominance are what will carry the shares in the near-to mid-term, longer-term, it is the company’s artificial intelligence “moat” that will provide for new avenues of growth. Alphabet surpassed more than 350 million paid subscriptions across Google One and YouTube. AI is what has made the company’s search, video, and targeted ad capabilities best-in-class and is the driving force behind the company’s success in voice (Google Home) and autonomous driving (Waymo). Furthermore, we believe it is this AI expertise that will also make the company more prevalent in other industries, including healthcare via its subsidiary Verily, as AI and machine learning continue to disrupt operations across industries. As of mid-2026, Google’s Gemini app had over 1 billion million monthly active users. Adding to our positive view of the company’s future opportunities, we believe that Alphabet’s free cash flow generation and solid balance sheet set it apart and are what will allow the company to continue taking chances on far-out, ground-breaking, and potentially world-changing projects, as well as fund capital returns to shareholders. We will continue to monitor advertising spend as well as the competitive landscape for the company’s core Search and Advertising business.
Target Price: $380; Rating: Two
Checkpoint: $305
RISKS: Regulatory risk (data privacy), competition, and macroeconomic slowdown impacting consumers and therefore ad buyer activity.
Amazon AMZN; $240.35; 801 shares; 3.30%; Sector: Consumer Discretionary
UPDATE: When all was said and done, shares of Amazon ($AMZN) fell low-single digits in October as the market’s reaction to its Q3 2026 results on October 29 followed the same path taken by Meta and Alphabet. Heading into the report, Anthropic’s filings showed roughly $110 billion in commitments to AWS, and CEO Andy Jassy said AWS capacity for 2027 is largely sold out. The quarter confirmed that demand. AWS revenue rose 39.3% to $46.0 billion, ahead of the 38.2% Wall Street expected, its sixth straight quarter of accelerating growth, while its backlog grew triple digits to $578 billion and its operating margin climbed to 38.7% from 34.6% a year ago. Jassy now expects AWS to grow north of 40% in both 2027 and 2028, and inference already accounts for well over half of AWS AI revenue. The rest of the report was a hair light. Revenue rose 12% to $201.9 billion vs. the $202.2 billion consensus, and EPS of $1.89 missed the $1.97 forecast as retail and advertising revenue came in below expectations. But management estimates the shift of Prime Day into June shaved roughly 400 basis points off September-quarter growth, combined June- and September-quarter North American sales were up double digits, and North American margins continued to expand. With NBA games back on Prime Video, Amazon expects ad growth to return to the high teens in the December quarter, which we’ll be watching to confirm the September quarter was a timing issue. What weighed on AMZN shares was capex and free cash flow. Capex of $77.3 billion ran about $20 billion above estimates, and simple math tells us that consumed roughly 1.8x the $42.4 billion in operating cash flow Amazon generated, leaving free cash flow negative for a third straight quarter. Amazon held its 2026 capex forecast near $220 billion and expects to spend “meaningfully more” in 2027. Entering November, consensus operating cash flow figures for 2027 and 2028 are north of $200 billion each. December-quarter guidance for revenue of $240 billion-$247 billion and operating income of $28.5 billion-$33.5 billion came in below consensus at the midpoint, but Amazon has a history of guiding conservatively for its all-important holiday quarter. To us, funding the buildout is the near-term overhang, and it appears Amazon has started to address it. Its 10-Q disclosed supplier financing arrangements that let it borrow as much as $80 billion against the hardware it buys, a secured facility it can tap at its discretion from the start of 2027 through the third quarter of 2028, with lenders getting collateral rights over some of the assets purchased. Until now, Amazon had funded its data centers and chips with cash from its cloud and retail operations and its biggest-ever bond sales, and had largely avoided the creative arrangements some rivals have used, such as joint ventures with investment groups or leasing chips. AWS CEO Matt Garman said Amazon is looking for ways to “responsibly fund” the opportunity so it can “go as big as possible” for customers. We see that as a sign management is serious about keeping the buildout going, but it also underscores the scale of the commitments. Amazon’s total spending commitments, including debt, interest, leases not yet commenced and obligations to acquire property and equipment, ballooned to $883 billion at the end of September, up 36% from the prior quarter and more than double a year ago. In our view, Amazon tapping that supplier financing arrangement should allow it to build out its needed capacity, grow its AWS revenue, profit and cash flow in the coming quarters and in due course return to positive free cash flow. With the midterm elections and October inflation data around the corner, we’d rather make a higher conviction move once we have more data in hand, and we’ll be watching support near $240 on the weekly chart to determine potential pick-up points.
October Price Change: -3.53%; Yield: N/A
INVESTMENT THESIS: We believe that upside will result from Amazon’s continued e-commerce dominance, AWS’s continued leadership in the public cloud space, and the ongoing growth of the company’s advertising revenue stream, which feeds off Amazon’s e-commerce business. Additionally, we think profitability will continue to improve as AWS and advertising account for a larger portion of total sales, as both these segments sport higher margins than the eCommerce operation. While we believe the increasing share of the revenue from these higher-margin businesses will be key to driving profitability longer-term, we think margins on eCommerce stand to improve as the company’s infrastructure is further built out and economies of scale further kick in. The embedded call option is that management is always looking to enter a new space and generate new revenue streams. Outside of the company’s core businesses, per recent 13F-HR filings, Amazon holds a stake of 158.36 million shares in Rivian, 225,428 shares in Marvell, as well as positions in other companies. It has also committed to a $50 billion investment in OpenAI.
Target Price: Reiterate $325; Rating: Two
Checkpoint: $225
RISKS: High valuation exposes the stock to volatile swings, e-commerce has exposure to slower consumer spending and competition, potential headwinds resulting from new e-commerce regulation in India, and management is not scared to invest aggressively for growth, which can at times cause volatile reactions as near-term concerns arise relating to the impact on margins.
Apple AAPL; $344.63; 750 shares; 4.43%; Sector: Technology
UPDATE: Shares of Apple ($AAPL) climbed low-to-mid-single digits in October, and along the way set a fresh intraday all-time high of $351.73 on October 23, the day the iPhone Duo hit store shelves. The month got off to a choppy start when Nikkei Asia reported Apple had told suppliers to cut October component orders for the iPhone 18 Pro and Pro Max by at least 15%, citing soaring memory costs and softer demand. As we shared that morning, we weren’t surprised given the growing buzz around the Duo, and what matters more is the aggregate mix of iPhone orders. That mix story got a big boost on October 16 when Duo pre-orders opened and promptly sold out, with delivery dates slipping to late January within hours and Apple calling demand “nothing short of extraordinary.” With the Duo starting at $1,999 vs. $1,199 for the entry iPhone 18 Pro, and Apple likely to shift production toward it, we lifted our AAPL price target to $375 from $350 and our checkpoint to $305 from $280. Simple math tells us that a richer mix at those price points should lift iPhone average selling prices and revenue even if total units are flat. Supporting that view, DigiTimes reported on October 22 that strong pre-orders led Apple to raise its 12-month Duo shipment target by 44% to 14 million units from 9.7 million. Earlier in the month, Apple’s October 13 “Welcome Home” event put Siri AI at the center of the smart home with HomeView, HomePod mini 2, a new Apple TV 4K and the Apple Home Collection developed with LG and Schneider Electric. None will move the revenue needle like iPhone, but they keep customers inside the Apple tent. Reports also pointed to Apple Intelligence finally launching in mainland China in December, and Apple and Meta announced a collaboration to run Meta’s Muse Spark model locally on Mac Studio. On the flip side, IDC found September-quarter smartphone shipments fell 22% as memory costs surged roughly 350%, though Apple fared better than most given its premium lineup, and KeyBanc downgraded Apple supplier Cirrus Logic, citing supplier cuts that point to lower iPhone units in 2027. Looking ahead, Apple will report its September-quarter results on November 2. There, our focus will be December-quarter guidance and the Duo’s contribution as well as what management says about memory costs and margins. We will also be interested in the company’s Services segment, which should benefit from pricing action taken earlier in the year and Apple’s expanding user base. Subject to what we learn, including from Taiwan Semi’s October sales report and Foxconn quarterly earnings report on November12, we’ll revisit our $375 price target as needed. As we move through the seasonally strongest time of year for AAPL shares, a pullback near $331 would be a place to consider picking up some shares, but a more pronounced move near $320 offers a more compelling spot to add.
October Price Change: 3.49%; Yield: 0.32%
INVESTMENT THESIS: While we acknowledge that near-to-mid-term performance remains heavily influenced by iPhone sales, the dynamic is shifting as investors finally place greater emphasis on Services growth. We are bullish on the 5G upgrade cycle and believe longer-term upside will continue to come as Services revenue grows its share of overall sales. Services provide for a recurring revenue stream at higher margins, a factor that serves to reduce earnings volatility while allowing for a higher percentage of sales to fall to the bottom line; as a result, we believe that Services growth and the installed base are much more important than how many devices the company can sell in each 90-day period. In addition to improved profitability, we also believe the transparent nature of this revenue stream will demand an expanded price-to-earnings multiple as segment sales grow. Furthermore, we believe that Apple’s desire to push deeper into the healthcare arena will help make its devices invaluable as more life-changing features are added and the company works to democratize health records.
Target Price: $375; Rating: Two
Checkpoint: $305
RISKS: Slowdown in consumer spending, competition, lack of new product innovation, elongated replacement cycles, and failure to execute on Services growth initiatives.
Arista Networks ANET; $168.86; 1,200 shares; 3.47%; Sector: Technology
UPDATE: Shares of Arista Networks ($ANET) fell 17.1% in October, closing the month at $168.86, as a record-setting start to the month gave way to a sharp pullback as AI spending concerns took hold late in the month. The shares reached record levels after Bernstein initiated coverage with an Outperform rating and a $250 price target on October 1, and Lumentum later said its optical components are effectively sold out through early 2029, a strong data point for AI networking demand. Mid-month, Bloomberg reported Microsoft, one of Arista’s two largest customers, plans to more than triple its data center capacity to more than 38 gigawatts by 2032. Despite those favorable data points, ANET shares fell sharply in the back half of the month as the market’s AI financing concerns intensified following Meta’s quarterly results. Meta’s 10-Q revealed sizable multi-year commitments to support capacity for more than 1 billion Muse users, and Nokia said demand for networks exceeds supply, with AI and cloud its fastest-growing customer group. That led us to add to the Portfolio’s ANET position near $173 on October 23 while keeping our checkpoint at $145. We purposely left room to add further given Nokia also flagged supply chain pressures that could resurrect the component constraints Arista contended with earlier this year. The month closed with more supportive capex news. Microsoft expects capex to top $50 billion in the December quarter and accelerate again in the first half of 2027, while Meta and Alphabet are both stepping up their 2027 spending. That bodes well for Arista, though as we’ve discussed, capacity constraints could make for fits and starts in its deliveries. To us, those spending plans point to sustained demand for Arista’s AI networking switches well into 2027, and as component constraints ease, rising volumes should give way to operating leverage. Next up is Arista’s Q3 2026 report after the market close on November 3, where backlog, deferred revenue, component shortages and 2027 visibility will be focal points. As we digest that report, we’ll revisit our $225 price target, and should the shares remain under pressure, we’re inclined to use that weakness to round out the position.
October Price Change: -17.06%; Yield: N/A
INVESTMENT THESIS: Arista Networks engages in the development, marketing, and sale of data-driven, client-to-cloud networking solutions for AI, data center, campus, and routing environments in the Americas, Europe, the Middle East, Africa, and the Asia-Pacific. Its cloud networking solutions consist of Extensible Operating System (EOS), a publish-subscribe state-sharing networking operating system offered in combination with a set of network applications. The company offers data center, cloud, and AI networking, cognitive adjacencies, and cognitive network software and services. It also provides post-contract customer support services, such as technical support, hardware repair, and replacement parts beyond standard warranty, bug fixes, patches, and upgrade services. The company serves a range of industries comprising internet companies, cloud service providers, financial services organizations, government agencies, media and entertainment, healthcare, oil and gas, education, manufacturing, industrial, and others. Two of Arista’s largest customers in the last few years are two Portfolio holdings you’ll quickly recognize — Microsoft and Meta. Per Arista’s 10-K filings, both Meta and Microsoft each account for more than 10% of revenue. Other named customers include Amazon’s AWS, Google Cloud, Anthropic, Canva, SAP, Shopify, Apple, Oracle, Bank of America, and Accenture.
Target Price: $225; Rating: Two
Checkpoint: $145
RISKS: Economic, customer, supply chain, and competition risks.
Bank of America Corp. BAC; $50.01; 3,999 shares; 3.43%; Sector: Financial Services
UPDATE: Shares of Bank of America ($BAC) tumbled mid-single digits in October as a sizable regulatory fine, mixed quarterly report, and slower IPO activity dragged the shares lower. On October 13, the Treasury Department’s FinCEN assessed a $1.2 billion penalty against Bank of America for Bank Secrecy Act violations tied to failures in its anti-money laundering program, with the OCC’s $750 million penalty credited against that amount. When BofA reported its Q3 2026 results the next day, EPS of $0.91 included that charge, and excluding it, EPS of roughly $1.08 missed consensus modestly. Net interest income rose 8% to $16.4 billion, and client deposits, wealth flows and consumer activity were bright spots. However, investment banking fees fell 11% to $1.8 billion, and sales and trading revenue dropped 5%, with fixed income trading notably weaker. BAC shares declined sharply on the news, pushing their Relative Strength Index below 20. We expect some near-term credibility questions following the fine, but as we said at the time, investors shouldn’t expect us to pull the plug on BAC shares. Baird upgraded the shares to Outperform with a $62 target, arguing the selloff was excessive, while roughly 10 other firms trimmed their targets. CEO Brian Moynihan has pointed to net interest income growth of 8% or more in 2027. A rising rate environment, with the market outlook calling for a December Fed rate hike and two more in the first half of 2027, should support BofA’s net interest income but could slow loan growth. The key question remains an investment banking rebound. Here, the month closed with encouraging developments, including EQT Corp.’s $50 billion all-stock deal for Range Resources, Anthropic’s public S-1 filing, Meta’s equity offering and the $63 billion financing package that Bank of America is helping provide for Anthropic’s purchases of Broadcom chips and networking gear. Should that activity translate into a rebound in fees, alongside net interest income growth and BofA’s focus on productivity and cost reduction, it would set the stage for improving operating leverage and EPS in 2027. Between BofA and Morgan Stanley, we said Morgan Stanley would likely be our first add, which proved to be the case in late October. Exiting the month, Microsoft’s heavily oversubscribed $25 billion bond sale, following Meta’s raise, points to an appetite for more of these offerings, a positive for investment banking fees. With BAC shares building a base amid an oversold condition, we’re contemplating adding to the Portfolio’s BAC position.
October Price Change:-8.12%; Yield: 2.35%
INVESTMENT THESIS: Bank of America is one of the world’s leading financial institutions, serving individual consumers, small- and middle-market businesses, and large corporations with a full range of banking, investing, asset management, and other financial and risk management products and services. The company provides unmatched convenience in the United States, serving approximately 69 million consumers and small business clients with approximately 3,700 retail financial centers, approximately 15,000 ATMs, and award-winning digital banking with approximately 59 million verified digital users. Bank of America is a global leader in wealth management, corporate and investment banking, and trading across a broad range of asset classes, serving corporations, governments, institutions, and individuals around the world. Bank of America offers industry-leading support to approximately 3 million small business households through a suite of innovative, easy-to-use online products and services. The company serves clients through operations across the United States, its territories, and approximately 35 countries. From a reporting perspective, the company’s business breaks down as follows: Net Interest Income breakdown: Consumer Banking 57%, Global Banking 23%, Global Wealth & Investment Management 14%, and Global Markets 6%; Income Before Tax breakdown: Consumer Banking 42%, Global Banking 27%, Global Wealth & Investment Management 16%, and Global Markets 15%.
Target Price: $70; Rating: Two
Checkpoint: $45
RISKS: Financial markets, fiscal, monetary, and regulatory policies, economic conditions, and credit ratings.
Eaton Corp. ETN; $369.97; 532 shares; 3.37%; Sector: Industrials
UPDATE: Despite a strong finish at the end of the month, shares of Eaton ($ETN) fell double-digits in October, pulled lower amid the AI-related selloff earlier in the month. That move came even though data on electricity demand continued to build in Eaton’s favor. Early in the month, Applied Digital said power is the “single largest gating factor” in its industry as it plans to have 3.5 to 4 gigawatts of capacity in place by 2030. Mid-month, Bloomberg reported Microsoft plans to more than triple its data center capacity to more than 38 gigawatts by 2032, more than New York State’s peak electricity use. As one data point put it, an AI rack draws 100 kilowatts compared to 1.2 kilowatts for a house, and the grid takes a decade to build. Microsoft also walked away from an Nscale data center site in Essex because power was unlikely to be available before 2030, another reminder that power remains the pain point Eaton is positioned to address. With the shares retreating, we added to our holdings near $395 on October 19 and kept our checkpoint at $370. The shares then fell sharply on October 22 alongside Vertiv and GE Vernova, as Meta’s higher spending outlook and negative free cash flow stoked concerns over how the AI buildout will be funded. During the final week of October, which brought funding deals for SpaceX, Meta and others, ETN shares rallied back as AI concerns waned. On the aerospace side, GE Aerospace’s comments about rising engine deliveries to Boeing bode well for Eaton’s Aerospace segment, roughly 15% of its revenue. Next up is Eaton’s Q3 2026 results before the market open on November 3. There, we’ll be focused on data center orders, which were up 85% year over year per UBS’s September analysis, and electrical backlog levels. We’ll continue listening for updated capital spending comments from hyperscalers, neoclouds and electric utilities.
October Price Change: -13.90%; Yield: 1.02%
INVESTMENT THESIS: Eaton is an intelligent power management company that makes products for data center, utilities, industrial, commercial, machine building, residential, aerospace, and mobility markets. That business is positioned to capitalize on the mega trends of electrification, energy transition, and digitalization. We see Eaton helping address the power pain point created by data center, EV charging infrastructure, and other drivers of electricity demand. Research estimates that data center power demand will grow 160% by 2030, accounting for 3% to 4% of global power, up from 1% to 2% today. Data centers will use 8% of U.S. power by 2030, compared with 3% in 2022.
Target Price: Reiterate $500; Rating: Two
Checkpoint: $370
RISKS: Raw material costs, labor costs, end market volatility, and government legislation.
Meta Platforms META; $614.99; 297 shares; 3.13%; Sector: Communication Services
UPDATE: Shares of Meta Platforms ($META) fell double digits in October, with the bulk of that decline coming after the company’s Q3 2026 results that raised questions about potential capital needs. Early in the month, Muse adoption continued to impress. Sensor Tower data showed Muse was the 12th app ever to reach 10 million U.S. downloads in 40 days, with retention rates well ahead of ChatGPT, Claude and Grok, and Apple and Meta announced a collaboration to run Meta’s Muse Spark model locally on Mac Studio, which helps address the privacy concerns that remain the key hurdle for Muse. The defining event, however, was Meta’s October 21 report. Q3 revenue rose 26% to $64.6 billion, ahead of the $63.3 billion consensus, with Family Average Revenue per Person up more than 20% and the average price per ad up 14%. Family daily active people reached 3.64 billion, and more than 10 million U.S. and Canadian users set up Muse in six weeks. However, total expenses jumped 68% to $51.6 billion, including a $9.9 billion charge for the August settlement with state attorneys general. Meta also narrowed its 2026 capex range to $135 billion-$145 billion but offered no formal 2027 figure, though it telegraphed a big year-over-year step up in that spending, and free cash flow turned negative at -$2.1 billion. Despite the revenue beat and a raft of price target increases, the shares fell sharply following the report. Here’s the thing: Meta’s ad business is firing on all cylinders as it leverages AI to drive efficiencies and boost pricing. However, with overall expenses growing more than twice as fast as revenue, the near-term operating leverage story has flipped, and that’s what the market was adjusting to as well as subsequent reports the company would look to raise as much as $95 billion. Meta also announced a new class of nonvoting Class C shares to be distributed one-for-one to shareholders, and its 10-Q showed $454.5 billion in non-cancelable commitments. This speaks to Zuckerberg’s stated plan to build sufficient capacity to support 1 billion Muse users in the coming years. On October 26, Meta launched an equity raise that it boosted to almost $98 billion, one of the largest in history, selling $25 billion of common stock and $12.5 billion of preferred shares, with up to $60 billion more to come through an at-the-market program. Nvidia, AMD and Broadcom agreed to buy up to $5 billion of the common shares. While we see that raise helping calm funding concerns across AI infrastructure, the funding of Meta’s buildout remains the overhang for META shares, and that’s another reason to stay on the sidelines near-term. Recall we trimmed the position just below $750 in September, which served us well. With the shares near $615 entering November, we’ll be watching to see if a positive test of support on the weekly chart near $630 emerges and if we see a positive inflection in the MACD indicator on the daily chart. On the fundamental side, we’ll continue to track data for Muse and any subscription data and reported transaction volumes as Meta looks to monetize that new platform.
October Price Change:-15.19%; Yield: 0.29%
INVESTMENT THESIS: Meta segments its business between Family of App Products, which includes Facebook, Instagram, Messenger, Threads, and WhatsApp, and Reality Labs Products, which includes its metaverse and investments and future product R&D. Family of Apps accounts for about 99% of the company’s revenue and 100% of the company’s operating profits. Substantially all of Meta’s revenue is currently generated from advertising on Facebook and Instagram. Family daily active people (DAP) were ~3.64 billion on average for the September 2026 quarter. Meta forecasts its expenses to run between $165 billion-$169 billion this year while also spending $135 billion-$145 billion on capex, a significant increase year over year with a large step up in H2 2026 compared to H1 2026. Meta is positioned to benefit from the ongoing shift toward digital advertising and the adoption of AI across its entire product offering. We recognize Meta is ramping up capital spending as part of the current AI arms race, but we see that as an investment that has the potential to drive greater productivity and monetization as it expands its core advertising business further across all its platforms. As the company shifts into harvesting that investment, we could see a step up in margins, much like we saw in 2023.
Target Price: $850; Rating: Two
Checkpoint: $590
RISKS: Ability to add and retain users and user engagement; marketing spend; new products or changes to existing ones; competitive risk, geopolitical risk.
Microsoft Corp. MSFT; $521.91; 310 shares; 2.77%; Sector: Technology
UPDATE: With their low-single digit rise in October, shares of Microsoft ($MSFT) were a nice performer for the Portfolio and an outperformer relative to the S&P 500 and the Nasdaq. Mid-month, Bloomberg reported Microsoft plans to more than triple its data center capacity to more than 38 gigawatts by 2032 and that a computing shortage had forced it to turn away some AI and cloud business. Anthropic’s disclosures also included a $31 billion commitment to Microsoft, and on October 26, Microsoft offered voluntary buyouts to roughly 60,000 eligible employees. On October 28, Microsoft topped expectations on revenue, EPS and guidance for its September quarter. Azure revenue grew 48% to $33.2 billion vs. the 44% Wall Street expected, management guided for 49%-50% growth in the December quarter as demand continues to exceed supply, and the commercial backlog jumped 73% to $677 billion. What stands out to us is the operating leverage. Operating income rose 21% while operating expenses grew just 6%, lifting operating margin to 50%. The big surprise was $18.6 billion in free cash flow vs. the roughly $8.5 billion Wall Street modeled, though some of that reflects third-party capacity deliveries that slipped, holding capex to $45.2 billion vs. Microsoft’s $50 billion forecast. Following the report, we boosted our price target to $600 from $500. We’re keeping our Two rating, however, as Microsoft expects capex to top $50 billion in the December quarter, totaling about $170 billion for calendar 2026 and step up again in calendar 2027. Microsoft wasted little time addressing the funding question. On October 30, it raised $25 billion in its first major bond sale for the AI buildout, drawing roughly $115 billion in orders, 4.6 times the amount on offer. Odds are Wall Street will need to revisit its fiscal 2027 free cash flow forecast of near $30 billion when Microsoft lays out its 2027 capex plans in January, and until then, MSFT shares could be range bound. Longer term, as the AI buildout tempers and capex declines, Azure margins should lift and free cash flow reaccelerate. That’s the opportunity in the shares, but rather than chase them here, we’ll wait for a pullback that improves the risk to reward tradeoff to our new $600 price target.
October Price Change: 1.76%; Yield: 0.76%
INVESTMENT THESIS: We believe the cloud to be a secular growth trend and that the upside to the shares will result from Microsoft’s hybrid cloud leadership as the company grabs market share in this expanding industry. While companies may look to build out multi-cloud environments, Microsoft’s Azure offering will be a prime choice thanks to its decision to provide the same “stack” used in the public cloud to companies for their on-premises data centers. Additionally, we would note that hybrid environments are currently the preference for most companies because they allow them to maintain critical data in-house while taking advantage of the agility and scalability provided by public clouds. Outside of the cloud opportunity, we maintain a positive view on the company’s growing gaming business, which we believe is becoming an increasingly prominent factor in the Microsoft growth story as gaming becomes more mainstream, management works to convert its gaming revenue from a one-time license purchase to a recurring subscription model, and as technologies like augmented/virtual reality evolve. Finally, as it relates to LinkedIn and other subscription-based services such as O365 and various Dynamics products, we continue to value them highly for their recurring revenue streams, which, we remind members, provide for greater transparency of future earnings.
Target Price: $600; Rating: Two
Checkpoint: $345
RISKS: Slowdown in IT spending, competition, and cannibalization of on-premises business by the cloud.
Morgan Stanley MS; $184.30; 1,220 shares; 3.85%; Sector: Financial Services
UPDATE: Shares of Morgan Stanley ($MS) slipped just over 2% in October, but combined with their double-digit decline in September, they closed October up modestly year-to-date. Worries about the IPO market overshadowed a strong quarterly report. Early in the month, a string of M&A deals, including Schneider Electric’s purchase of PTC, Nvidia’s acquisition of Hugging Face and the NextEra-Dominion merger, reminded us that investment banking fees come from more than just IPOs. Still, the pulled $5 billion Firmus Grid IPO suggested the IPO window remained shut for now, weighing on MS shares. On October 14, Morgan Stanley beat Q3 2026 consensus, with revenue up 12% to $20.3 billion and EPS of $3.03 vs. roughly $2.94 expected. Equity trading revenue jumped 41% to $5.8 billion, Wealth Management delivered record revenue of $9.1 billion with a 30.4% margin, and net new assets hit a record $232 billion. Despite the beat, MS shares slipped following the report as the market continued to fixate on the outlook for IPO activity. Mid-month, New York City Comptroller Mark Levine urged Anthropic to delay its IPO, and valuation chatter for the offering slipped to around $1.5 trillion from $2 trillion. However, the month closed with a flurry of activity. EQT Corp. agreed to acquire Range Resources in a $50 billion all-stock deal, and Anthropic publicly filed its S-1 on October 26, with Goldman Sachs as lead-left and Morgan Stanley as the second lead bookrunner. That same day, Meta launched an equity raise, later boosted to almost $98 billion, with Morgan Stanley and Goldman Sachs leading the offerings, and on October 27 Morgan Stanley was among the banks providing $63 billion in financing for Anthropic’s purchases of Broadcom chips and networking gear. Add in fund-raising efforts by SpaceX and OpenAI, and we see concerns over investment banking fees as likely overdone. That led us to add to the Portfolio’s MS position near $184.50 on October 26 and reset our checkpoint to $165. Microsoft’s $25 billion bond sale on October 30, which was 4.6 times oversubscribed, along with prospective offerings from Alphabet and Amazon, only reinforces that decision. As we discussed in our Office Hours the same day, we trimmed MS shares near $215 back in mid-June, and the recent pullback offered an opportunity to rebuild the position at a lower level. Next up is the Anthropic IPO roadshow, slated to begin around November 9 with pricing expected before Thanksgiving, as well as the progress of Meta’s offering. As we await those transactions, and what Anthropic’s IPO may portend for the IPO market, we’ll be monitoring developments on the M&A front as well. Should we see the IPO market rebound and the pace of other investment banking activity continue at a brisk pace, that would lead us to revisit our current Two rating on MS shares.
October Price Change: -2.01%; Yield: 2.45%
INVESTMENT THESIS: Morgan Stanley reports in three business segments: Institutional Securities (42% of trailing 12-month revenue, 38% of trailing 12-month Income Before Tax), Wealth Management (48%, 55%), and Investment Management (10%, 6%). While the IPO window has yet to reopen, the potential IPO class continues to build with pending ones from Anthropic, OpenAI, and others. That would be a boon to private equity firms and others that have been nursing IPO candidates during the dark period and a positive for Morgan Stanley’s investment banking business. Deregulation under the Trump administration is a potential catalyst for Morgan’s M&A business. Meanwhile, folks continuing to be behind in retirement savings bodes well for Morgan Stanley’s wealth management business in the coming quarters, while continued market volatility bodes well for its equity trading business.
Target Price: $225; Rating: Two
Checkpoint: $165
RISKS: Market and interest rate risk, credit risk, country risk, and operational risk, including cybersecurity.
Palantir Technologies PLTR; $184.11; 1,130 shares; 3.57%; Sector: Technology
UPDATE: After soaring more than 60% in Q3 2026, shares of Palantir Technologies ($PLTR) reached a new high in mid-October before easing back with the broader pullback in AI-related stocks. For the month, PLTR shares fell 1.6%. Early in the month, Palantir announced a partnership with Armada for air-gapped sovereign AI on modular data centers, naming Armada its first Certified Modular Data Center Partner. On October 19, the shares rallied after Palantir announced a partnership with Knox Systems aimed at federal cloud and FedRAMP software deployments. Other data points during the month pointed to widening enterprise AI adoption. At SAP, 9 of its 50 largest deals included AI and it targets up to €3 billion in AI efficiencies, while at IBM, AI accounted for about 30% of consulting revenue and 35% of its consulting backlog. As AI adoption and usage widen further, we continue to see Palantir benefiting across both its commercial and government businesses. The company will report its quarterly results after the market close on Monday, November 2. Its guidance calls for Q3 revenue of $2.160 billion-$2.164 billion, up more than 80% year over year, versus the $2.18 billion consensus forecast. For the current quarter, the market expectation is for revenue to rise to ~$2.45 billion. Given the continued step-up in AI adoption, there is reason to think Palantir’s second-half outlook skews conservative, but expectations are elevated following a long string of beats. Inside Palantir’s Q3 2026 results, we’ll be focused on U.S. commercial revenue growth, remaining deal value, total contract value, customer count and revenue per customer, as well as margins and free cash flow, which should add further to the company’s roughly $9.4 billion in net cash. As a frame of reference, exiting Q2 2026, the company’s U.S. commercial remaining deal value (RDV) was $6.24 billion with a corresponding customer count of 653. Its total RDV exiting that quarter was $13.1 billion. We’ll also be listening for updates on government demand both here in the U.S. and internationally. Given the market mood when it comes to companies in the AI complex, should Palantir come up short either with its quarterly results or guidance, we’ll follow up with potential pick-up points.
October Price Change: -1.57%; Yield: N/A
INVESTMENT THESIS: Palantir Technologies specializes in big data analytics and builds software platforms that help organizations integrate, analyze, and make sense of vast amounts of data for both commercial and government clients. While much has been made about the company’s exposure to the federal government, its software is used across 90 industries, and the larger global government sector accounted for 55% of revenue last year. The balance was from the commercial sector. Exiting Q2 2026, Palantir’s U.S. Commercial remaining deal value (RDV) stood at $6.24 billion, up 124% year over year, and its total RDV at $13.1 billion. We will continue to monitor Palantir’s RDV and deferred revenue metrics. Key items to watch include continued diversification of its customer base across industries and increasing revenue per customer. Because we are still in the relatively early innings of AI adoption, we are inclined to be long-term owners of PLTR shares.
Target Price: $220; Rating: Two
Checkpoint: $120
RISKS: Economic and IT budget spending risk, technology risk, competition and competitive pressures, and customer acquisition risk.
Robo Global Robotics and Automation ETF ROBO; $74.62; 1,390 shares; 1.78%; Sector: Technology
UPDATE: While shares of the Robo Global Robotics and Automation ETF ($ROBO) had a strong finish during the last week of October, it wasn’t enough to overcome declines registered earlier in the month. The net result was a 7.3% decline, but we used that pullback to wade deeper into the shares given the favorable data points and other signals received during the month. On October 27, we bought 425 ROBO shares at $76.11 and maintained our $68 checkpoint. We made that move alongside our additions to AVGO and MRVL shares, using the AI infrastructure funding announcements for SpaceX, Anthropic-Broadcom and Meta as a sign that funding concerns weighing on the group should ease. As we explained at the time, the move lower in ROBO likely reflected just under half of its end-market exposure coming from computing and AI, actuation, sensing and integration, the same exposure that ties the ETF to the AI infrastructure buildout. That same morning, ETF holding Celestica reported 83% revenue growth and record margins and issued an initial 2027 revenue outlook of $40 billion, up 90%. We continue to monitor other key holdings in the ETF’s basket, including Intuitive Surgical, Harmonic Drive, Illumina, Fanuc, Teradyne and Rockwell Automation. Industry data continues to support our thesis. The latest A3 data showed North American robot orders up 4.3% in units and 21.3% in value in Q2, with non-automotive customers accounting for 56% of units. Texas Instruments’ comments about robotics and automation demand bode well for the ETF’s constituents. Tesla said it has started early production on its high-volume Optimus line in Fremont, though reaching 20,000 units a week will take at least a year. Rising labor costs and accelerated depreciation under the One Big Beautiful Bill should only strengthen the case for automation as companies focus on productivity. Upcoming catalysts include A3’s Q3 2026 robot order data, likely in mid-November. Having added to the position, we will continue to evaluate potential levels to further expand the Portfolio’s position size.
October Price Change: -7.26%; Yield: N/A
INVESTMENT THESIS: The ROBO Global Robotics & Automation Index ETF invests in global companies that are driving transformative innovations in robotics, automation, and artificial intelligence (RAAI), including companies that create technology to enable truly intelligent systems that can sense, process, and act, and companies that apply those technologies to deliver RAAI-enabled products — including robots — to businesses and consumers. The ETF’s underlying basket is broken down into two categories — Application (55%) and Technologies (45%). Application includes manufacturers and industrial automation (21%), logistics automation (10%), autonomous systems (7%), healthcare (7%), food & agriculture (6%), business process automation (3%), and 3D printing (1%). Technologies includes actuation (14%), computing and AI (14%), sensing (10%), and integration (7%).
Target Price: Reiterate $95; Rating: Two
Checkpoint: $68
RISKS: Economic and business cycle risk; capital spending and geographic risk, technology risk.
State Street Health Care Select Sector SPDR ETF XLV; $184.84; 580 shares; 1.84%; Sector: Health Care
UPDATE: After dipping modestly in September, the State Street Health Care Select Sector SPDR ETF ($XLV) rebounded hard in October climbing nearly 10% as health care stocks benefited from a rotation away from AI and technology shares. By October 20, the ETF had meaningfully outperformed a flat S&P 500 over the prior month, helped by easing tariff and drug pricing concerns and continued sector M&A. Quarterly results from several top holdings set the tone. On October 13, Johnson & Johnson ($JNJ) beat expectations and raised its full-year outlook, with pharmaceutical sales up 7.7%. However, its MedTech sales rose only 2.5% and missed expectations, and we’ll be watching to see if that reflects share loss, deferred procedures or belt-tightening on equipment. UnitedHealth also beat expectations and guided 2026 adjusted EPS to at least $20.50, while noting at least 69% of its members will be in 4-star or higher Medicare Advantage plans for 2027. Later in the month, Abbott Labs ($ABT) reaffirmed the midpoint of its full-year EPS guidance. On the Medicare front, reports pointed to enrollment in Medicare Advantage poised to rise as premiums fall, which speaks to our aging-of-the-population theme. Following the string of XLV constituents having recently reported September quarter results, we are in the process of fine tuning our price target for the ETF with an upward bias. However, with a RSI reading of 72.6 exiting October, we’re inclined to wait for a pullback in the shares before adding further. Upcoming catalysts include quarterly results and guidance from Pfizer ($PFE) and other constituents in the ETF basket.
October Price Change: 9.75%; Yield: 1.50%
INVESTMENT THESIS: The State Street Health Care Select Sector SPDR ETF provides exposure to companies in the pharmaceuticals; health care equipment and supplies; healthcare providers and services; biotechnology; life sciences tools and services; and healthcare technology industries. Top holdings exiting September 2026 included Eli Lilly (15.1%), Johnson & Johnson (10.4%), AbbVie (7.55%), Merck & Co. (5.86%), United Health (5.38%), and Thermo Fisher Scientific (4.08%).
Target Price: Reiterate $180; Rating: Two
Checkpoint: $147
RISKS: Drug approval, pricing pressure, funding changes, R&D spending, patent expiration, and litigation risk.
Waste Management WM; $233.45; 775 shares; 3.10%; Sector: Industrials
UPDATE: After climbing at a brisk pace through most of October, which landed Waste Management ($WM) in an overbought condition, the shares moved lower following the company’s Q3 2026 earnings miss. The net result was WM shares climbed 14.5% in October, making them the Portfolio’s best performer for the month. The shares climbed from near $202 to roughly $240 in the first few weeks of October with little in the way of company-specific news. Instead, we saw investors rotate toward defensive names as the market’s AI and technology trade came under pressure and as the energy cost backdrop came into sharper focus. As we explained, Waste passes changes in diesel and natural gas prices through its energy surcharge. With a Relative Strength Index reading above 78, flashing an extreme overbought condition, we sold roughly one-fifth of the Portfolio’s position size near $240 on October 26, ahead of Waste’s Q3 2026 earnings report. As we made that move, we also downgraded the shares to a Two rating from One and lifted our checkpoint to $210. When Waste reported its Q3 2026 results on October 27, revenue edged past expectations at $6.85 billion, but EPS of $2.05 missed consensus by $0.13. As we explained in our follow-up alert, roughly $0.12 of that shortfall came from a $63 million year-over-year jump in risk management costs, largely an out-of-period actuarial adjustment. The balance reflected fuel, given the roughly one-month lag in the energy surcharge. Operationally, revenue rose 6.3%, operating EBITDA climbed 5.8%, core price came in at 5.8%, and Healthcare Solutions posted its first year-over-year revenue gain since the acquisition. Free cash flow topped $3 billion through nine months, and Waste expects to land at the upper end of its 2026 target. However, management’s fourth-quarter diesel assumption near $5.50 a gallon looks light against current prices near $6.35, and operating EBITDA is tracking toward the low end of its range. Expecting modest EPS cuts, we trimmed our price target to $255 from $265 and maintained our Two rating. Our thesis remains that WM is a margin-driven story, helped by pricing actions, pruning of less profitable routes, the conversion of its residential fleet to automated side-loader trucks, and further integration of its Healthcare Solutions business. We’re open to rebuilding the position at more favorable prices once EPS revisions are reflected in the shares, and we’ll be watching energy prices closely, as a decline could turn that surcharge lag into a bottom-line benefit.
October Price Change: 14.48%; Yield: 1.86%
INVESTMENT THESIS: Waste Management’s revenue by reportable segment is 61% collection, 21% disposal, 10% healthcare solutions, 6% recycling, and 2% renewable energy. As you can see, the core business is the inelastic waste removal business for residential, enterprise, and other customers. The company has built its footprint through a series of acquisitions and excelled at wringing costs out of them, driving free cash flow, dividends, and funding incremental acquisition activity. While the residential business is sticky, the commercial business should continue to benefit from non-residential construction activity. Margins should continue to inch higher due to disciplined pricing and increasing use of automation. We are in the early days of WM Healthcare Solutions, but we see the business growing as management integrates and cross-sells against its core business and flexes the ability to integrate nip-and-tuck acquisitions as it has at the core waste business. Here, too, we see room to consolidate a fragmented industry, which makes this a natural fit for Waste Management.
Target Price: $255; Rating: Two
Checkpoint: $210
RISKS: Industry and economic risk, competition and competitive pressures, and acquisition risk.
THREES
The Boeing Company BA; $171.55; 1,136 shares; 3.34%; Sector: Industrials
UPDATE: Shares of Boeing ($BA) fell 7.8% in October, as a steady flow of good news early in the month gave way to a disappointing production outlook in late October. On October 27, Boeing reported Q3 2026 revenue of $24.2 billion, a core loss of $0.34 per share, free cash flow of roughly $0.5 billion and a record $745 billion backlog. The bigger story came on the earnings call, where management said the production ramp would be slower than expected. Boeing now expects 737 deliveries to fall short of its 500-aircraft target for 2026, with 787 deliveries near the low end of its 90-100 range, as stabilizing 737 production at 47 per month will take into next year and the step to 52 is now targeted for the back half of 2027. CEO Kelly Ortberg expects 2027 commercial deliveries to rise more than 10%, and Boeing’s new free cash flow outlook calls for roughly $2 billion this year, $3 billion in 2027, $6 billion in 2028 and $10 billion in 2029. With Commercial Airplanes not expected to approach breakeven until early 2028, Defense, Space & Security and Global Services will continue to carry the company’s operating profits. With expectations for 2027 and 2028 revenue, EPS and free cash flow set to come down and management’s credibility once again on the line, we downgraded the shares to a Three rating from Two. Rather than sell into an oversold condition, we will bide our time and as needed, use near-term strength in BA shares to reduce our exposure, treating them as a source of cash or funding for other Portfolio moves. Given our Three rating, should more favorable data points emerge, we’d be inclined to reconsider BA’s role in the Portfolio.
October Price Change: -7.79%; Yield: N/A
INVESTMENT THESIS: Boeing is an aerospace company that reports its business in three operating segments – Commercial Airplanes (47% of 2025 sales), Defense, Space & Security (30%), and Global Services (23%). Our focus is on Boeing’s Commercial Airplane business, the operational leverage and EPS improvement that should follow increasing production levels. Factors fueling the rise in new aircraft demand, which is reflected in Boeing’s multi-year backlog, include post-pandemic passenger travel, the need to replace aging, inefficient fleets, and supply chain delays that have artificially tightened aircraft availability. Industry projections indicate that airlines will require over 43,000 new aircraft — primarily single-aisle jets — to meet rising passenger traffic and replace older, less efficient models.
Target Price: $265; Rating: Three
Checkpoint: $175
RISKS: Industry demand, defense spending, supply chain, and competitive risk.
Not Rated
EPS All-Stars Model; 6.57%; Sector: N/M
UPDATE: The EPS All-Stars strategy started out of the gate strong for the month, but as renewed concerns over AI and AI infrastructure funding rippled through the market, the basket became a big drag on the Portfolio’s October performance. The string of funding deals for SpaceX, Meta and more, as well as other supportive data points helped a bit, but the strategy was dragged substantially lower in late October. Upcoming catalysts for the basket include quarterly results by AMD and Astera Labs November 3, and if our suspicion is correct, the basket should also benefit as more AI funding uncertainty is removed. As a reminder, there are no price targets or ratings for each of the positions that make up the basket, and the only time we may adjust its composition during the quarter is if a company is acquired. The next reconstitution cycle for the EPS All-Stars model will be December 31 and January 2.
October Price Change: -22.43%
INVESTMENT THESIS: EPS All-Stars is a basket of large-cap companies that offer the fastest rate of EPS growth over a multi-year period. That basket is screened regardless of industry sector or sub-sector, which means the down-selected list of companies can span a wide array of sectors. The focus is on earnings growth because earnings growth is often seen as a signal of a company’s competitive strength, operational efficiencies, and future growth potential. Shares of companies that provide historically consistent earnings growth faster than the stock market receive premium valuations compared to those awarded to the S&P 500. And as we’ve often discussed with you, multiple expansion paired with earnings growth tends to drive outperformance relative to the market, better known as alpha. The basket of eight stocks is reconstituted on a quarterly basis to reflect updated EPS expectations for the current year and the following one.
Target Price: N/M
Checkpoint: N/M
RISKS: Macro and end-market risk, individual company risk, and consensus EPS expectations.
