October Monthly Roundup: Navigating the Tech Pullback. What We Bought and Our Shopping List.

We used the AI pullback to add to several holdings, made a handful of rating and target changes, and sharpened our shopping list.
We used the AI pullback to add to several holdings, made a handful of rating and target changes, and sharpened our shopping list.
Intel’s record drop leads a cascade in chip names with the S&P 500 and Nasdaq seeing their worst session since June, while defensive buying gave the Consumer Staples ETF its best month on record.
Over 400 of the S&P 500’s components were higher even as the index ended lower and the Russell 2000 gained for a fourth day while Amazon and Intel dropped after hours
– $GKOS +16% (record Q3 sales and a large FY revenue-guidance raise topped expectations)
– $INSM +14% (BRINSUPRI revenue grew 29% sequentially and guidance was raised for both BRINSUPRI and ARIKAYCE)
– $NCLH +12% (Q3 results topped guidance and the FY EBITDA and EPS outlooks were raised)
– $CVNA +8.4% (large Q3 revenue beat and accelerating retail-unit growth outweighed an EPS miss)
– $CMG +8.3% (Q3 comparable sales beat expectations despite a modest profit miss)
– $DASH +6.9% (record GOV, revenue and net income alongside an agreed $17B acquisition of CART)
– $LITE +6.9% (MRVL is reportedly in advanced acquisition talks, with a deal potentially announced next week)
– $EBAY +6.1% (Q3 revenue and GMV growth accelerated, reinforcing improving marketplace momentum)
– $HII +5.6% (record Q3 revenue, $32.4B of contract awards and higher FY shipbuilding-revenue guidance)
– $LLY +5.1% (annual revenue guidance topped expectations)
– $NVS +3.2% (2026 core operating-income guidance was raised despite a drug-trial write-down)
– $RCL +3.5%, CCL +3.0% (cruise names rise after NCLH beat and raised its FY outlook)
– $MSFT +1.1% (strong cash flow and cloud guidance signaled better returns from heavy AI investment)
– FTNT -27% (headline beat and raised guidance failed to offset sharply slowing product growth and concerns the refresh cycle is fading)
– NOW -19% (strong topline results were overshadowed by softer forward cRPO expectations and unfavorable renewal phasing)
– HLN -14% (Q3 organic sales missed and FY organic-growth guidance was cut to around 2.5%)
– OSK -13% (quarter missed and FY revenue and EPS guidance were cut as fire-truck production problems persisted)
– MRVL -12% (reported talks to acquire LITE sparked concerns over deal cost and execution risk)
– $CAT -11% (quarter beat, but the margin outlook and durability of AI-infrastructure demand fell short of elevated expectations)
– $GOOGL -11% (Q3 profit and revenue missed as softer search advertising and surging AI spending intensified cash-burn concerns)
– $EGO -10% (2026 gold-production guidance was cut and cost outlooks were raised amid a slower Skouries ramp)
– $CTSH -10% (Q3 beat, but the FY revenue-growth outlook narrowed and Q4 growth guidance disappointed)
– $SCI -8.9% (Q3 earnings missed and guidance was cut)
– $ZS -7.1%, $OKTA -7.5%, $PANW -6.8%, $RBRK -6.8%, $CRWD -6.8%, $SAIL -8.0% (cybersecurity names fall on FTNT’s product-growth slowdown and refresh-cycle concerns)
– $NBIS -6.7%, $CRWV -6.4%, $STRL -6.6% (AI-infrastructure names retreat as $GOOGL’s spending surge renews concerns about monetization and cash returns)
– $HUBS -6.5%, $TEAM -6.9%, $CRM -5.8%, $TYL -5.8%, $WDAY -6.1% (enterprise-software names weaken after NOW’s forward cRPO and renewal outlook disappointed)
Marvell’s potential Lumentum bid, Samsung’s comments on chip capacity, and other headlines are moving the market this morning.
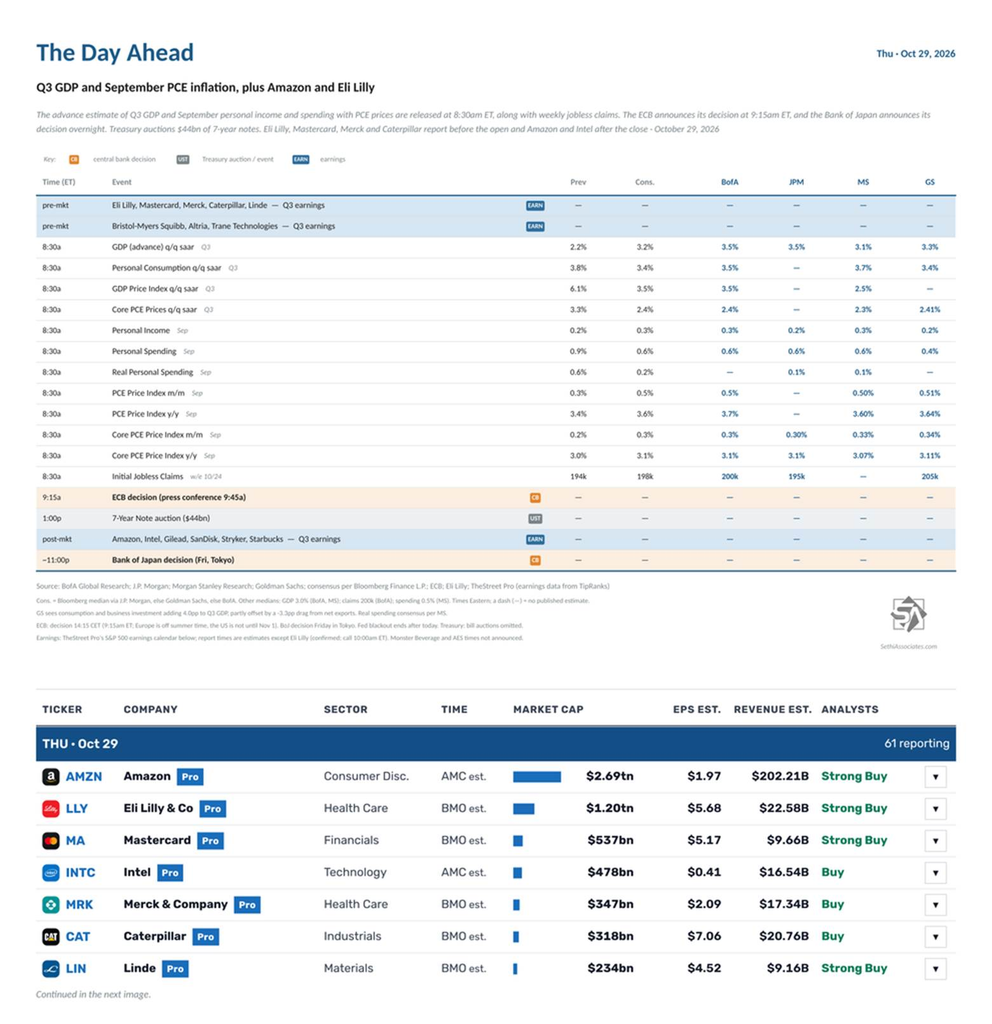
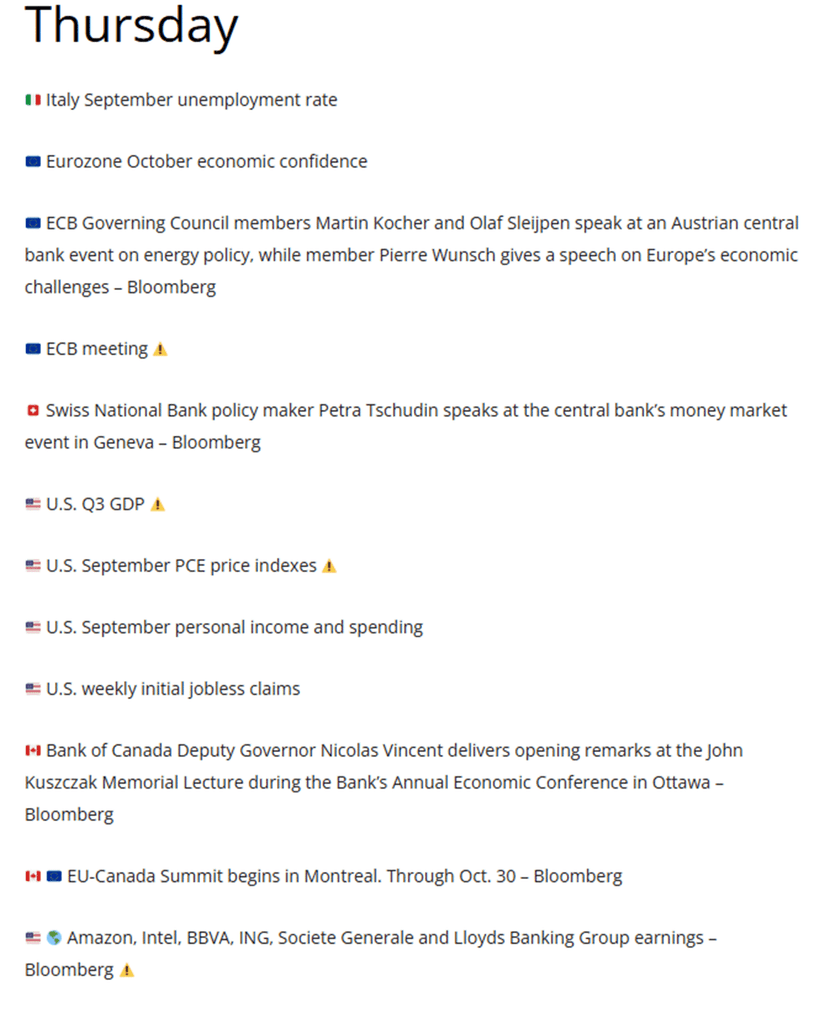
US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.
The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.
The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.
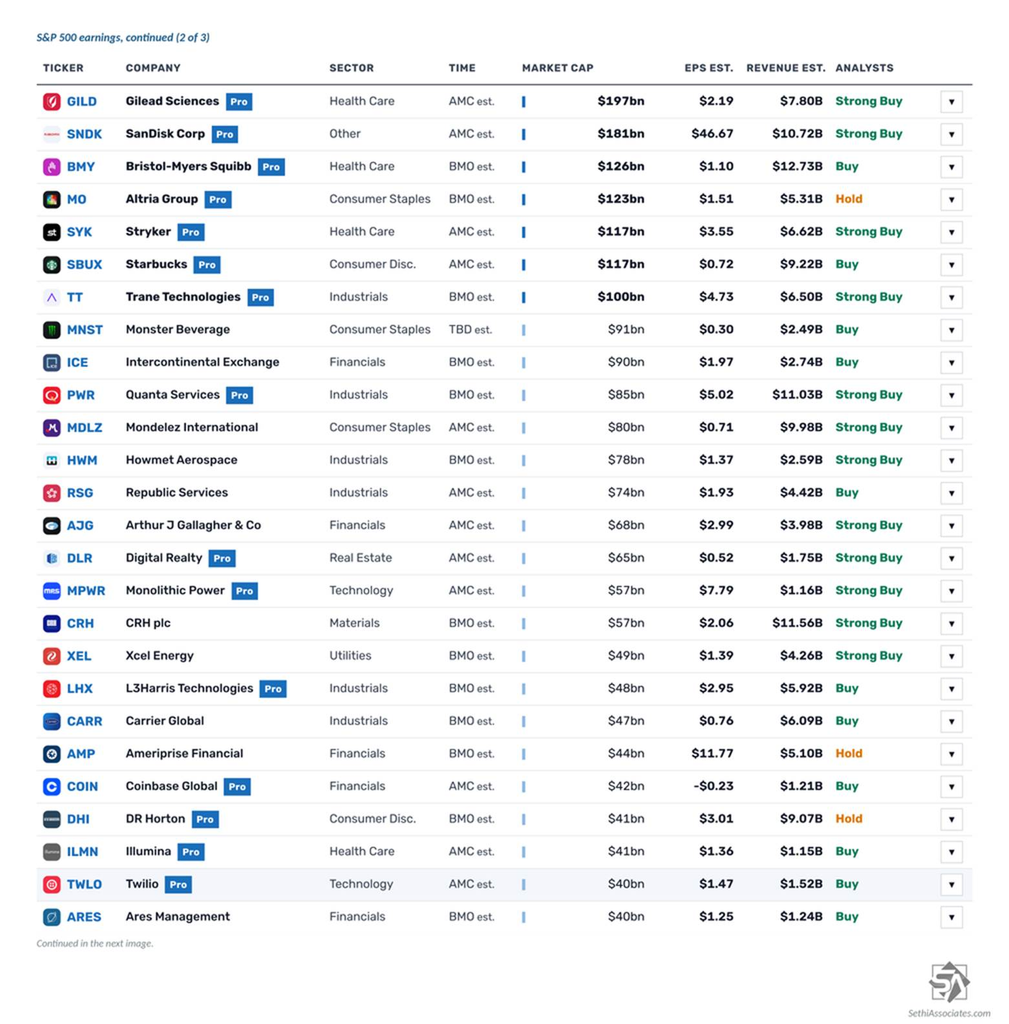
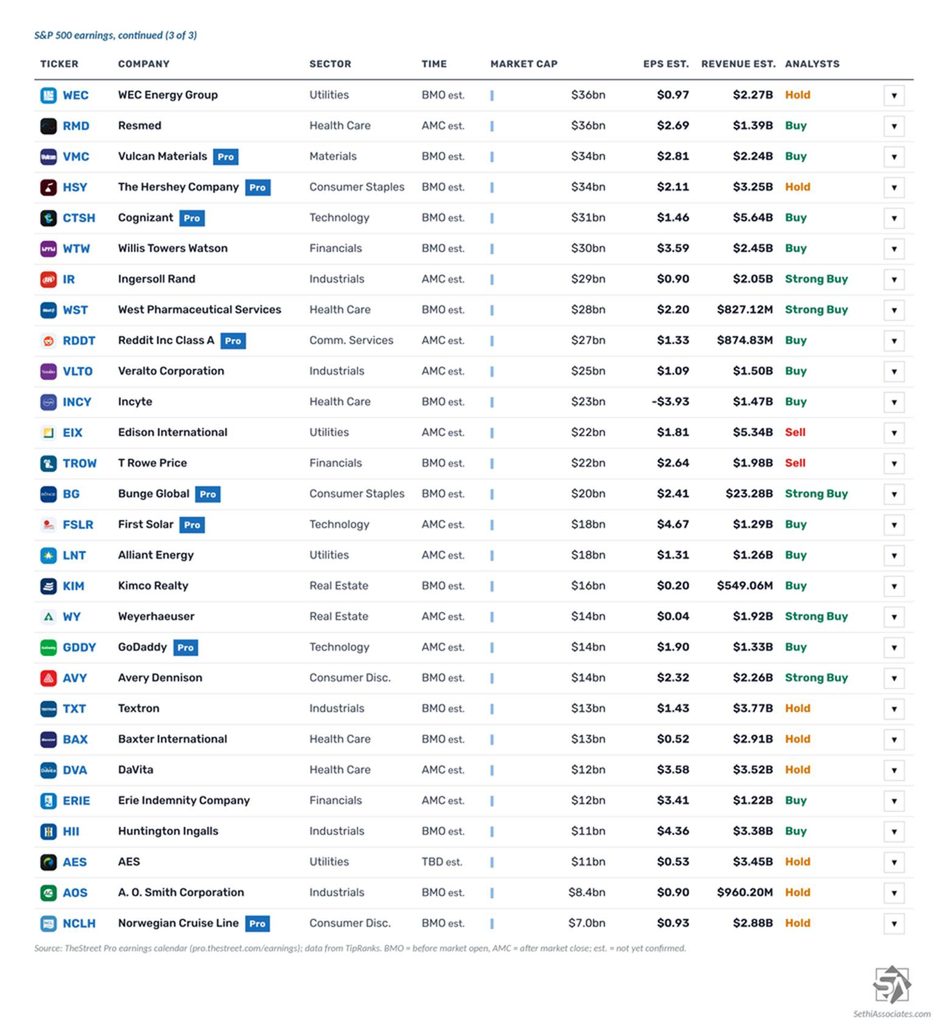
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:
Before the open: Eli Lilly ($LLY), Mastercard ($MA), Merck ($MRK), Caterpillar ($CAT), Linde ($LIN), Bristol Myers Squibb ($BMY), Altria ($MO), Trane Technologies ($TT), Intercontinental Exchange ($ICE), Quanta Services ($PWR), Howmet Aerospace ($HWM), CRH ($CRH), Xcel Energy ($XEL), L3Harris ($LHX), Carrier ($CARR), Ameriprise ($AMP), D.R. Horton ($DHI), Ares Management ($ARES), WEC Energy ($WEC), Vulcan Materials ($VMC), Hershey ($HSY), Cognizant ($CTSH), WTW ($WTW), West Pharmaceutical ($WST), Incyte ($INCY), T. Rowe Price ($TROW), Bunge ($BG), Kimco Realty ($KIM), Avery Dennison ($AVY), Textron ($TXT), Baxter ($BAX), Huntington Ingalls ($HII), A.O. Smith ($AOS) and Norwegian Cruise Line ($NCLH)
After the close: Amazon ($AMZN), Intel ($INTC), Gilead ($GILD), SanDisk ($SNDK), Stryker ($SYK), Starbucks ($SBUX), Mondelez ($MDLZ), Republic Services ($RSG), Arthur J. Gallagher ($AJG), Digital Realty ($DLR), Monolithic Power ($MPWR), Coinbase ($COIN), Illumina ($ILMN), Twilio ($TWLO), ResMed ($RMD), Ingersoll Rand ($IR), Reddit ($RDDT), Veralto ($VLTO), Edison International ($EIX), First Solar ($FSLR), Alliant Energy ($LNT), Weyerhaeuser ($WY), GoDaddy ($GDDY), DaVita ($DVA) and Erie Indemnity ($ERIE)
Time not announced: Monster Beverage ($MNST) and AES ($AES)
Outside the US, Shell ($SHEL), TotalEnergies ($TTE) and Volkswagen ($VWAGY) report.
Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.
From Christophe Barraud’s international Week Ahead rundown:
The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
Brent topped $116 and stocks pulled back on fears of renewed U.S.-Iran hostilities after the midterm elections. For the week, small caps led with the Russell 2000 up 2% while the S&P 500 and Nasdaq slipped.
We added to six holdings, and upgraded and lifted a price target on another as favorable AI data conflicted with market emotion.
Dougie Kass
3m ago
The tide is going out and now you understand my resentment towards Fin TV.
Look at their favorite stocks – $BABA $UBER $NFLX $SHAK $GEV $CAT Paramount, $BA, $RDDT the banks/brokers/private equity et al
They are swimming naked.
Memo to retail investors – they will not take ownership of their mistakes, the will continue to smile, they will be confident in view, they will take your assets.
They will cost you money.
Turn off your TVs.
Positions: None