From Peter Boockvar:
Positives,
1) Kevin Warsh told us the AI data center buildout is now on their radar and the committee ex two voting members decided to give themselves more time to scan the landscape.
2) Initial jobless claims remained very low at 194k vs 195k in the week before and that was 4k less than expected. The 4 week average slips to 197k from 198k. Continuing claims were low too at 1.701mm vs 1.722mm in the week before and about 200k under the 2025 trend.
3) Q3 GDP rose at a 3.4% q/o/q annualized rate, just above the estimate of 3.2% but was notably helped out by the price deflator which rose 2.3% instead of 3.2% as estimated. Consumer spending was above expectations. Massive increase in tech related imports was an actual drag on calculation but partly offset by the rise in inventories.
4) Core durable goods orders in September were a bit light relative to expectations with a .5% rise but comes off a solid August of up 1.6%.
5) Consumer confidence according to the Conference Board in October rose to 91.7 from 84.2 and was about 10 pts above the estimate. One yr inflation expectations slipped by 2 tenths to 5.8% after rising by a like amount in September.
6) With the slight dip in mortgage rates, purchase applications rebounded by 3.8% w/o/w after 7 weeks in a row of declines. Refi’s rose 2.7% w/o/w after 9 consecutive weeks lower.
7) New home sales in September totaled 676k, above the estimate of 651k.
8) The October Chicago manufacturing index fell to 55.3 from 58.8 and just below the estimate of 56 but still well above 50. The Dallas regional survey rose to 13.4 from 9.8.
9) From Amazon: AWS saw sales up 39% y/o/y, just above the estimate of up 38%. Positive for the receipients of the spend, “We still expect 2026 cash CapEx of approximately $220 billion, the majority for AWS, and expect to spend meaningfully more in 2027, with a clear line of sight to attract its financial returns.”
10) From Google/Alphabet: Cloud was where the strength was with revenues up 103% “driven by strong growth in GCP (Google Cloud) with strength in AI, including AI infrastructure and AI solutions, and core GCP. TPU system sales were also a meaningful contributor.”
11) From Microsoft: A strong quarter (their Q1) with the Azure cloud business seeing sales growth of 48% y/o/y vs the estimate of 44%.
12) From Ebay: Gross merchandise volume grew 13% with particular growth in “collectibles, Ebay Motors, fashion, and refurbished goods” And they spent more time talking about how they are really benefiting from the collectibles business which is “our largest growth contributor.”
13) From Caterpillar: “Non-residential construction investment continues to be supported by the IIJA, critical infrastructure programs, and data centers…Power generation grew 75%, driven by continued very strong demand for turbines and large reciprocating engines used in data center applications.”
14) From GE Vernova: “the demand environment remains strong and customers secure turbines further into the future. Demand also remains diverse, with approximately 100 customers in 25 different countries, of which approximately 80% are traditional customers and 20% are for data centers. We are seeing strong equipment pricing and total lifecycle economics in gas.”
15) From Nucor: “Turning to our demand outlook, Nucor continues to expect steel mill shipments growth to finish closer to the higher end of our 5% to 10% range for 2026, supported by several durable underlying drivers.”
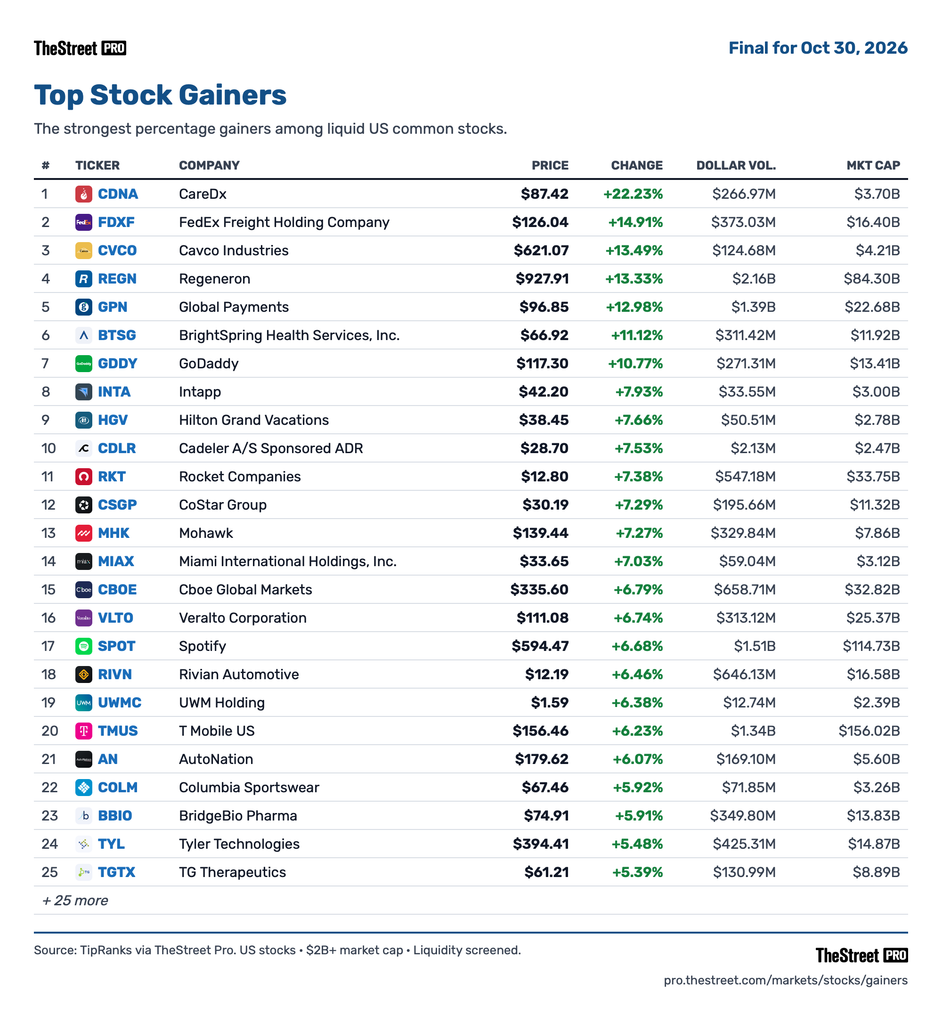
16) From Corning: “Enterprise grew sales 84% y/o/y, with GenAI product sales growing more than 100% y/o/y, significantly outpacing GPU unit growth.”
17) From Johnson Controls: “The demand environment also accelerated as we exited the year. Orders increased 44% driven by continued data center demand along with strong growth across other mission critical verticals including battery and semiconductor manufacturing and large research universities.”
18) From Celestica: “Celestica is well positioned to continue to support leading hyperscalers and frontier AI labs through the ongoing AI infrastructure supercycle. The demand environment continues to be very robust, supporting our 2027 revenue outlook, with customer demand forecasts meaningfully higher for 2028.”
19) From Starbucks: Global comps were up 7.2%, “marking our 5th consecutive quarter of comp growth, and US comps were up 7.7%…Our plan is working. More customers are visiting us because the Starbucks experience is better. Our coffeehouses are coffeehouses again…Strength is coming through the fundamentals.”
20) From Cheesecake Factory: “Comp sales and traffic growth meaningfully outperformed the broader casual dining industry, underscoring healthy demand for our brand and continued market share gains.”
21) From Jersey Mike’s: Comps rose 3%, “accelerating from 2.3% in the second quarter. We continue to outperform the fast casual segment this year…And I think it’s important to note that our gains are primarily driven by traffic both during the third quarter and year-to-date and anticipate that’s continuing in the fourth quarter.”
22) From Brinker’s: Chili’s comps were up 10%, “outperforming the casual dining industry by 720 bps” and “was driven by traffic increases of 6% versus a year ago.”
23) From Hilton Worldwide: “Strength in travel demand supported by favorable macro trends is driving RevPAR outperformance, a trend we expect to continue into 2027.”
24) From Hyatt Hotels: “Performance was driven by durable demand from high end travelers and continued strength across our luxury portfolio with some benefit from the FIFA World Cup in July and the timing of the Jewish holidays in September.”
25) From Royal Caribbean: “we continue to see accelerated momentum as consumers prioritize our vacations and experiences. Travel remains the number one leisure category where consumers intend to increase spending. Traveling more is a top priority for a third of Americans, and consumers see cruising as a good value due to high quality onboard amenities, pricing that includes meals, accommodations, and entertainment, and the ability to visit multiple destinations in one trip.”
26) From Vulcan Materials: On the public side, activity remains healthy at healthy levels. There is still a long tail from IIJA with approximately 35% of funds yet to be spent. There is a current extension of the Federal Highway Authorization Bill that maintains funding at current levels and is expected to be extened again until a bill is passed…On the private side, large project opportunities continue to drive non-residential activity…We are currently shipping on a variety of solar, wind, LNG, power plant and refinery projects in addition to large scale manufacturing projects like SpaceX and Toyota in South Texas and Scout Motors in South Carolina.”
27) From Blue Owl: “Portfolio health remains robust with no meaningful changes to our direct lending watchlist, portfolio growth trends, or our realized loss rate, which sits at a low 12 bps per annum for the total direct lending portfolio and at a net gain for our technology lending book.”
28) From ADP: “Labor markets continue to demonstrate resiliency, and we have seen our clients continuing to hire at a steady pace.” But, “I think it still is a relatively low hire, low fire environment.”
29) From Old Dominion Freight: “I think that just based on customer conversations we’ve had throughout the year, but even recently, we just continue to see stable demand trends.
30) From FedEx: “Revenue was up 12%, which includes a 4 percentage point boost from fuel price driven surcharge revenue. Underlying revenue growth was supported by base yield expansion across both segments, along with US domestic and international export volume growth…We were particularly encouraged by the strength from our B2B customers, including the fast growing data center vertical, which supported 28% y/o/y growth in international freight revenue.”
31) From UPS: “Turning to the holiday season. US consumers remain resilient and the outlook for holiday demand is strong. Industry forecasts for holiday online retail sales project an average increase of approximately 9% compared to last year.”
32) From Masco: Plumbing sales rose 5% adjusted and “This strong performance was driven by pricing, which increased sales by 5%, and higher North American volume, which contributed 2% to growth. This was partially offset by lower international volume and unfavorable mix.” In their Decorative Architectural business, pro paint sales were good while DIY was soft, the trend seen for many quarters.
33) From Mastercard: “While there continues to be economic and geopolitical uncertainty, consumers continue to spend, businesses continue to invest and commerce continues to expand. The economy, our overall business and our network have a resilient backdrop.”
34) From Visa: “Growth across consumer spend bands remained relatively consistent with prior quarters, with the highest spend band continuing to grow the fastest. We did not see signs of the lower spend consumer weakening in our volumes.“
35) From American Express: “Customer behavior looks very similar to what we’ve seen over the past year. Strong and consistent spend growth, especially in the T&E categories, balance growth in line with spend, high retention rates, and excellent credit performance…Airline spending accelerated to 13%, while restaurants, our largest T&E category, saw spend growth of 9%. US consumer spending was up 9.4% this quarter, reflecting the continued strength in our premium customer base. While growth moderated slightly through Q2, it was in line with Q1, and continues to run above the levels we saw in 2024 and 2025.”
36) From SoFi: “Member activity remains very strong. We continue to attract above average earners while spending, saving and investing trends remain positive. Credit performance once again improved and remains firmly in line with our expectations with all-in personal loan net charge-offs of 3.4%. We are not seeing evidence of a slowdown in how many members borrow, spend, save, or invest…For personal loans, we saw very strong credit performance for the quarter.”
37) From SLB: “It’s an exciting cycle for exploration. I think the combination of energy security as a heightened priority, as well as depleting reserves and the pressure of declining production are adding and fueling this investment in exploration.”
38) The Bank of Canada raised rates to still just 2.5%, a negative real rate. The ECB left rates unchanged as expected but set to hike again in December. The RBNZ surprised the market without a hike.
39) In Germany, their October jobs data was as expected and with an unemployment rate of 6.4%.
40) The October German IFO business confidence index rose a touch to 90.2 from 89.9 but the components were mixed as all of the gain came from the Expectations line as the Current Assessment fell. The IFO said simply, “The economic recovery is continuing” and a key reason for this is the continued rebound in manufacturing with this component going positive for the first time since April 2023 “as incoming orders increased.” Services in contrast softened but “IT service providers performed particularly well.” Construction rose and trade was unchanged.
Negatives,
1) Inflation pressures are still very obvious and the Fed decided to sit by and not react.
2) The September PCE inflation stats were spot on as expected, but remaining elevated, rising .5% headline m/o/m and .3% core with 3.6% and 3.1% y/o/y increases.
3) September income and spending figures were also as expected but because spending continues to exceed income, the savings rate fell to 3.8% from 4% and to the lowest since July 2008 not including the post Covid decline into 2022.
4) Private sector wages & salaries rose 3.1% y/o/y in Q3, just keeping pace with inflation with health care benefits eating into the growth as they rose 6.4%.
5) The October Richmond manufacturing index remained below zero at -2.
6) From Amazon: Retail online sales grew just 2%, the slowest pace since early 2023 in large part because of a shift in timing with Prime Day as it was in Q3 ‘25 and Q2 ‘26 and normalizing for this would have added an additional 400 bps of growth. Advertising sales were up just 12%, the weakest pace of growth since they started telling us about its financial details. Negative for their free cash flow, “We still expect 2026 cash CapEx of approximately $220 billion, the majority for AWS, and expect to spend meaningfully more in 2027, with a clear line of sight to attract its financial returns.”
7) From Google/Alphabet: “the strong growth in AI Mode queries had an impact because of the lower monetization we were seeing in AI Mode.” Youtube advertising revenue growth was only 9%. “We had negative free cash flow of $9.1 billion in the 3rd quarter driven by our investments in CapEx.”
8) From Microsoft: “we expect to continue to remain free cash flow positive in FY27” but “To complement cash generated by the business and preserve financial flexibility, we will access additional sources of funding when we believe it is attractive to do so.”
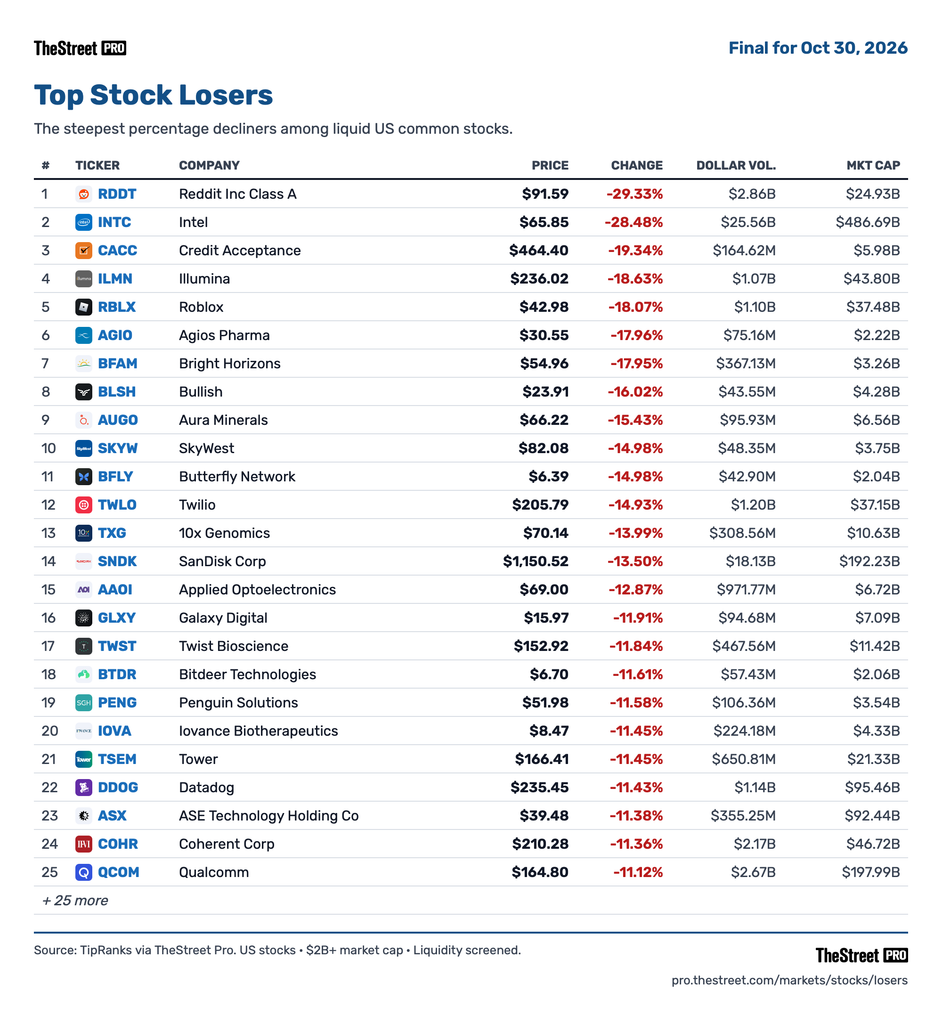
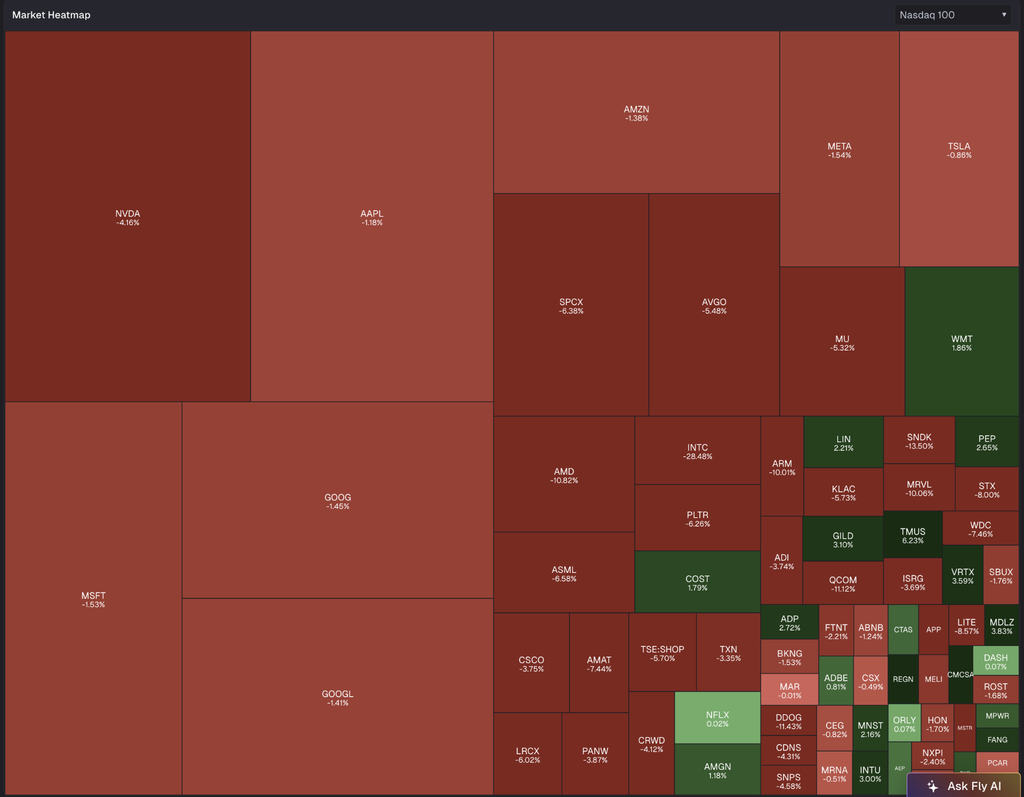
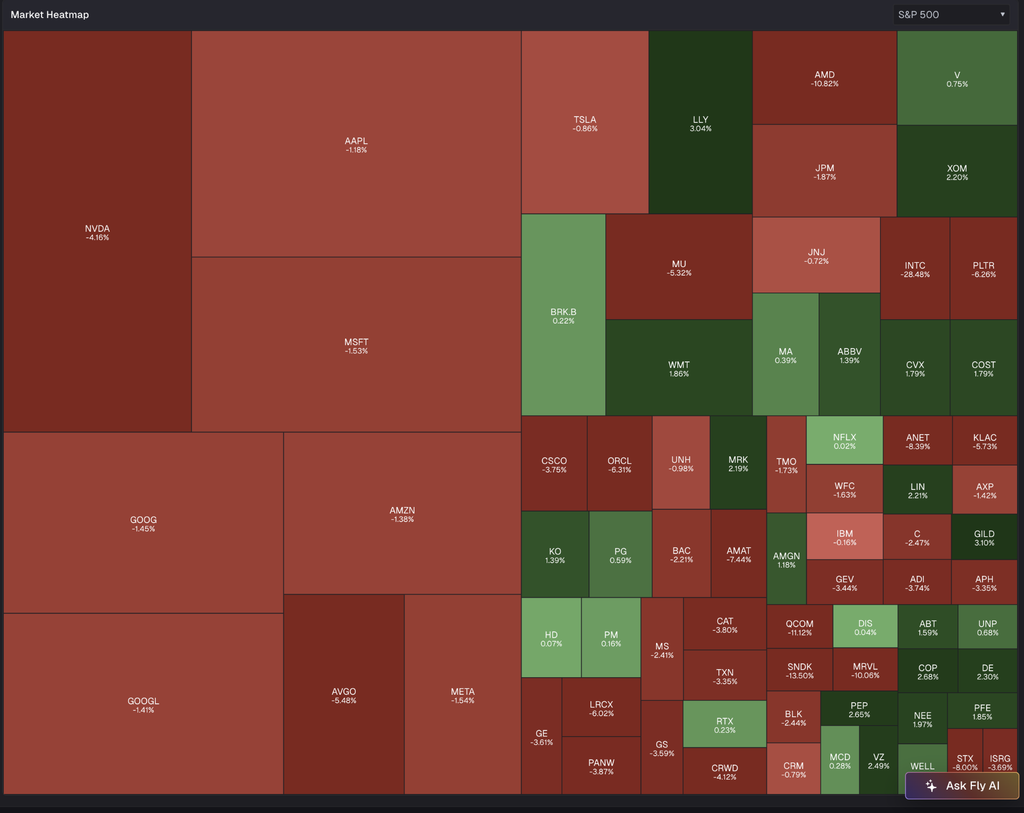
9) From Intel: “In recent weeks, our customers began signaling a PC slowdown based on the memory prices and availability. Year-to-date system endpoint prices have increased significantly, placing additional pressure on already limited IT budgets. The pace of this PC correction has accelerated over the last two months and our OEM partners are aggressively managing inventory to match the softer sell through.”
10) From Monro: Comps fell 1.8%, “reflecting an operating environment which continued to challenge the full service auto aftermarket. This was driven by lower store traffic, consumers that continued to defer higher ticket spending decisions and traded down to lower cost alternatives in tires.”
11) From Coca Cola: “the global operating environment continues to evolve. Geopolitical disruptions affect several parts of the world, cost pressures have accelerated, and all of these has an impact on many consumers…While our own business continues to have a lot of momentum across those channels, I think the underlying pressure across the consumer landscape is there.”
12) From Hershey: “the operating environment has become more challenging as consumers manage the cumulative pressure of higher gas prices, inflation, and interest rates. As September progressed, we saw consumers become more deliberate about spending, particularly in channels most exposed to higher gas prices like convenience stores where the U.S. candy, gum, and mint category declined nearly 5% in the month. That caution persisted into October, with growth moderating across snacking segments, though our categories are holding up comparatively well.”
13) From Wingstop: “During the 3rd quarter, domestic same store sales declined 5.4%, below our expectations. While we’re beginning to see positive signals from the changes we’ve made, the improvement in sales performance is taking longer than we initially anticipated, and the macro trends we are seeing among customers have intensified over the last few months.”
14) From Chipotle: “We entered the quarter with strong sales trends supported by our Recipe for Growth Initiatives. However, industry headwinds beginning in mid-July slowed our momentum. We quickly acted to reengage our guests with promotional offers…We were pleased to see trends normalize by late August, and we saw further improvement in September…October trends have softened, consistent with the broader industry.”
15) From Brunswick: “Headwinds from geopolitical uncertainty, inflation and higher borrowing costs are weighing on consumer confidence and discretionary spending, particularly for the value consumer, but our premium and core focused portfolio continues to be resilient and perform ahead of overall year-to-date SSI (statistical surveys) data.”
16) From DR Horton: “We expect continued pressure on our home sales gross margin in the first quarter, reflecting a lower average sales price and higher incentive levels to remain elevated in fiscal 2027…Looking ahead to fiscal 2027, we expect affordability constraints, higher mortgage rates and cautious consumer sentiment to continue to pressure new home demand.”
17) From Whirlpool: Sales were “impacted by softer industry demand in North America.”
18) From Vulcan Materials: “The continued lack of housing affordability and a challening rate environment are limiting residential construction activity.”
19) From International Paper: “Since our 2nd quarter call, incremental headwinds of approximately $145 million have emerged. The largest drivers are higher diesel fuel and distribution costs, along with increased volume pressure.”
20) From Masco: On cost inflation, “in Q3, we experienced mid single digit inflation from input costs in both of our segments and we expect that for the year in its totality.”
21) From Sherwin Williams: Impacting gross margin in part was “higher raw material and supply chain related costs…From a cost perspective, we are not immune from inflation. We will continue to manage this variable through targeted pricing actions as needed, disciplined control of general and administrative expenses, and simplification initiatives that drive speed and efficiency.”
22) From Ford Motor: “Our guidance now assumes a US SAAR of 16.5 million units, commodity headwinds approaching $2.5 billion y/o/y, an increase of about $500 million as we continue to see increasing pressure from input costs. In addition, higher fuel prices are impacting our freight and energy costs. But notably, we are not seeing it impact customer demand for trucks and fleet vehicles at this point. We now expect full year US industry pricing to be about 100 bps higher y/o/y, which is a .5 point higher than our previous assumption.”
23) From Tractor Supply: Several broader trends continue to pressure the categories we serve. Elevated interest rates and reduced housing mobility are weighing on property improvements and larger projects. Pet ownership headwinds, particularly new pet acquisition, continue to affect demand in certain categories…Across the farm economy, increases in commodity prices and operating costs are influencing purchasing decisions. Customers continue to spend, but remain cautious. In our most recent consumer work, more than 60% said they felt less comfortable making non-essential purchases than six months ago. Inflation, higher fuel costs, and broader uncertainty continued to weigh on household budgets and discretionary spending.”
24) While not expected to hike rates this week, the BoJ at just 1.25% has rates still well below inflation.
25) Tokyo CPI for October rose 2.6% y/o/y, one tenth less than anticipated and vs 3% in the month before. The headline rate was higher by 2.8%, one tenth above the forecast and vs 2.7% in the month before.
26) France’s economy unexpectedly contracted by .1% y/o/y instead of rising .3% as expected. CPI in France was higher by 3.8% in October, above the estimate of 3.6%.
27) Consumer price inflation in Spain in October was higher by 4.9% y/o/y but as expected.
28) The October Eurozone Economic Confidence index fell to 96.9 from 97.5 and that is the lowest since June. Manufacturing continued to improve but services, consumer, retail and construction confidence all moderated.
29) A disappointing outcome with the Brazilian election.
Position: None