Market Postscript

* Here are my thoughts following the plethora of EPS releases after the close…

With Google’s ($GOOGL) miss (the deceleration in its core business was unanticipated by every panelist on “the show”), Meta’s ($META) continued awful share price action, Nvidia’s ($NVDA) price rollover threatening chart support, Amazon’s ($AMZN) lackluster share price action (and underperformance) and some possible toppiness in Apple’s ($AAPL) share price, we are left with one… Microsoft ($MSFT).

Meanwhile, ServiceNow’s ($NOW) disappointing results (the company cut subscription revenues for the full year) will likely weigh heavily on software stocks (which were market leaders) tomorrow morning.

I remain independent in view.

As I said in response to subscriber jryan, most stocks do not meet my standards to buy and I won’t change my process or discipline — even if Perma Bulls Tom Lee and Dan Ives (confidently) see clear skies ahead…

The S&P Short Range Oscillator registered 1.84% (more overbought than the prior day) and I ended the day with a large short positioin in $SPY.

Position: Short SPY (L)

SK Hynix Gives Another Boost to Chip Stocks

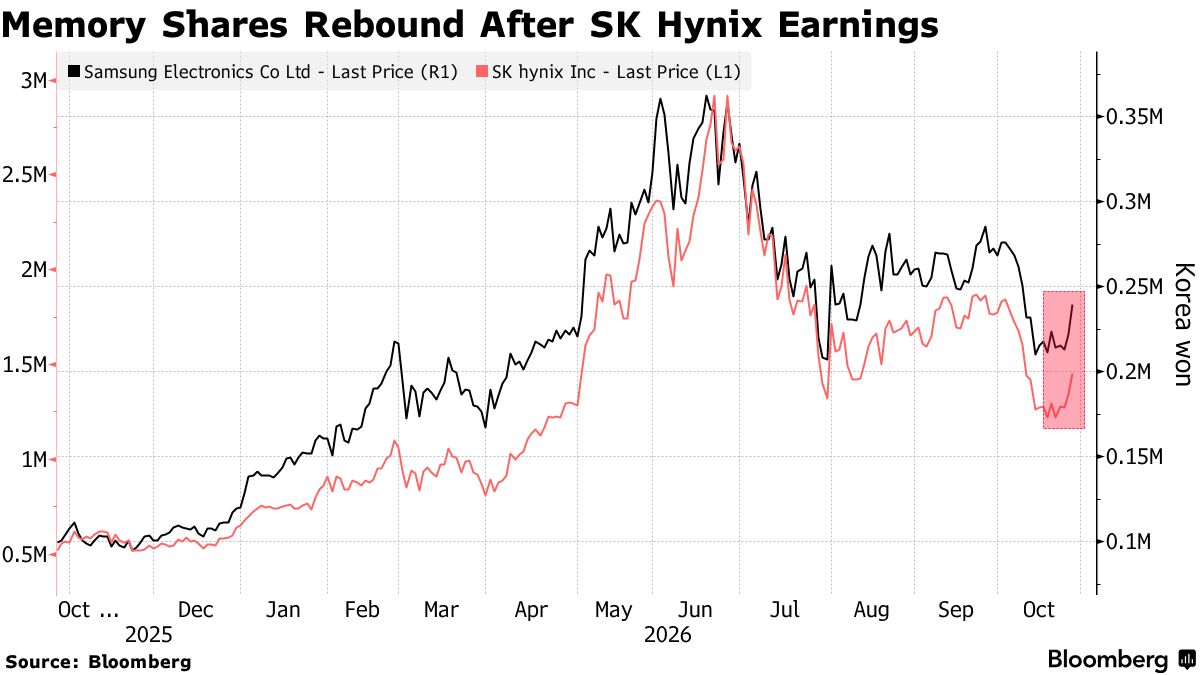
The chip rebound got another boost overnight as SK Hynix ($SKHY) reported record third-quarter results, saying it has sold out of DRAM and high-bandwidth memory (HBM) through 2029 and that HBM demand is double what it can supply, per Reuters. It also unveiled about 60 trillion won (roughly $45 billion) of additional buybacks and dividends. Its shares closed up 10.9% in Seoul, Samsung Electronics rose 9% and the Kospi gained 6.6%, per CNBC. The iShares Semiconductor ETF ($SOXX) is indicated up another 1% premarket as of 8:30 a.m. ET after gaining nearly 7% over the past two sessions.

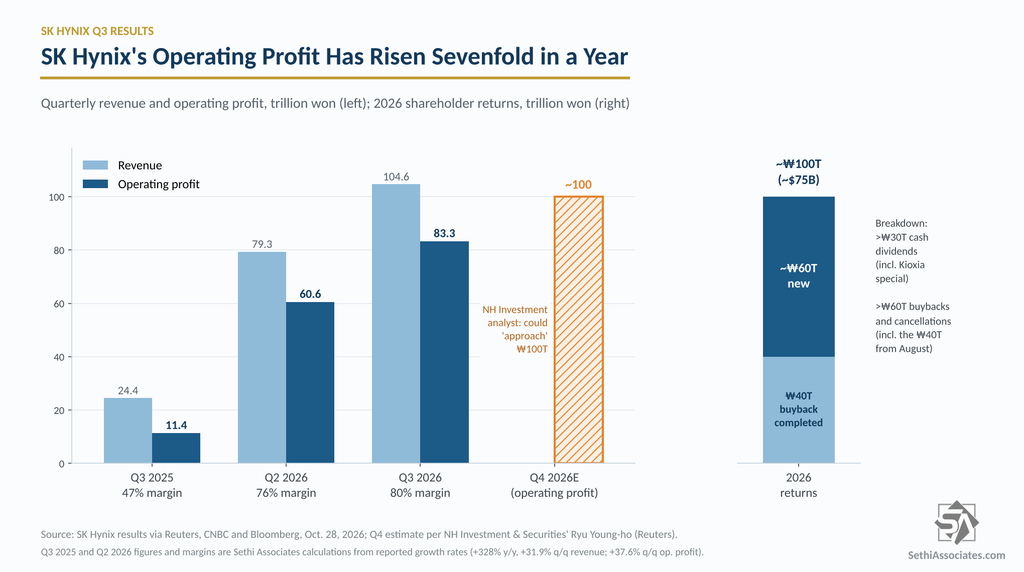
SK Hynix, which holds almost half the HBM market and supplies the memory for Nvidia’s ($NVDA) AI chips, saw revenue more than quadruple from a year earlier to a record 104.6 trillion won ($78.9 billion), beating the 98.3 trillion won LSEG estimate. Operating profit rose more than sevenfold to a record 83.3 trillion won, versus 76.7 trillion won expected. DRAM average selling prices rose by a high-20s percentage from the prior quarter, and server DDR5 shipments jumped more than 40%, per CNBC. One analyst though sees that accelerating through the end of the year: “Given that the fourth quarter is traditionally stronger, operating profit could approach 100 trillion won,” NH Investment & Securities’ Ryu Young-ho told Reuters. Not everything beat, though: net profit of 39.8 trillion won fell well short of the 61.4 trillion won FactSet consensus, per the WSJ.

The outlook is moving the group. SK Hynix expects the memory shortage to last through 2030. It has long-term agreements, typically five years, with 14 major customers covering more than half its 2027-2028 capacity, and it plans to raise capex “significantly” next year from at least 40 trillion won this year. Memory already accounts for about a third of AI data center costs, and Macquarie expects HBM prices to more than double in 2027, per Bloomberg.

And in a sharp contrast with Meta’s equity raise, SK Hynix is sending money to shareholders. After Meta Platforms ($META) announced this week it is raising $98 billion from investors to fund its AI spending, SK Hynix is returning about 100 trillion won (roughly $75 billion) to shareholders this year. That comprises more than 30 trillion won in dividends and more than 60 trillion won in buybacks and cancellations, including the 40 trillion won announced in August.

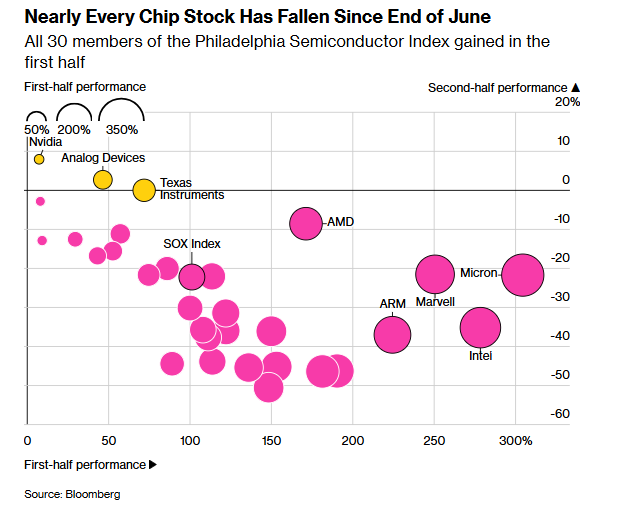
The rebound has ground to make up. SK Hynix shares have more than doubled this year but are still about half their June record, per Reuters, and nearly every chip stock has fallen since the end of June, per Bloomberg. Samsung reports Thursday.

A Fair Criticism Deserves a Response

Subscriber jryan (below) delivered some reasonable comments and criticism yesterday in the Comments Section. 

Basically he said he is “getting sick of reading about cannabis and Fin TV commentary” — and he wants more (long) stock suggestions, etc.  

I wanted to respond in the first column of the day. 

* Few longs have represented value to me as I have been unduly negative for a lengthy period of time. I take ownership of that.

* The stocks that I have owned have recently been Staples ($KO, $PEP, $PG and $KMB), selected cannabis names and some others. The consumer nondurable stocks have been fine recently (and I have taken profits in them). We shall see about cannabis — a speculative sector and my focus has been intermediate-term based on the improved likelihood of rescheduling and other factors clearly delineated in my Diary.

*As to the CNBC constructive criticism. I point these out not only as an advocate of the retail viewer that should see timestamps (panelists taking ownership) and observe better company interviews, but so they can evaluate the merits and process of the panelists’ recommendations and become better-informed investors through more hard-hitting interviews (that serve more than as a marketing tool of companies). 

* But the criticism directed to Fin TV also is intended to highlight investment recommendations from panelists and guests that I strongly disagree with. Choosing stocks to avoid (in that FIN TV criticism) can be as valuable or even more valuable than choosing stocks to buy. Consider my negative comments towards $BA, $BABA, $META, $UBER, $NFLX, $RDDT, $TTAN, $DIS, $CLF, $MRNA and $UNH (a few years back) etc. that were mostly confidently and strenuously recommended on CNBC. 

* My “More Tales From Nvidia” series is intended to deliver the idea that the functionality, productivity and ROIC on the enormous capital spend may disappoint the many and multitude of optimists on AI. I have felt that my contrarian and non herd-like observations were valuable in a backdrop of near-universal bullishness (that is readily and frequently available from the buy/sell sides, panelists and guests). My view was that dwelling on “More Tales” had statistical value in that over 40% of the S&P is comprised of large-cap tech.   

* As to specific AI beneficiaries, I have admitted (often) of missing $MSFT and $GOOGL. The valuation on $AAPL seems foolish to me — the shares have prospered and I have been wrong.  But the others ($META, $AMZN and even $NVDA) have not set the world on fire this year. As to memory and chip stocks, they have been “the world’s fair” up until the summer but awful since late June. Not only do I think these companies are “overearning,” but the volatility is not for me and not consistent and doesn’t conform with my appetite for risk. 

*  The financial stocks were quite strong until early summer. I repeatedly cautioned not to embrace banks, brokers and private equity shares (I successfully shorted $BX, $KKR and $APOL since then). Viewed by panelists as perhaps the best “value play,” financials have been dismal over the last four months.  We avoided this decline (in $C, $JPM, $BAC, $GS, $MS et al).

* The stocks that I have been short in the AI sphere have been terrific (to the downside) — $ORCL and $CRWV. (Avoiding them as longs has also been a valuable contribution.) My recent foray into shorting NVDA was profitable also. 

* As to my preoccupation with CNBC I suggest taking the number of words written about FIN TV and divide it by the number of words written on other subjects daily. You will find my criticism is dwarfed by my other columns. In the scheme of things my criticism is de minimis. 

* Finally, to jryan I say there are many other contributors that actively recommend longs and provide a valuable service.

All this said I am imperfect.

I take ownership of my mistakes.

The transparency of my Diary exposes my blemishes. 

I believe jryan has some good points and I will purposefully look for more long ideas in the future. 

I truly appreciate jryan’s comments and I have tried to respond to his concerns:

jryan

Just a thought. There used to be a lot of different investment ideas, stock suggestions etc., but all it seems to be now is cannabis and CNBC commentary, which I don’t watch anyway. Kind of getting sick of it, especially the cannabis info, is it ever going to pay off? Likely, but it will be quite a while from today, if ever. But at least it’s easier to scroll through the commentary and use less time.

Position: Long KO (VS), PG (VS), KMB (VS), MSOS common (VL) and calls (VS), VRNO (VS), GLAS (S), GTBIF (S), TRLV (VS), CURLF (VS); Short AAPL (S)

Expect Small Earnings Growth From the Market’s Biggest Movers

While everyone will be focused on earnings from Alphabet ($GOOGL), Microsoft ($MSFT) and Amazon ($AMZN) this week, a Wall Street Journal analysis shows they aren’t expected to contribute enough to third-quarter S&P 500 earnings growth to get their own callout in terms of needle-movers. That’s quite a change from the second-quarter season, when their “other income” was one of the biggest sources of upside surprise.

In contrast, Nvidia ($NVDA) and Micron Technology ($MU) alone account for about a third of the nearly 30% year-over-year growth in S&P 500 third-quarter earnings. That figure blends actual results from companies that have reported with estimates for those that haven’t. Just 10 companies account for nearly two-thirds of that growth. Along with Nvidia and Micron, they are Broadcom ($AVGO), Exxon Mobil ($XOM), EchoStar ($SATS), Sandisk ($SNDK), Marathon Petroleum ($MPC), Meta Platforms ($META), Chevron ($CVX) and Valero Energy ($VLO).