Microsoft Beats, Alphabet Misses and Fed Holds Steady

Oracle reassurance moved the market more than the Fed did.
Oracle reassurance moved the market more than the Fed did.
“The sea was angry that day, my friends – like an old man trying to send back soup in a deli.”
– George Costanza
Today’s market is different than some of the past sharp drawdowns in the last 12-18 months.
* The drop is broad and deep — with other asset classes like gold and bitcoin joining the downside.
* There is no single catalyst like Leopold (Situational Awareness hedge fund liquidation) to blame on the market’s selloff.
* The weakness in financials over the last several months is now accelerating, with no respite whatsever.
* The decline in over stretched stocks is breathtaking — especially the over conceptualized AI stocks on the periphery (e.g. $GEV -$105 to $820). Look at the breakdown in $CAT’s chart (-$45 and down from $950 to $695 in a straight line).
* We are witnessing a classical (but violent) rotation. See the remarkable strength in staples and healthcare.
* A sign of flight to quality/safety seen in a pronounced rise in bond prices (and in lower bond yields). ($TLT +$1.20 today)
Position: None
$TLT at the day’s low and now negative on the day.
Position: None
* Monday was another day of divergences — with interest rates moving higher and foul market breadth.
* Meanwhile, momentum-based products and strategies (that know everything about price and nothing about value) followed the strong intraday price momentum and ignored the aforementioned divergences.
The S&P Short Range Oscillator moved further into oversold territory at -0.66% vs. -0.08%.
As I mentioned in yesterday’s “Regrets” column, I missed an opportunity to short the gap higher yesterday because of machine/algo-derived market uncertainty and volatility.
Let me explain…
Today’s market structure, as I have previously noted, has produced an unpredictable short-term pattern of equity prices. The ever-growing treasure chests of index funds control stock floats and the pods and other momentum-based quant funds have become the marginal buyer/seller (in which unemotional machines and algorithms dominate much of the trading activity of passive strategies and structures).
Yesterday the “buyers lived higher” — serving to exaggerate the day’s advance. The problem I have and others have is that one simply doesn’t easily know when the buying will be sated and how high the machines will take stocks higher.
On Monday, with S&P futures more than +65 handles, the buying just stopped (without a catalyst) and the S&P fell by about -30 handles into a large ($8 billion) market on close imbalance. This morning S&P futures are -5 handles (-0.05%). (The Nasdaq, in percentage terms, is down more -0.40%.)
Importantly Monday’s advance was featured by the conspicuous divergences of higher interest rates and poor breadth — two signposts that usually lead me to short the indices:
* Another rise in interest rates ($TLT ended at the day’s lows).
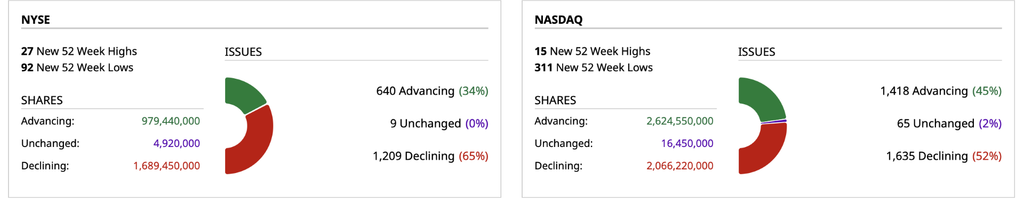
* Market breadth was foul:
“Kill the machines before they kill our markets.”
Position: None
Bond prices at the low of the day.
$TLT -$0.60.
The dead cat bounce might be over.
Position: None
The pros start to turn bearish just as the big cap tech stocks reach oversold. Are retail traders far behind?
While there are some similarities to 1987, there are also some major differences.
TSMC beat and still fell, a giant AI offering is coming, and the market wants to know what AI growth costs.
Stocks were slammed after a hot core CPI report, but bonds rallied and biotech rose.
We finally got our broadening in equities as yields softened but a packed calendar including CPI, bank earnings and Warsh will put it to the test