Kill the Machines Before They Kill Our Markets

* Monday was another day of divergences — with interest rates moving higher and foul market breadth.
* Meanwhile, momentum-based products and strategies (that know everything about price and nothing about value) followed the strong intraday price momentum and ignored the aforementioned divergences.
The S&P Short Range Oscillator moved further into oversold territory at -0.66% vs. -0.08%.
As I mentioned in yesterday’s “Regrets” column, I missed an opportunity to short the gap higher yesterday because of machine/algo-derived market uncertainty and volatility.
Let me explain…
‘Buyers Live Higher, Sellers Live Lower‘
Today’s market structure, as I have previously noted, has produced an unpredictable short-term pattern of equity prices. The ever-growing treasure chests of index funds control stock floats and the pods and other momentum-based quant funds have become the marginal buyer/seller (in which unemotional machines and algorithms dominate much of the trading activity of passive strategies and structures).
Yesterday the “buyers lived higher” — serving to exaggerate the day’s advance. The problem I have and others have is that one simply doesn’t easily know when the buying will be sated and how high the machines will take stocks higher.
On Monday, with S&P futures more than +65 handles, the buying just stopped (without a catalyst) and the S&P fell by about -30 handles into a large ($8 billion) market on close imbalance. This morning S&P futures are -5 handles (-0.05%). (The Nasdaq, in percentage terms, is down more -0.40%.)
Importantly Monday’s advance was featured by the conspicuous divergences of higher interest rates and poor breadth — two signposts that usually lead me to short the indices:
* Another rise in interest rates ($TLT ended at the day’s lows).
* Market breadth was foul:
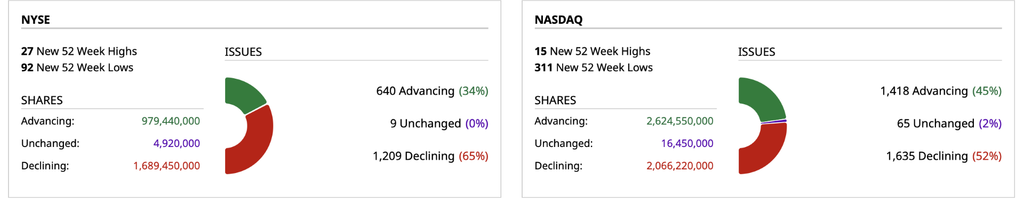
“Kill the machines before they kill our markets.”
Position: None
