The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
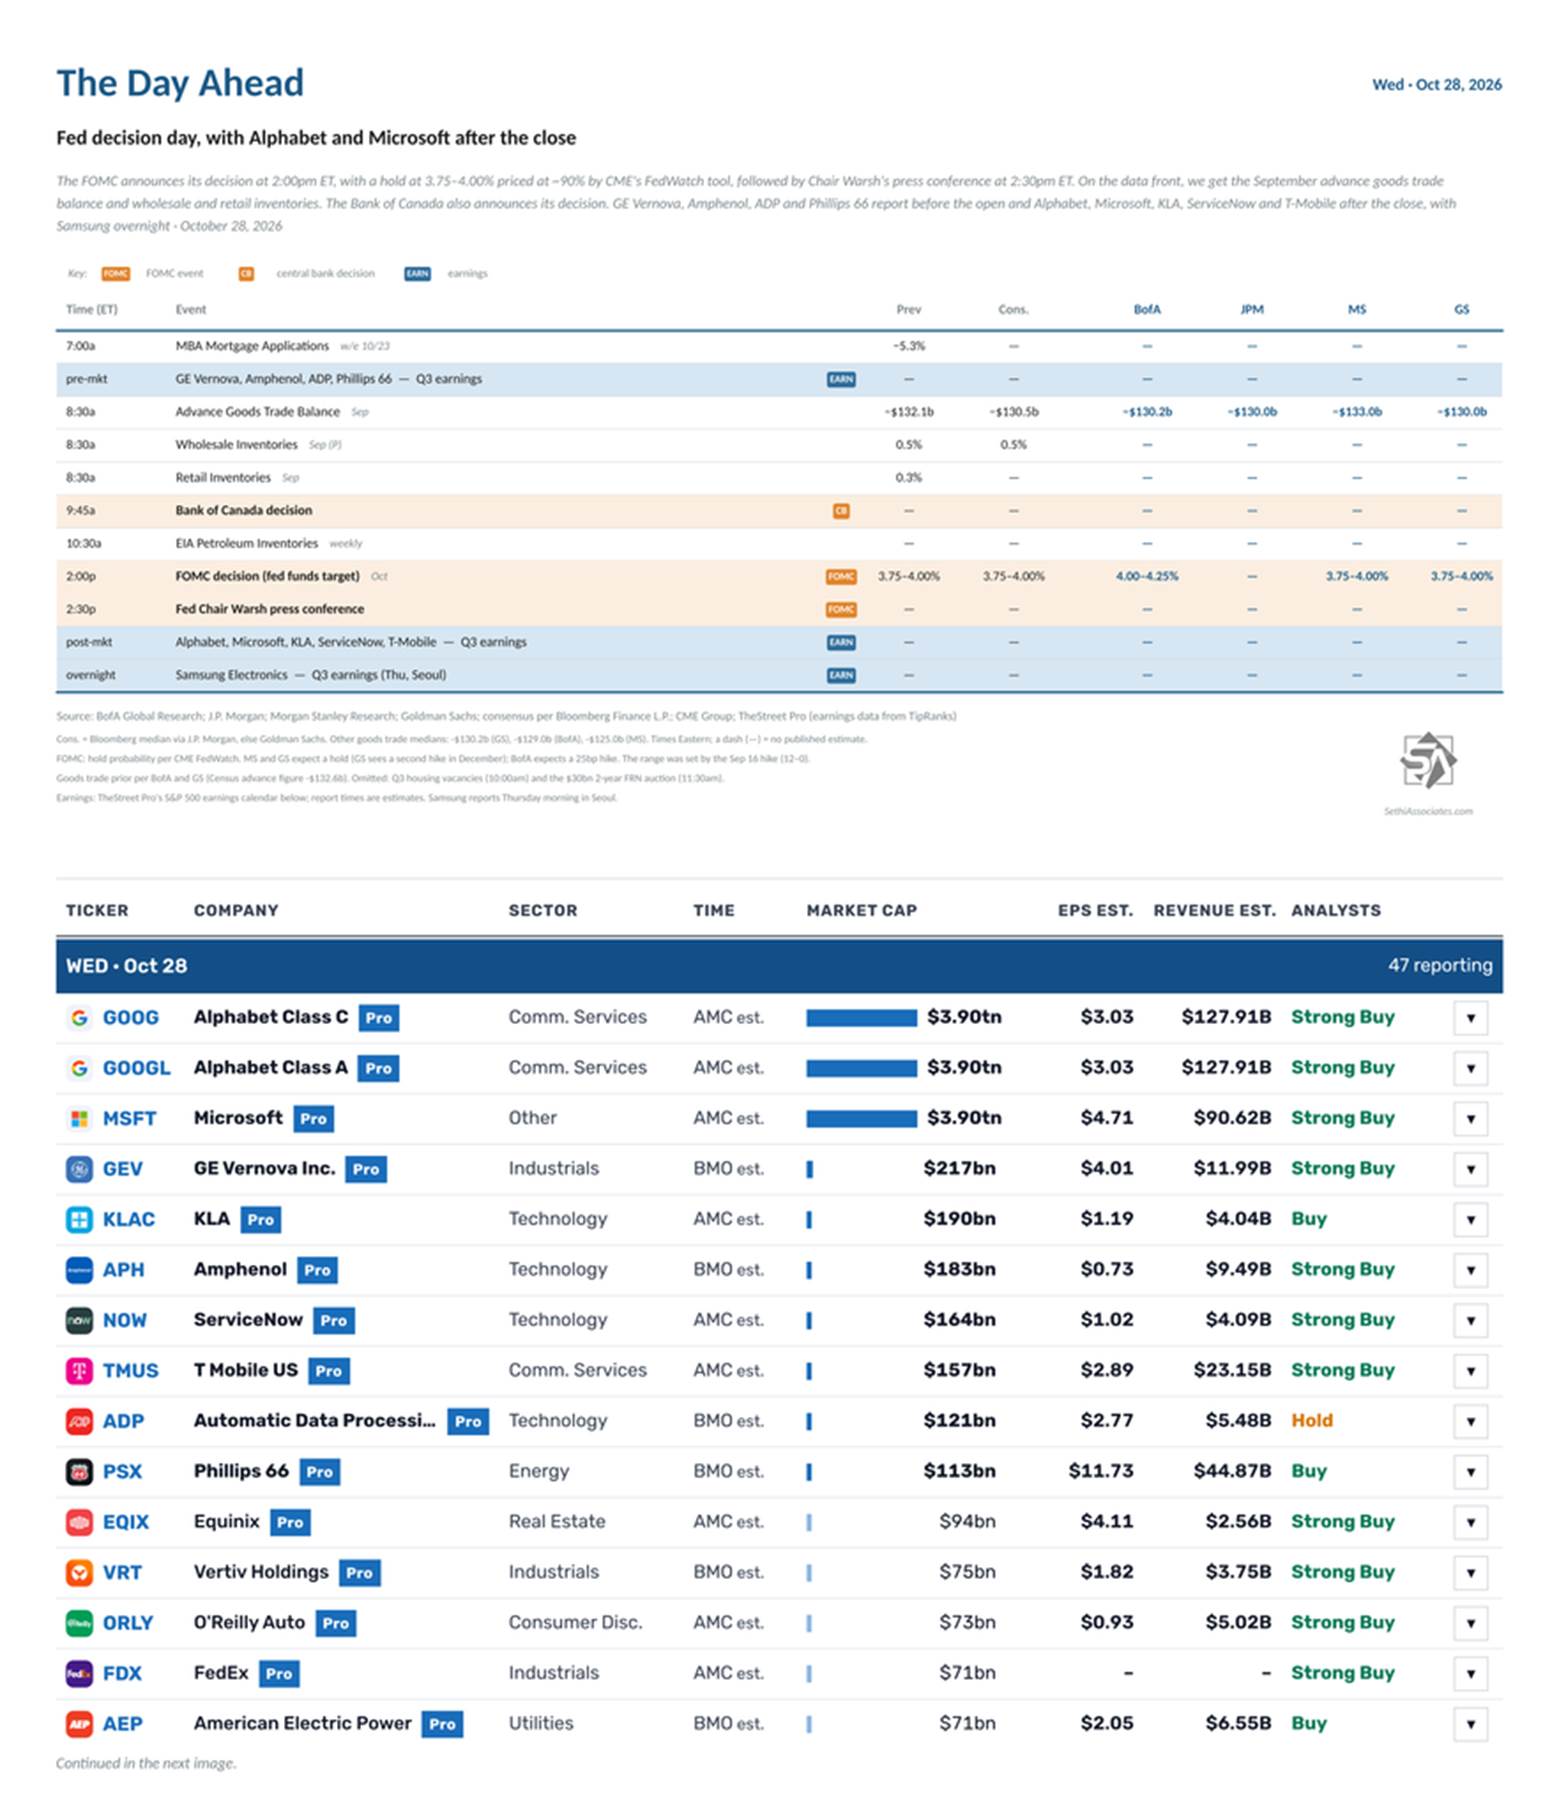
US economic data is light Wednesday, with just the September advance goods trade balance and wholesale and retail inventories plus weekly MBA mortgage applications and EIA petroleum inventories.
The FOMC takes center stage announcing its decision at 2pm ET, with a hold priced at ~93% by CME’s FedWatch tool, followed by Chair Warsh’s press conference at 2:30pm ET.
The only Non-Bill (>1yr in maturity) US Treasury auction is a $30B 2-year floating-rate note (not followed due to its floating nature).
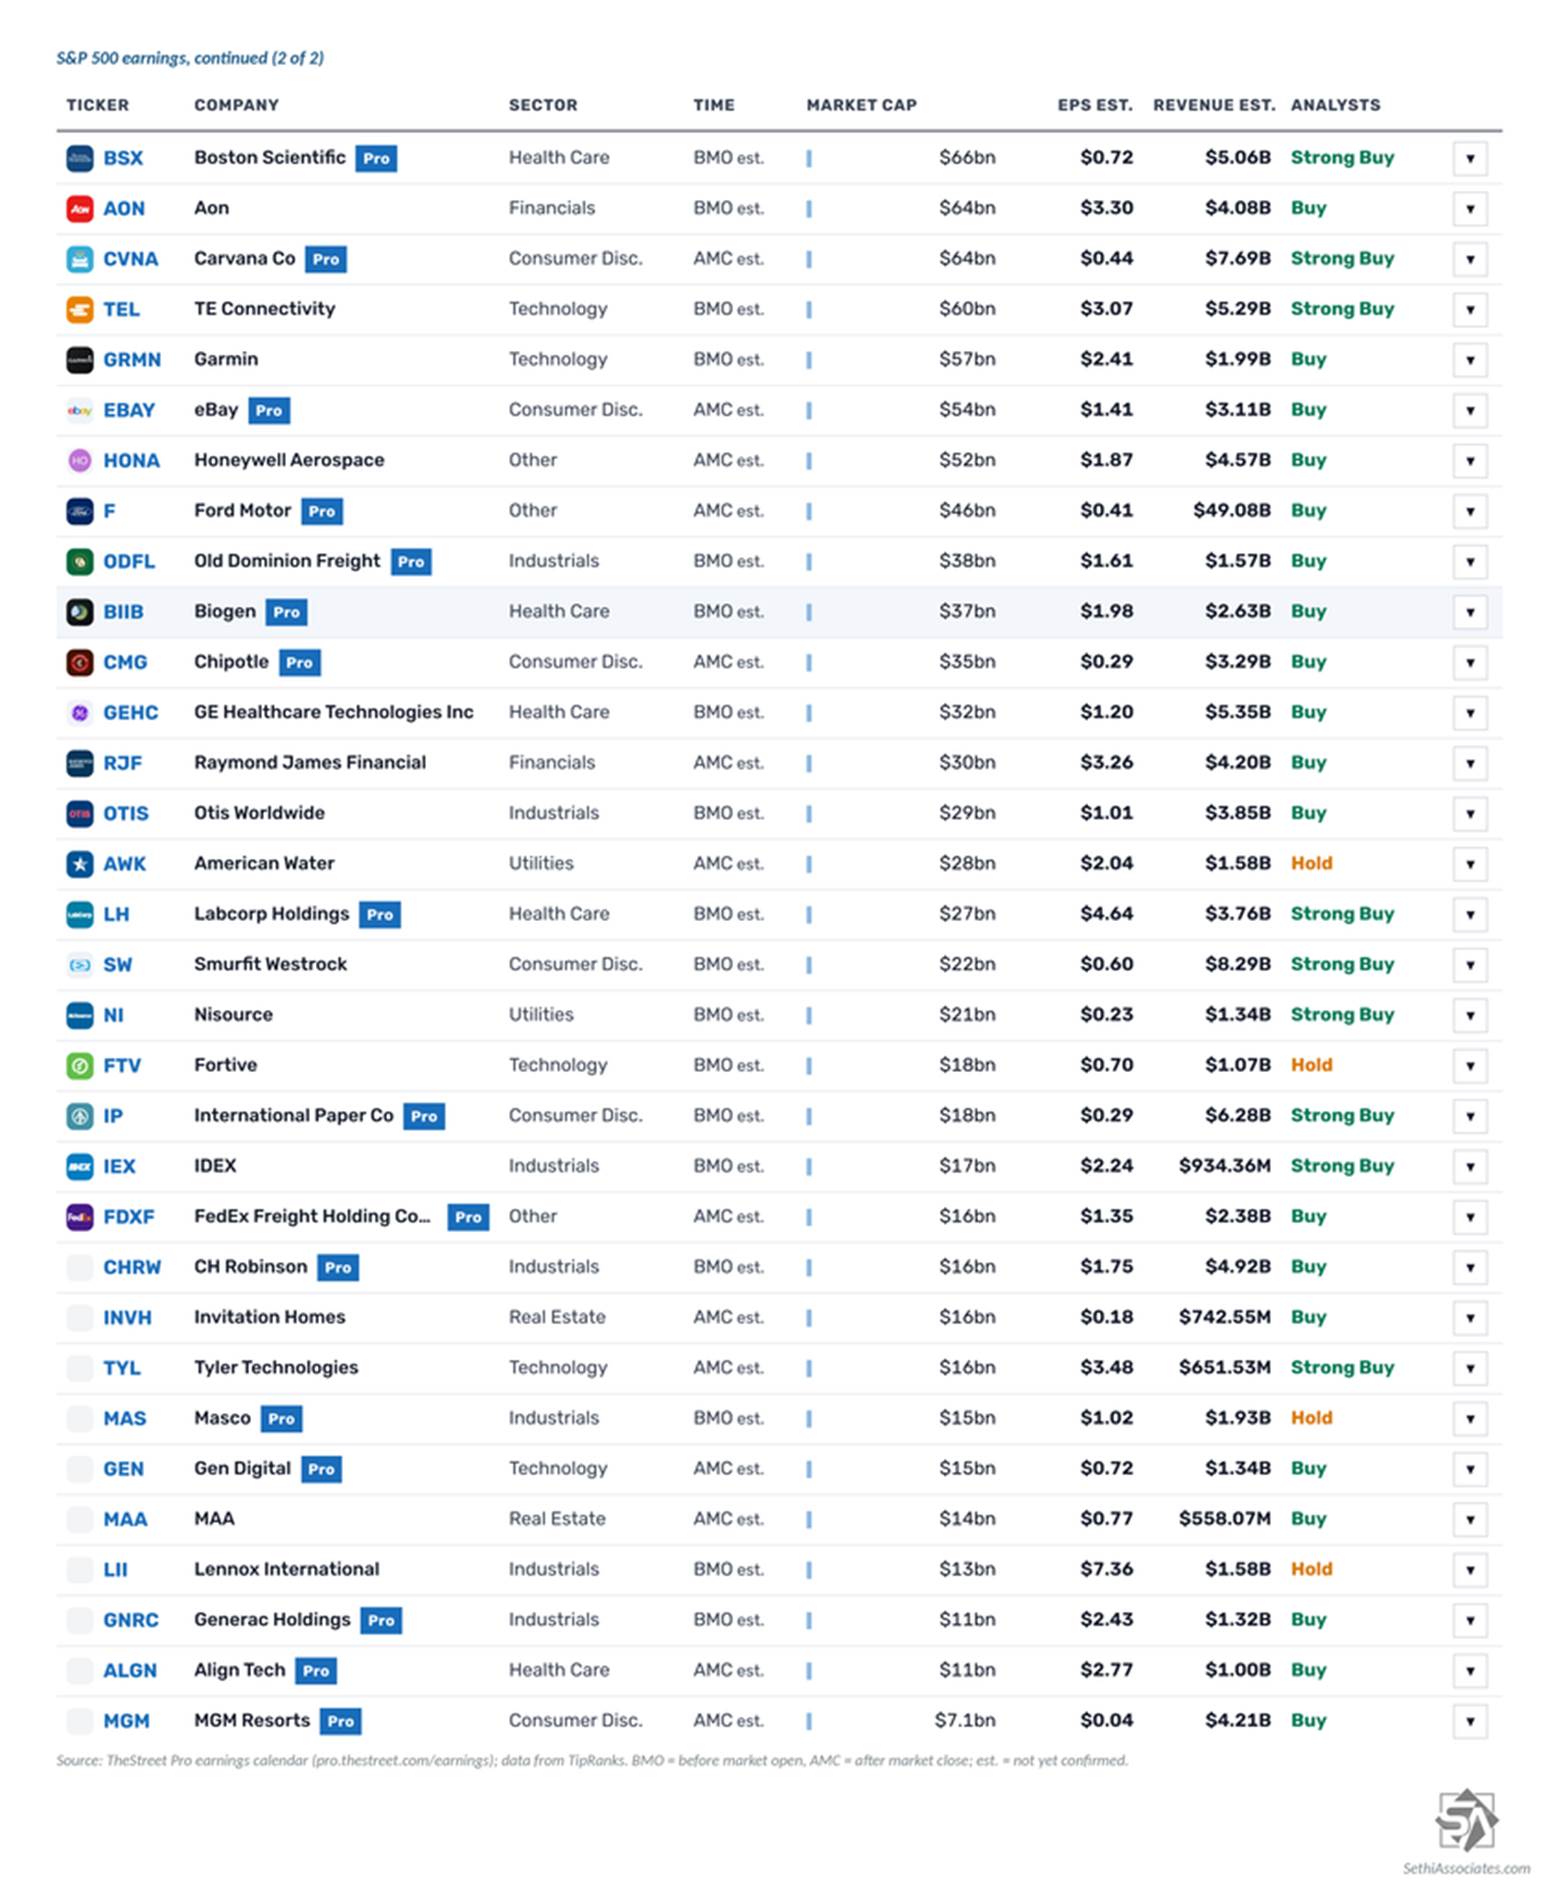
Alphabet and Microsoft lead 46 S&P 500 components reporting, nine of them with market caps over $100B:
Before the open: GE Vernova ($GEV), Amphenol ($APH), ADP ($ADP), Phillips 66 ($PSX), Vertiv ($VRT), American Electric Power ($AEP), Boston Scientific ($BSX), Aon ($AON), TE Connectivity ($TEL), Garmin ($GRMN), Old Dominion Freight Line ($ODFL), Biogen ($BIIB), GE HealthCare ($GEHC), Otis Worldwide ($OTIS), Labcorp ($LH), Smurfit Westrock ($SW), NiSource ($NI), Fortive ($FTV), International Paper ($IP), IDEX ($IEX), C.H. Robinson ($CHRW), Masco ($MAS), Lennox International ($LII) and Generac ($GNRC)
After the close: Alphabet ($GOOGL), Microsoft ($MSFT), KLA ($KLAC), ServiceNow ($NOW), T-Mobile ($TMUS), Equinix ($EQIX), O’Reilly Automotive ($ORLY), FedEx ($FDX), Carvana ($CVNA), eBay ($EBAY), Honeywell Aerospace ($HONA), Ford ($F), Chipotle ($CMG), Raymond James ($RJF), American Water Works ($AWK), FedEx Freight ($FDXF), Invitation Homes ($INVH), Tyler Technologies ($TYL), Gen Digital ($GEN), MAA ($MAA), Align Technology ($ALGN) and MGM Resorts ($MGM)
Ex-US highlights include decisions from central banks in Canada and New Zealand, Germany November GfK consumer confidence, France Q3 total jobseekers, Italy August industrial sales and September PPI, and Australia September CPI.
A wave of AI-related deals sent semiconductor shares soaring, helping the Nasdaq rally while investors prepared for the Fed and crucial earnings from Microsoft and Google parent Alphabet.