Jaguar’s Bold EV Gamble Could Become the Auto Industry’s Survival Strategy

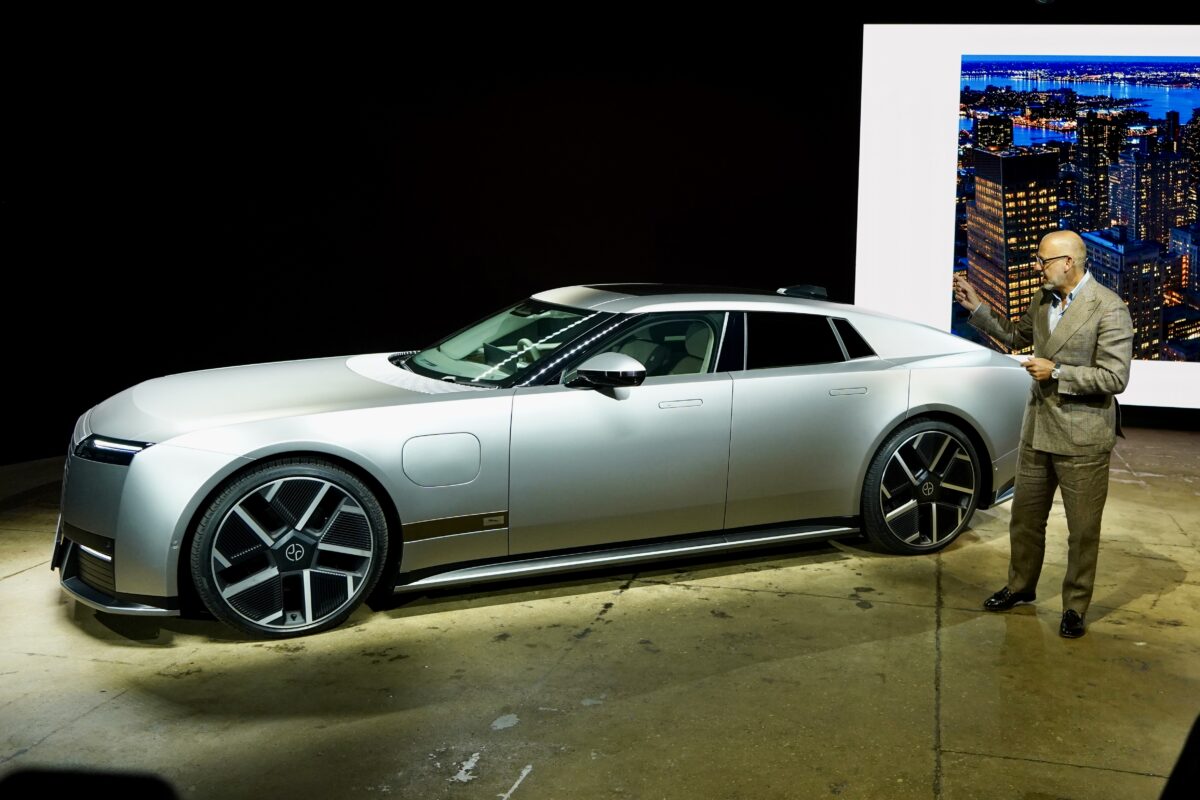
The Type 01 represents more than a product launch. It’s a test of whether luxury, differentiation, and brand identity can withstand China’s growing dominance.
The Type 01 represents more than a product launch. It’s a test of whether luxury, differentiation, and brand identity can withstand China’s growing dominance.
A wave of AI-related deals sent semiconductor shares soaring, helping the Nasdaq rally while investors prepared for the Fed and crucial earnings from Microsoft and Google parent Alphabet.
I’m getting into these two familiar oil and gas stocks amid an uncertain market.
Easing long-term yields and oil prices lifted the Russell 2000 to its best day since early August and saw 9 of 11 S&P 500 sectors higher, even as weakness in Tech dragged on the cap-weighted index.
Ryanair CEO on airline fares, OpenAI races to complete fundraising round and other headlines moving the market this morning.
– $RAPP +26% (Phase 2 RAP-219 trial met the primary and secondary endpoints in bipolar mania)
– $MSCI +5.9% (Q3 earnings and revenue topped expectations)
– $EFX +5.5% (sharply positive initial reaction to Q3 results released before the bell)
– $HTZ +5.0% (Oro Mobility secured an $80 million strategic equity investment to accelerate its standalone growth)
– $HAL +4.4% (Q3 earnings and revenue beat expectations)
– $SNY +2.4% (no clear fresh catalyst identified; unusually strong, liquid ADR move)
– $APA +1.9%, $XOM +1.2%, $CVX +1.4%, $COP +1.5%, $OXY +1.6%, $SLB +1.4% (energy names rise as crude jumps on renewed Middle East supply risks)
– $VICR +1.7% (Q3 product and royalty revenue surged and gross margin expanded sharply)
– $GM -7.6% (Q3 beat, but the full-year profit range was narrowed with the upper end cut, disappointing expectations for another guidance raise)
– $GPC -6.3% (quarter narrowly beat, but the full-year earnings range was narrowed and its upper end cut)
– $STLD -5.4% (Q3 profit missed consensus and fell below the company’s own guidance despite a revenue beat)
– $AAOI -4.6%, SKHY -4.8%, COHR -3.5%, SNDK -3.2%, MU -2.7%, LITE -2.7% (AI hardware, memory and optical names fall as renewed bubble concerns and a weak Korean AI listing pressure the trade)
– $CCK -4.3% (Q3 reaction turns negative as rising input costs offset strong beverage-can volume growth)
– $CRWV -3.9%, NBIS -4.4%, IREN -4.3% (debt-heavy AI-infrastructure names fall as borrowing-cost and funding concerns deepen)
– $GE -3.6% (Q3 beat and the outlook was raised, but shares slip in a high-expectations sell-the-news reaction)
– $BHP -3.0% (quarterly copper production fell 19% on lower grades, maintenance and operational disruptions)
– $AAPL -1.4% (Loop Capital downgrades to Hold from Buy and cuts its target on weaker iPhone shipment expectations)
Can the rally realistically continue another day? Also, when taken together, these 4 charts show a shaky situation for tens of millions of workers.
The megacap growth sectors went from worst (Friday) to first (Monday) as chipmakers snapped an eight-session losing streak, but rising Treasury yields left seven sectors, the Dow Jones Industrial Average, and the equal-weight S&P 500 lower.
Remembering Oct. 19, 1987; also an AI warning from Wall Street Journal and a check on the market’s charts.
What can we expect out of meetings between U.S. President Donald Trump and the leaders of China, Britain and Japan?