The Day Ahead: US Calendar is Light, but Tech Continues Selloff

Futures are pointing to another rough session for large cap indices with the S&P 500 indicated lower by over 1% and the Nasdaq-100 ($QQQ) 2.5%. Again non-Tech is faring better with the Russell 2000 ($RUT) indicated lower by just under a half percent.

Otherwise though catalysts are light today:

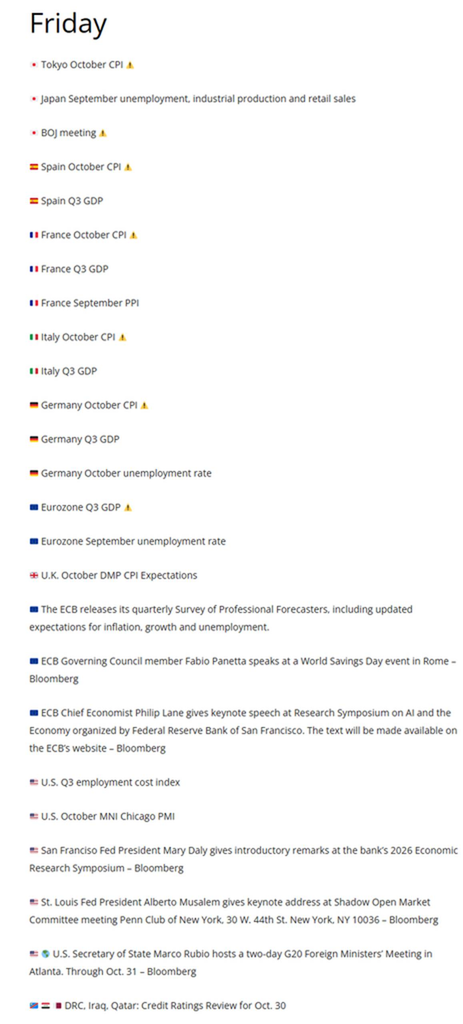
In US economic data, Friday brings us the Q3 Employment Cost Index (the Fed’s preferred wage inflation metric) and the October Chicago PMI.

Fed speakers return after Wednesday’s 10-2 decision to hold the fed funds target range at 3.75%-4%, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of a 25bp hike. San Francisco Fed President Daly gives introductory remarks at the San Francisco Fed’s Economic Research Symposium at 12pm ET, and St. Louis Fed President Musalem delivers a keynote address at the Shadow Open Market Committee meeting at 12:30pm ET.

There are no non-Bill (>1yr in maturity) US Treasury auctions.

13 S&P 500 components report, all before the open, three of them with market caps over $100bn:

Before the open: Exxon Mobil ($XOM), AbbVie ($ABBV), Chevron ($CVX), General Dynamics ($GD), Regeneron ($REGN), Colgate-Palmolive ($CL), Dominion Energy ($D), Exelon ($EXC), Kenvue ($KVUE), Cboe Global Markets ($CBOE), Church & Dwight ($CHD), LyondellBasell ($LYB) and Federal Realty ($FRT)

Outside the US, AstraZeneca ($AZN), Sanofi ($SNY) and BP ($BP) report.

Ex-US is a busier day, with highlights including a decision from the Bank of Japan, Japan October Tokyo CPI, September jobless rate, job-to-applicant ratio, retail sales, industrial production and housing starts, UK October Lloyds Business Barometer, the ECB Survey of Professional Forecasters, Germany October CPI, unemployment claims rate, Q3 GDP and September import price index, France October CPI, Q3 GDP, private sector payrolls, September consumer spending and PPI, Italy Q3 GDP and October CPI, Eurozone Q3 GDP and September unemployment rate, Spain October CPI and Canada August GDP. The G20 foreign ministers also meet in Atlanta (through October 31).
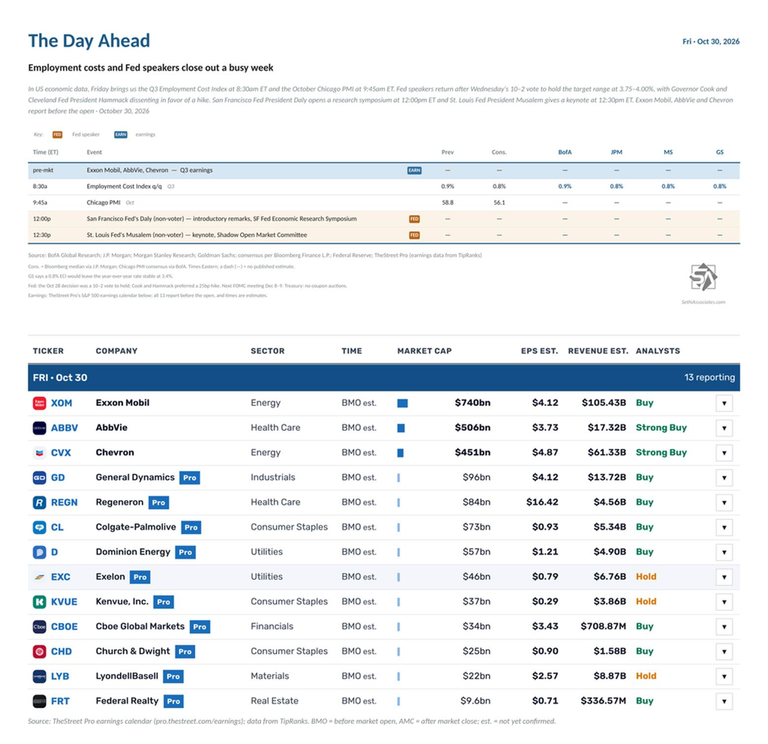
From Christophe Barraud’s international Week Ahead rundown:
Expect Small Earnings Growth From the Market’s Biggest Movers

While everyone will be focused on earnings from Alphabet ($GOOGL), Microsoft ($MSFT) and Amazon ($AMZN) this week, a Wall Street Journal analysis shows they aren’t expected to contribute enough to third-quarter S&P 500 earnings growth to get their own callout in terms of needle-movers. That’s quite a change from the second-quarter season, when their “other income” was one of the biggest sources of upside surprise.

In contrast, Nvidia ($NVDA) and Micron Technology ($MU) alone account for about a third of the nearly 30% year-over-year growth in S&P 500 third-quarter earnings. That figure blends actual results from companies that have reported with estimates for those that haven’t. Just 10 companies account for nearly two-thirds of that growth. Along with Nvidia and Micron, they are Broadcom ($AVGO), Exxon Mobil ($XOM), EchoStar ($SATS), Sandisk ($SNDK), Marathon Petroleum ($MPC), Meta Platforms ($META), Chevron ($CVX) and Valero Energy ($VLO).

Upside, Downside Movers in the Morning

Upside

– $RAPP +26% (Phase 2 RAP-219 trial met the primary and secondary endpoints in bipolar mania)

– $MSCI +5.9% (Q3 earnings and revenue topped expectations)

– $EFX +5.5% (sharply positive initial reaction to Q3 results released before the bell)

– $HTZ +5.0% (Oro Mobility secured an $80 million strategic equity investment to accelerate its standalone growth)

– $HAL +4.4% (Q3 earnings and revenue beat expectations)

– $SNY +2.4% (no clear fresh catalyst identified; unusually strong, liquid ADR move)

– $APA +1.9%, $XOM +1.2%, $CVX +1.4%, $COP +1.5%, $OXY +1.6%, $SLB +1.4% (energy names rise as crude jumps on renewed Middle East supply risks)

– $VICR +1.7% (Q3 product and royalty revenue surged and gross margin expanded sharply)

Downside

– $GM -7.6% (Q3 beat, but the full-year profit range was narrowed with the upper end cut, disappointing expectations for another guidance raise)

– $GPC -6.3% (quarter narrowly beat, but the full-year earnings range was narrowed and its upper end cut)

– $STLD -5.4% (Q3 profit missed consensus and fell below the company’s own guidance despite a revenue beat)

– $AAOI -4.6%, SKHY -4.8%, COHR -3.5%, SNDK -3.2%, MU -2.7%, LITE -2.7% (AI hardware, memory and optical names fall as renewed bubble concerns and a weak Korean AI listing pressure the trade)

– $CCK -4.3% (Q3 reaction turns negative as rising input costs offset strong beverage-can volume growth)

– $CRWV -3.9%, NBIS -4.4%, IREN -4.3% (debt-heavy AI-infrastructure names fall as borrowing-cost and funding concerns deepen)

– $GE -3.6% (Q3 beat and the outlook was raised, but shares slip in a high-expectations sell-the-news reaction)

– $BHP -3.0% (quarterly copper production fell 19% on lower grades, maintenance and operational disruptions)

– $AAPL -1.4% (Loop Capital downgrades to Hold from Buy and cuts its target on weaker iPhone shipment expectations)