New Planet Labs Price Target After SpaceX Satellite Launch

We’re moving price targets on three small-cap names amid technical developments.
We’re moving price targets on three small-cap names amid technical developments.
In addition to the well-received SpaceX ($SPCX) headlines detailed last night (SpaceX Climbs as Musk Floats Tesla Merger), some other stories are boosting Tech shares this morning:
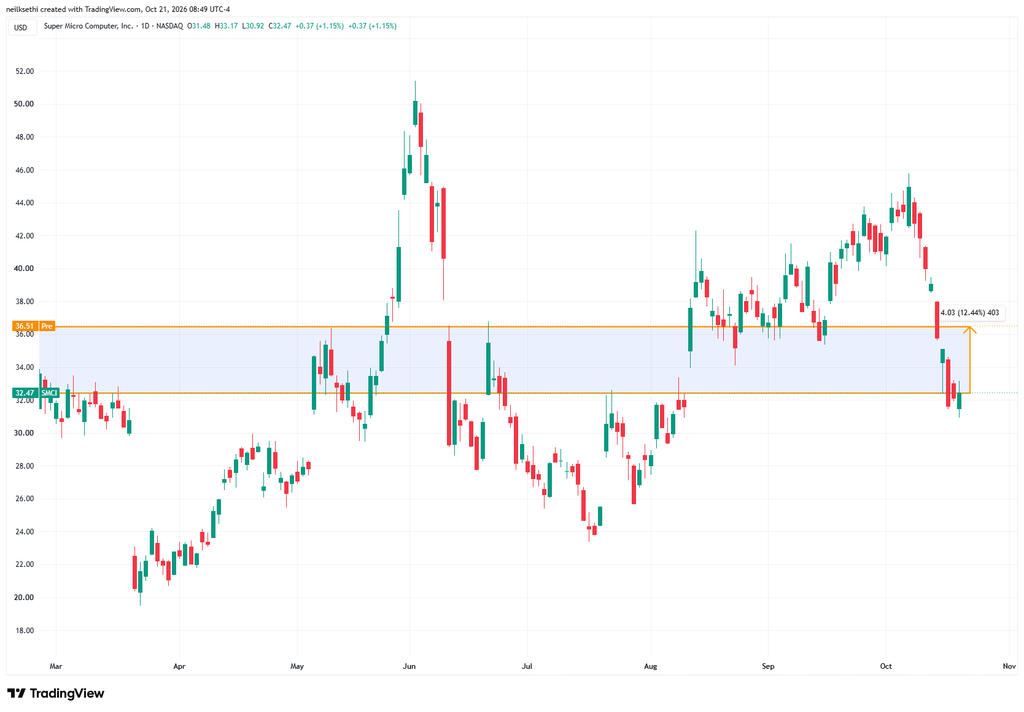
Shares of server maker Super Micro Computer ($SMCI) are up over 12% premarket after the firm released preliminary quarterly numbers for the period ending September 30, saying it expects revenue of $18.5 billion to $19.5 billion for the quarter. That compares with its earlier forecast of $14.5 billion to $15.5 billion and an average analyst estimate of about $15 billion. The company also raised its gross margin forecast to 12% to 12.5%, from 10.4% to 10.8%
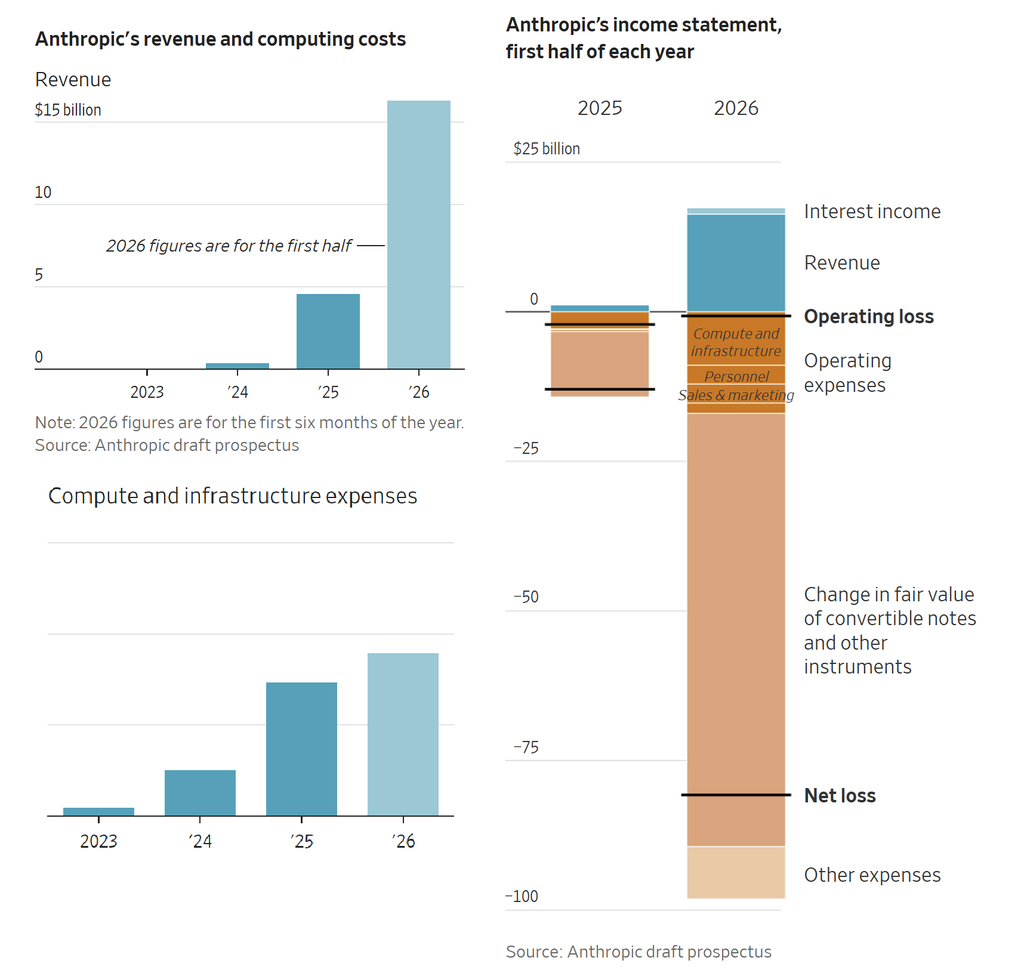
In addition, the Wall Street Journal is reporting that Anthropic’s draft prospectus signals coming spending on computer and power of as much as $750 billion in coming years, with $111 billion on contracts with Alphabet’s Google Cloud ($GOOGL), $110 billion with Amazon Web Services ($AMZN) and $31 billion with Microsoft ($MSFT) “regardless of actual usage.”
Anthropic also agreed to spend up to $86 billion renting Nvidia ($NVDA) chips from smaller AI cloud providers Nscale and Lambda.
And sales are growing at a blistering pace. The Journal reported revenues had grown to $16.3 billion in the six months ended June 30, up from $1.1 billion in the year-earlier period. That outpaced the nearly $9 billion on computing capacity and infrastructure, up from $2.3 billion.
Still it recorded a net loss of $80.7 billion, the vast majority ($72 billion) “tied to changes in the value of convertible notes and other instruments the company issued to raise funding.”
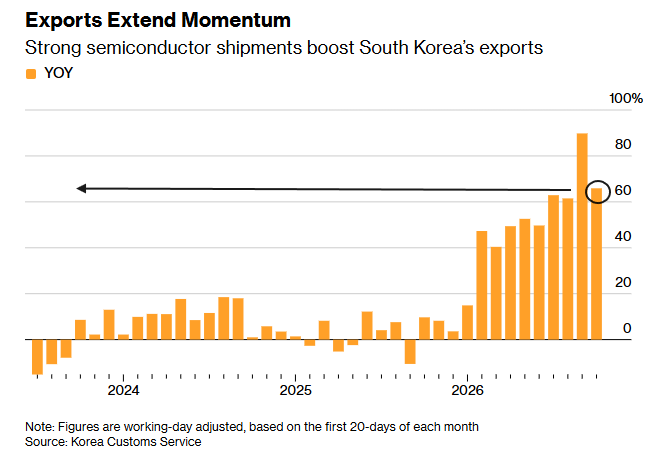
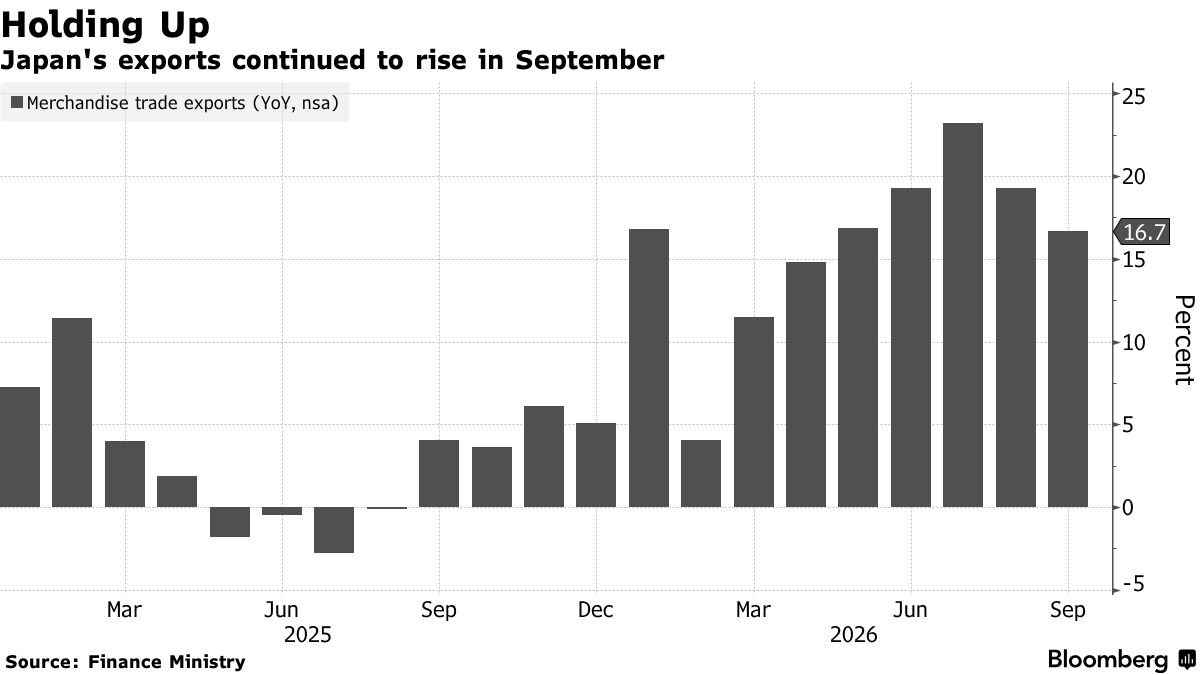
And finally, several Asian countries with large tech exposure (South Korea, Japan, Taiwan, etc.) are reporting strong export numbers led by semiconductor and other Tech shipments.
– $SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)
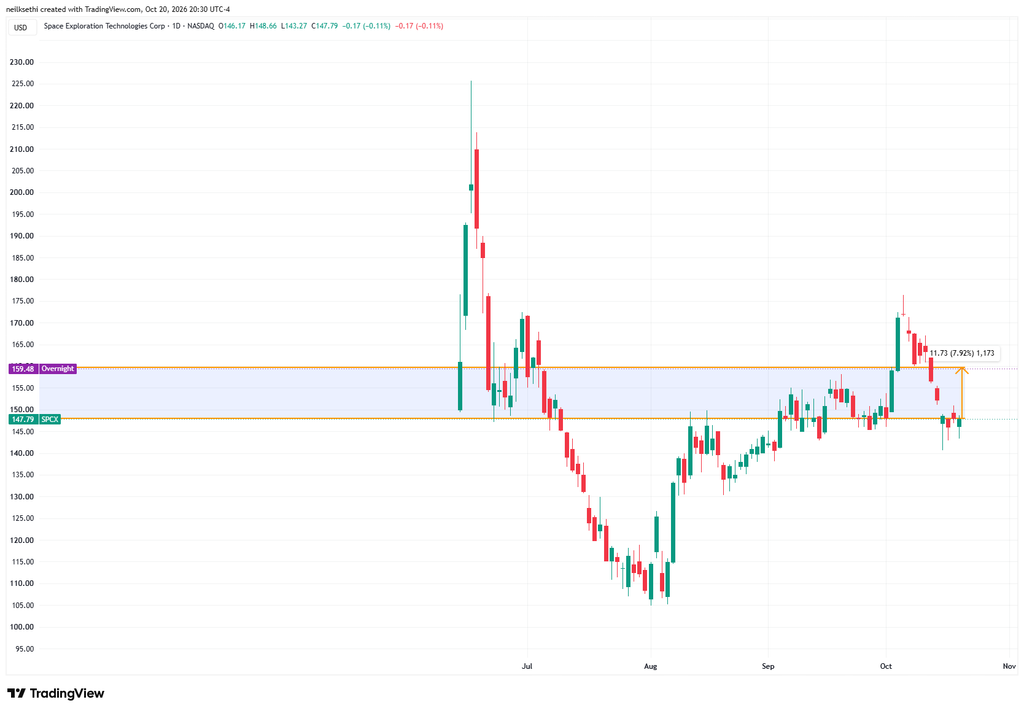
– $SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)
– $CRDO +7.2%, $VRT +6.7%, $DELL +6.9%, $LITE +5.6%, $HPE +5.0%, $COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)
– $WDC +4.0%, $SKHY +3.7%, $SNDK +3.7%, $STX +3.6%, $MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)
– $APLD +4.0% (Texas AI data-center agreement and bullish analyst action)
– $INTC +2.3%, AMD +2.1%, $NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)
– $TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)
– $TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)
– $NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)
– $ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)
– $T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)
– $DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)
– $TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)
– $ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)
Super Micro Computer crushes expectations while United Airlines and Alaska Airlines confirm energy input concerns. Those and other headlines are moving the market this morning.
The SpaceX ($SPCX) quarter beat on revenue and EBITDA across all three segments (Intelligence/AI, Space, Connectivity). The only blemish was a miss on Starlink subscriber adds, offset by better pricing. Guidance calls for revenue of $33B to $37B by Q1 FY27. Management says it expects 2 to 3 GW of compute by year-end 2026 and plans to add 10 GW in 2027, well above prior expectations, and told JPMorgan it is not considering raising equity.
Price targets:
Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
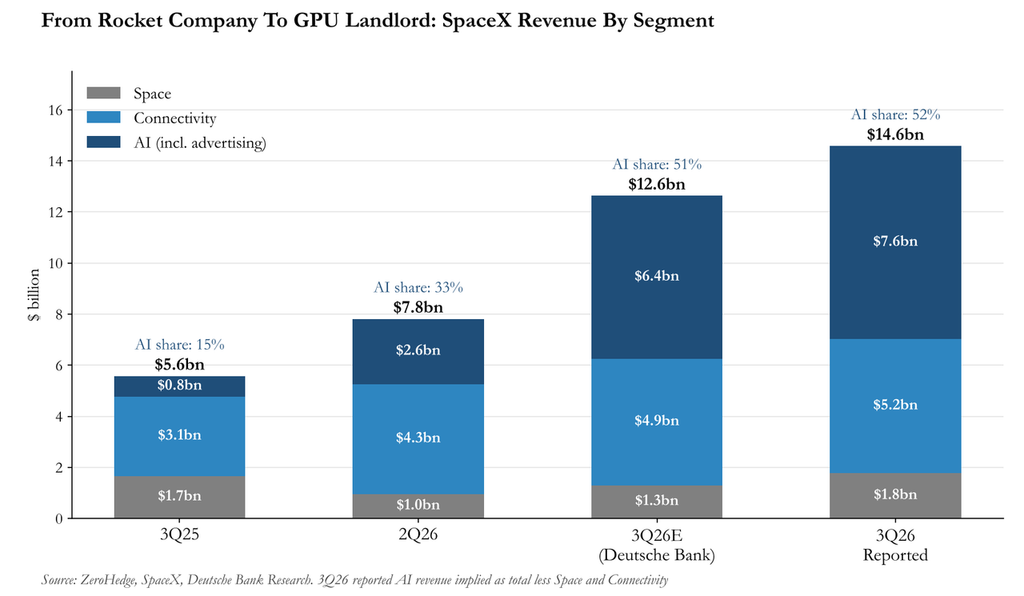
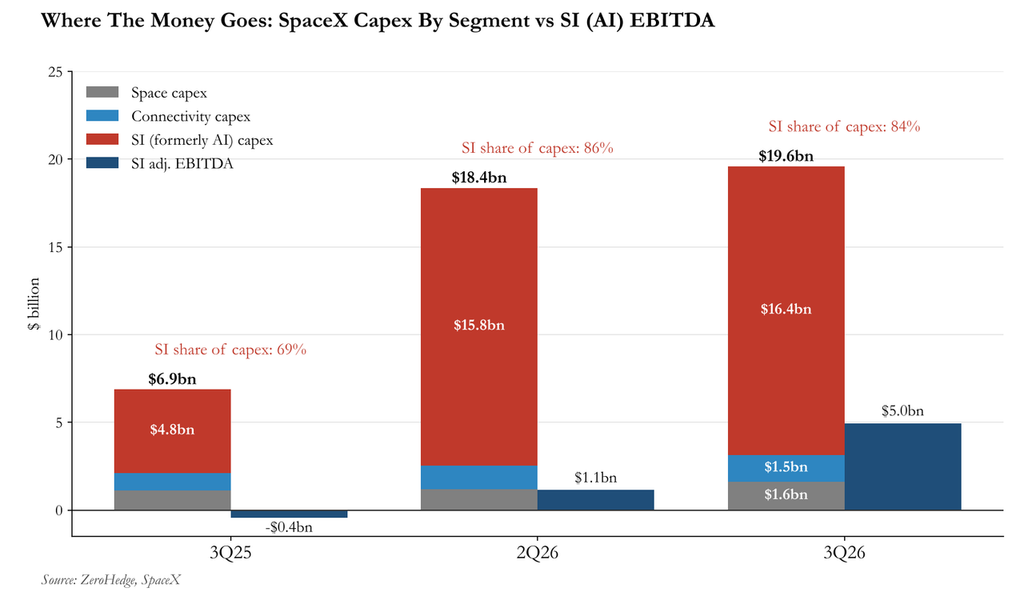
Below are two charts that speak volumes about the economics of AI.
SpaceX ($SPCX) just reported 3Q2026.
All of a sudden, AI (ergo data centers) is their biggest business. Along with that, cash and cash equivalents came in at $51.29 billion, versus an estimate of $91.2 billion. CAPEX for their AI segment was $16.4 billion versus $5 billion of EBITDA. Is this compelling?
I guess they can buy all the revenue they want; good thing the cost of financing it is so low??? Feels like double dilution is on the come here. Continued issuance to do whatever they are doing chasing WeWork landlord revenue, and dilution to potentially acquire Tesla ($TSLA), which is becoming more and more apparent.
Clearly Elon Musk wants to goose SPCX stock where he has much more of his net worth (~70%) to acquire TSLA (~25%) to hide it, on more favorable terms for SPCX (ergo himself).
This is the same trick Musk used when Tesla acquired Solar City. Hide the biz that can’t meet its promises, then to the next B.S. story.
Boy did that thing burn cash, holy heck, never seen a whiff this bad. Good thing borrowing costs are low these days. Oopsie:
In any case, at the rate AI is burning cash (and sucking down credit and equity), the 10-year Treasury will be yielding 6% in no time!
Position: None
Last quarter’s strong AI beats faded. Will it be different this time? Here’s my plan for SPCX.
Fan fave Netflix ($NFLX) materially reduced forward guidance after the close of trading — and its shares are trading -$4 (or -6%) in premarket trading.
Here is the company’s release: FINAL-Q3-26-Shareholder-Letter.pdf
From my Diary yesterday afternoon and last night on Netflix:
Repeating for emphasis, I would not bottom fish in Netflix (NFLX).
I expect in line-to-better 2Q2026 results but a possible lower forward guidance as margins are pressured.
From last month:
I would continue to avoid buying (and “bottom fishing”) in Netflix (NFLX) for the reasons I have previously mentioned:
* Netflix has nearly saturated the domestic market (as well as many other developed countries). These markets are significantly more profitable than the non developed arena.
* Future Netflix sales/profit growth will come from developing country markets that provide substantially less revenue (and income) per subscriber.
* Netflix’s original content programming has been unspectacular over the last 12 months (or more) — and existing content has suffered.
In the past I have been short NFLX, but it is no longer priced as an attractive short.
Position: None
BY Doug Kass · Sep 22, 2026, 1:50 PM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 4:09 PM EDT
Post Script:
Netflix, according to AI, was among the most recommended equities of the panelists on the “Show:” But viewers, in light of no timestamping or memorializing of recommendations, probably have no clue.
Though, as seen by my tweet above, I have stopped using X as a forum for my constructive criticism, I have a clue. Here is a recent recommendation of Netflix by one of the more particularly smug panelists seen on the Noon Show:
Trade Tracker: Steve Weiss buys more Netflix
We will likely never hear the name (Netflix) again from this particular panelist — or any of the others. As night follows day none of the panelists have modelled Netflix, spoken to management (and its competitors) or have performed any serious analysis.
Images and franchises are polished by panelists showing successful investment recommendations and not their conspicuous and frequent investment boners.
Instead the shows and panelists will likely all discuss SpaceX ($SPCX) today (whose shares are up by 6% after their EPS release)..
Position: None
SpaceX ($SPCX) shares rose nearly 8% after hours following an earnings call packed with bullish forecasts:
But perhaps the biggest news was Musk revealing that both SpaceX and Tesla ($TSLA) have formed special committees to discuss a merger. “Do I think it would be a good idea? Yes,” Musk said. “There’s a lot of merit to combining the companies,” he added. “I think it would be a good idea, but it’s really up to the special committees of both companies.” Tesla is up over 2% in the overnight session.
“There’s no question that Musk wants the merger, and he wants to get it done sooner rather than later,” Gene Munster, founder of Deepwater Asset Management, which has invested in both companies, told Bloomberg. “It was a key question on the call, and Elon said it was a good idea about three times. He’s getting people excited about it, and he wants to bump up the enthusiasm.”
https://www.bloomberg.com/news/live-blog/2026-10-20/spacex-third-quarter-earnings-live-coverage
https://www.wsj.com/livecoverage/stock-market-today-dow-sp-500-nasdaq-10-20-2026