Alphabet’s Record Plunge Drags Down Tech as the Rest of the Market Rallies

Over 400 of the S&P 500’s components were higher even as the index ended lower and the Russell 2000 gained for a fourth day while Amazon and Intel dropped after hours
Over 400 of the S&P 500’s components were higher even as the index ended lower and the Russell 2000 gained for a fourth day while Amazon and Intel dropped after hours
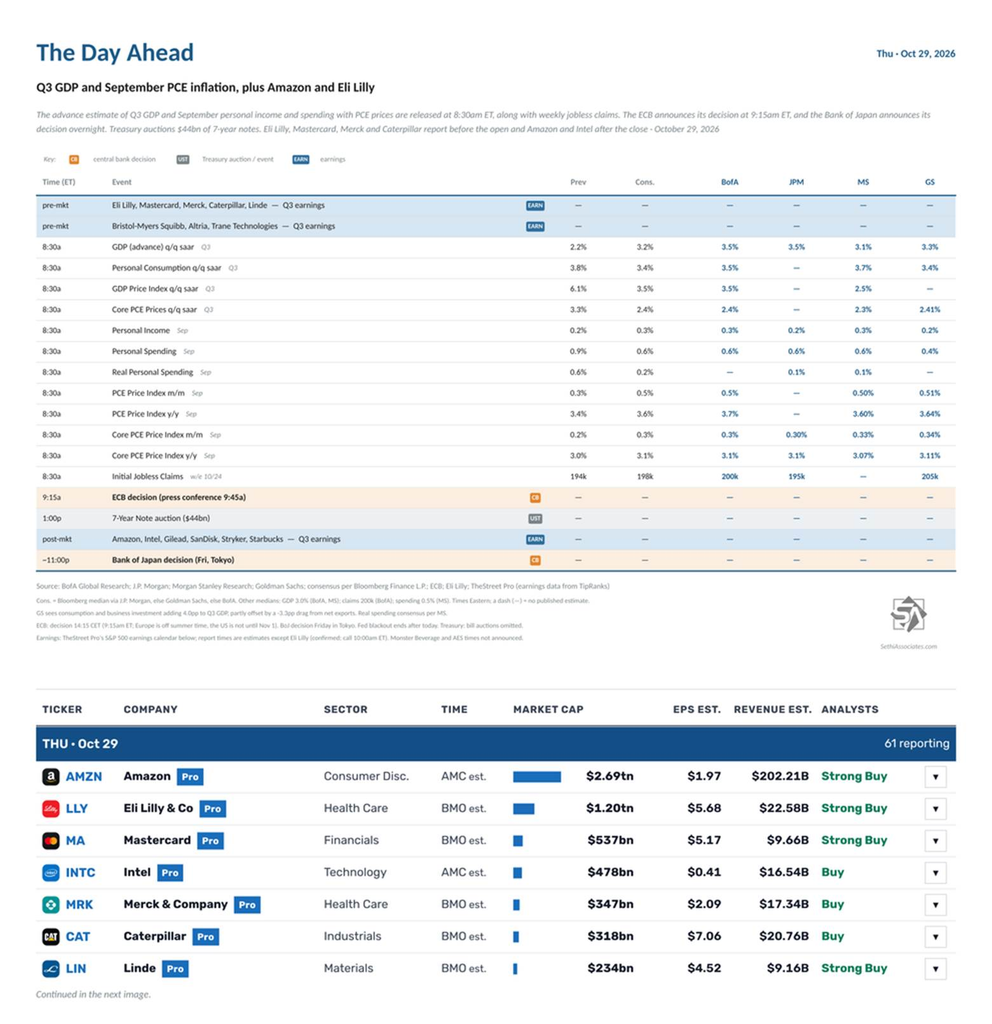
US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.
The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.
The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.
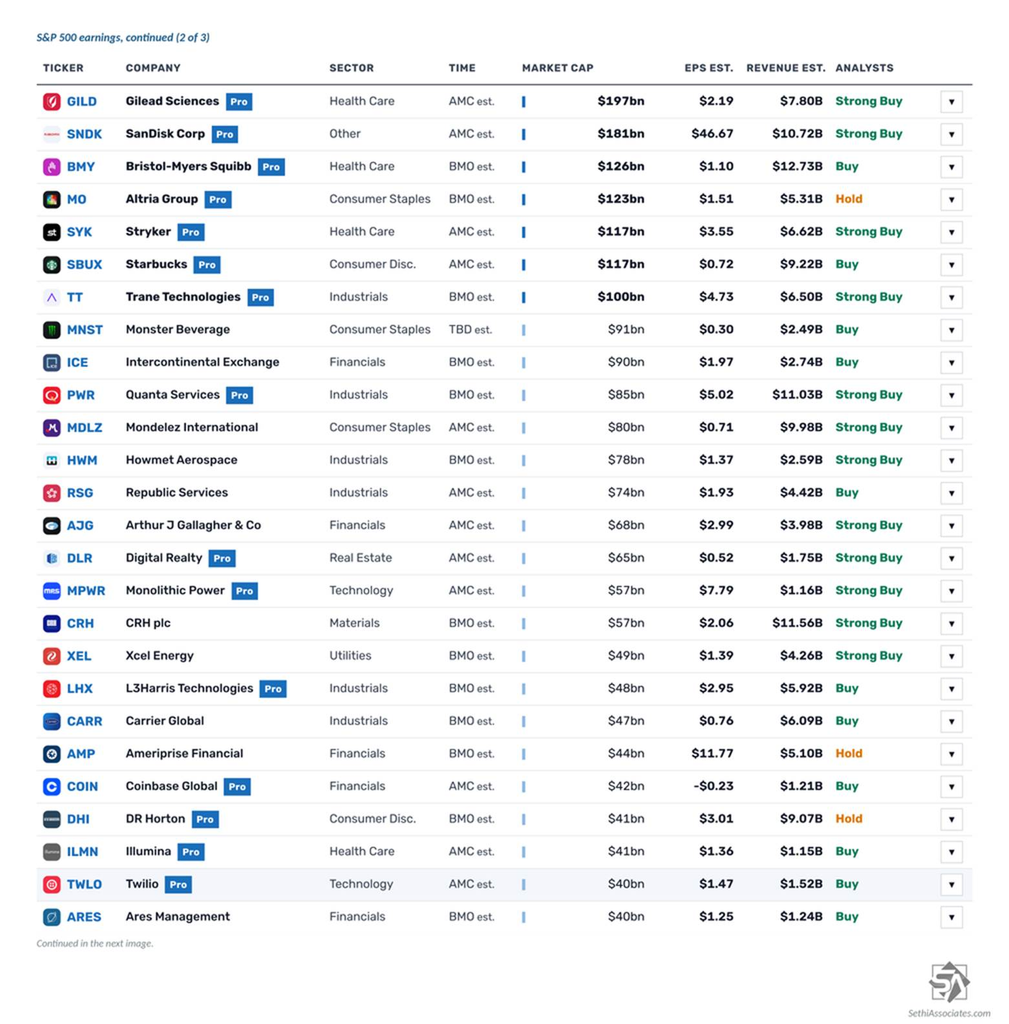
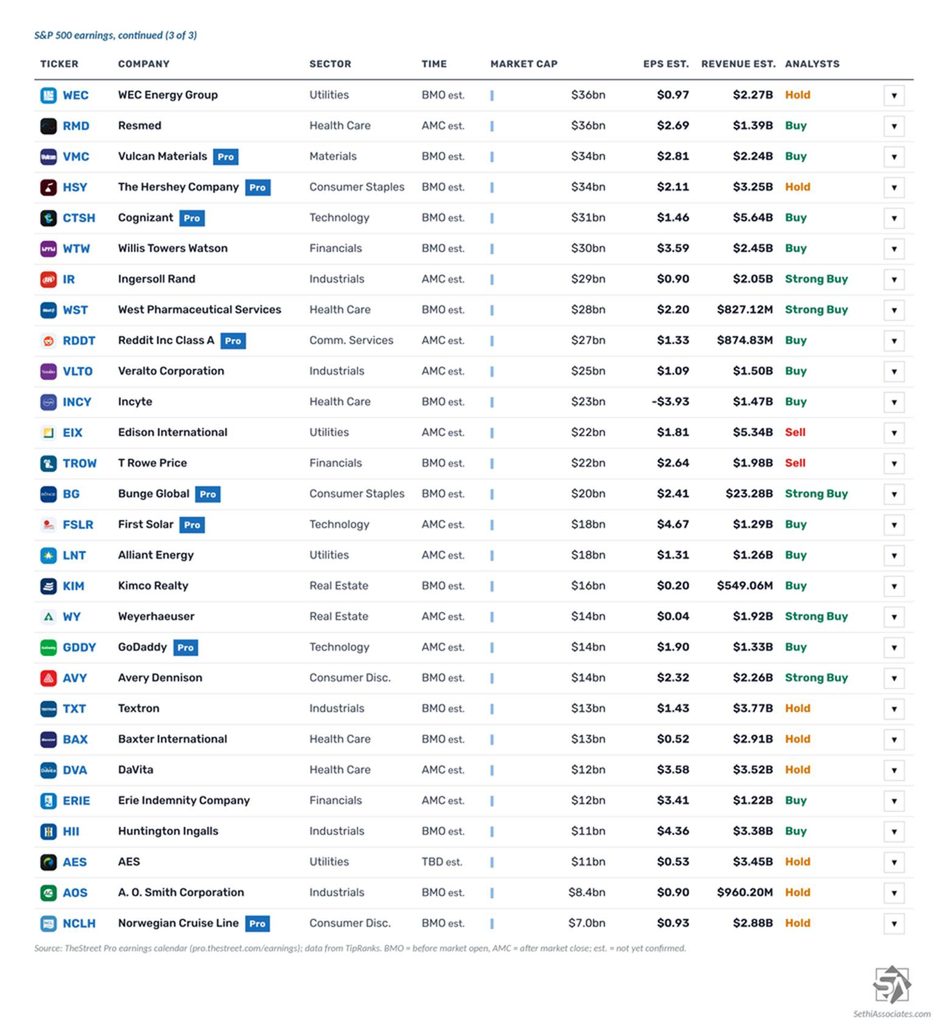
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:
Before the open: Eli Lilly ($LLY), Mastercard ($MA), Merck ($MRK), Caterpillar ($CAT), Linde ($LIN), Bristol Myers Squibb ($BMY), Altria ($MO), Trane Technologies ($TT), Intercontinental Exchange ($ICE), Quanta Services ($PWR), Howmet Aerospace ($HWM), CRH ($CRH), Xcel Energy ($XEL), L3Harris ($LHX), Carrier ($CARR), Ameriprise ($AMP), D.R. Horton ($DHI), Ares Management ($ARES), WEC Energy ($WEC), Vulcan Materials ($VMC), Hershey ($HSY), Cognizant ($CTSH), WTW ($WTW), West Pharmaceutical ($WST), Incyte ($INCY), T. Rowe Price ($TROW), Bunge ($BG), Kimco Realty ($KIM), Avery Dennison ($AVY), Textron ($TXT), Baxter ($BAX), Huntington Ingalls ($HII), A.O. Smith ($AOS) and Norwegian Cruise Line ($NCLH)
After the close: Amazon ($AMZN), Intel ($INTC), Gilead ($GILD), SanDisk ($SNDK), Stryker ($SYK), Starbucks ($SBUX), Mondelez ($MDLZ), Republic Services ($RSG), Arthur J. Gallagher ($AJG), Digital Realty ($DLR), Monolithic Power ($MPWR), Coinbase ($COIN), Illumina ($ILMN), Twilio ($TWLO), ResMed ($RMD), Ingersoll Rand ($IR), Reddit ($RDDT), Veralto ($VLTO), Edison International ($EIX), First Solar ($FSLR), Alliant Energy ($LNT), Weyerhaeuser ($WY), GoDaddy ($GDDY), DaVita ($DVA) and Erie Indemnity ($ERIE)
Time not announced: Monster Beverage ($MNST) and AES ($AES)
Outside the US, Shell ($SHEL), TotalEnergies ($TTE) and Volkswagen ($VWAGY) report.
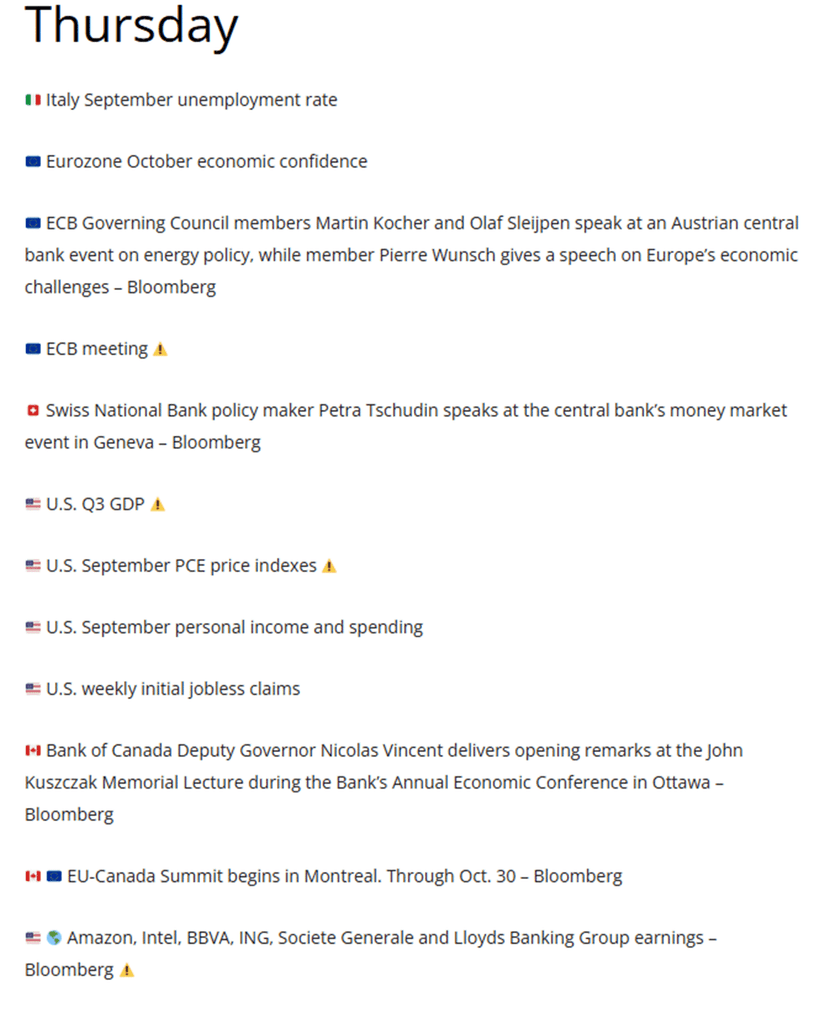
Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.
From Christophe Barraud’s international Week Ahead rundown:
The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
SK Hynix appears to be boosting the larger memory stock group.
– $ULBI +145% (agrees to be acquired for $16.00 a share in cash)
– $BOOM +21% (Q3 sales and adjusted EBITDA exceeded the high end of guidance as backlog and cash flow strengthened)
– $AXGN +16% (Q3 beat and full-year revenue guidance was raised)
– $VRT +16% (Q3 organic orders more than doubled and full-year sales guidance was raised by $650 million)
– $UCTT +15% (Q3 results and outlook drove a sharp upside reaction)
– $LUNG +12% (Q3 results and outlook drove a sharp upside reaction)
– $GEHC +9.7% (Q3 beat, full-year EPS and free-cash-flow guidance was raised, and a $945 million acquisition was announced)
– $FLEX +9.5% (fiscal Q2 beat and the full-year outlook was raised)
– $LCII +7.6% (confirms an unsolicited $101-a-share cash acquisition proposal)
– $SKHY +7.5% (quarterly revenue exceeded 100 trillion won for the first time)
– $STLA +6.9% (Q3 net loss narrowed about 90% and the 2026 outlook was reaffirmed)
– $ETSY +6.6% (announces a leadership transition)
– $SNDK +4.2%, MU +3.6% (memory names rise after SKHY posted record quarterly revenue)
– $GEV +2.4% (Q3 orders surged 96%, backlog reached $197 billion, cash-flow guidance was raised and the buyback authorization doubled)
– $RAPP -23% ($350 million of stock and convertible-note offerings priced alongside a $30 million private placement)
– $ENPH -19% (Q3 revenue missed and the Q4 sales guide was roughly 20% below consensus amid weak US residential-solar demand)
– $INTA -17% (quarter beat, but the fiscal-year outlook failed to clear elevated expectations)
– $EDU -13% (fiscal Q1 results disappointed investors)
– $BSX -12% (Q3 EPS missed and Q4 and full-year profit guidance came in below consensus)
– $LOGI -12% (holiday-quarter sales guidance called for a decline and included a $70 million–$80 million supplier-incident hit)
– $SEDG -8.7% (solar-equipment sympathy decline following ENPH’s weak demand commentary and Q4 guide)
– $NXPI -8.1% (Q3 beat, but the Q4 guide was only roughly in line and fell short of elevated expectations)
– $FFIV -7.6% (Q4 beat, but fiscal 2027 growth guidance disappointed and operating margins contracted)
– $HOOD -6.4% (revenue missed as crypto revenue fell 55%, outweighing an EPS beat and record total revenue)
– $GSK -5.8% (headline Q3 beat was offset by weak vaccine sales, soft new-product performance and unchanged guidance)
– $LII -4.7% (Q3 profit fell, segment margin contracted 240 basis points and the full-year EPS outlook disappointed)
– $STX -2.5% (fiscal Q1 results prompted a modest sell-the-news reaction)
– $V -1.7% (fiscal Q4 earnings and revenue missed forecasts despite healthy payment-volume growth and a 16% dividend increase)
While everyone will be focused on earnings from Alphabet ($GOOGL), Microsoft ($MSFT) and Amazon ($AMZN) this week, a Wall Street Journal analysis shows they aren’t expected to contribute enough to third-quarter S&P 500 earnings growth to get their own callout in terms of needle-movers. That’s quite a change from the second-quarter season, when their “other income” was one of the biggest sources of upside surprise.
In contrast, Nvidia ($NVDA) and Micron Technology ($MU) alone account for about a third of the nearly 30% year-over-year growth in S&P 500 third-quarter earnings. That figure blends actual results from companies that have reported with estimates for those that haven’t. Just 10 companies account for nearly two-thirds of that growth. Along with Nvidia and Micron, they are Broadcom ($AVGO), Exxon Mobil ($XOM), EchoStar ($SATS), Sandisk ($SNDK), Marathon Petroleum ($MPC), Meta Platforms ($META), Chevron ($CVX) and Valero Energy ($VLO).

Brent topped $116 and stocks pulled back on fears of renewed U.S.-Iran hostilities after the midterm elections. For the week, small caps led with the Russell 2000 up 2% while the S&P 500 and Nasdaq slipped.
– $SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)
– $SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)
– $CRDO +7.2%, $VRT +6.7%, $DELL +6.9%, $LITE +5.6%, $HPE +5.0%, $COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)
– $WDC +4.0%, $SKHY +3.7%, $SNDK +3.7%, $STX +3.6%, $MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)
– $APLD +4.0% (Texas AI data-center agreement and bullish analyst action)
– $INTC +2.3%, AMD +2.1%, $NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)
– $TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)
– $TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)
– $NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)
– $ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)
– $T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)
– $DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)
– $TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)
– $ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)
Some of the biggest names in tech are underperforming the market, which is still in consolidation mode.
The megacap growth sectors went from worst (Friday) to first (Monday) as chipmakers snapped an eight-session losing streak, but rising Treasury yields left seven sectors, the Dow Jones Industrial Average, and the equal-weight S&P 500 lower.