Apple Price Target Cuts, Palantir Earnings Reaction: 8 Key Items Shaping the Stock Market Tuesday

Eaton’s earnings, S&P 500 and Nasdaq Composite levels and other headlines are moving the market this morning.
Eaton’s earnings, S&P 500 and Nasdaq Composite levels and other headlines are moving the market this morning.
– $BLZE +34% (Q3 beat as B2 cloud-storage growth accelerated to 47% and large AI and core-workload agreements expanded)
– $AEIS +12% (record Q3 and strong Q4 guide on semiconductor and data-center power demand)
– $LSCC +11% (record Q3 beat and strong Q4 and 2027 outlook on AI-data-center FPGA demand)
– $GRAB +10% (Q3 growth and margins beat as revenue and EBITDA guidance was raised and buybacks continued)
– $RVTY +10% (Q3 beat and FY outlook was raised)
– $FISV +9.8% (reaffirmed outlook, doubled its savings target to $1B and set a $500M Q4 buyback despite flat organic revenue)
– $FN +9.2% (record revenue beat and strong Q2 guide on broad optical-program ramps)
– $NBIX +8.0% (Q3 beat and INGREZZA sales outlook was raised)
– $BE +6.9% (MOU targets at least 1 GW of California fuel-cell power paired with carbon capture)
– $JD +4.7% (China market-support measures and expected EU clearance for the Ceconomy acquisition)
– $CE +4.6% (Q3 profit beat and FY earnings and free-cash-flow outlook was raised)
– $MDGL +4.4% (Rezdiffra sales rose 50% and the company reached its first quarterly profit)
– $MCHP +3.4%, $SNDK +5.8%, $MU +4.7%, $LRCX +5.0%, $INTC +4.6%, $AMD +4.4% (chip names rebound from the recent selloff as fresh results reinforce AI-infrastructure demand)
– $ZBRA -17% (quarter beat and outlook raised, but adjusted operating margin contracted sharply and results fell short of elevated expectations)
– $SHOP -15% (Q3 cleared the published consensus bar, but Q4 low-30s revenue and high-20s gross-profit growth disappointed elevated expectations)
– $DT -14% (quarter beat, but acquisition dilution drove cuts to the full-year EPS and margin outlook)
– $IT -6.2% (profit beat and guidance raise, but contract-value growth remained soft at 2.5%)
– $PLTR -4.7% (blowout quarter and guidance raise, but total contract-value growth slowed sharply, triggering a high-expectations sell-the-news reaction)
– $KMX -4.2% (strategic update targets mid-single-digit unit growth and mid-teens adjusted EPS growth through fiscal 2030, but the framework disappointed investors)
– $AAPL -3.8% (fiscal Q4 beat, but holiday-quarter gross-margin guidance disappointed on higher memory and AI costs)
– $DDOG -2.8%, $TTD -1.0%, $NOW -1.0% (high-multiple software names weaken alongside $PLTR on AI-valuation scrutiny and pre-earnings de-risking)
– $DOCN -2.0% (strong growth and revenue outlook, but the Q4 profit outlook and heavy data-center capacity spending weighed)
– $HL -1.3% (precious-metals miners fall as silver drops and gold softens)
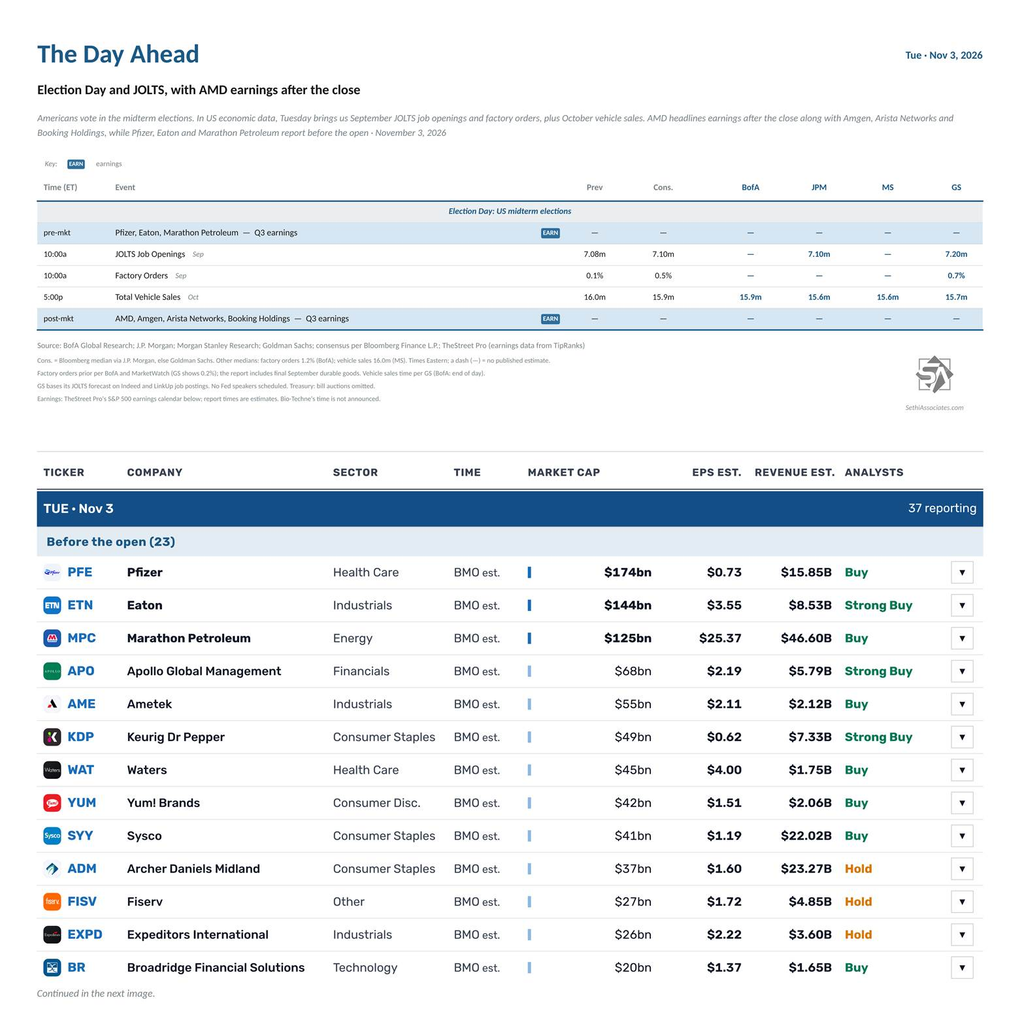
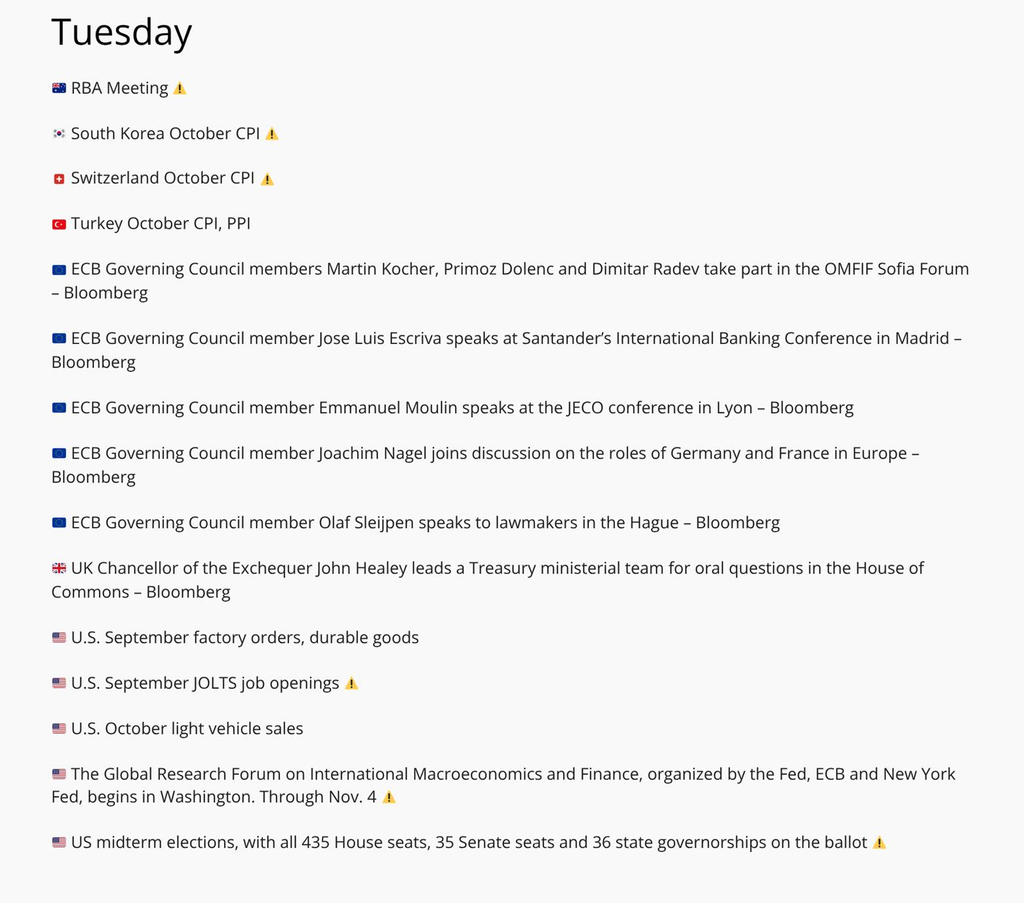
It’s Election Day, with Americans voting in the midterm elections (all 435 House seats, 35 Senate seats and 36 governorships are on the ballot).
In US economic data, Tuesday brings us September JOLTS job openings and factory orders (which include final durable goods), and October vehicle sales.
There are no Fed speakers scheduled, although the Global Research Forum on International Macroeconomics and Finance, organized by the Fed, ECB and New York Fed, begins in Washington (through November 4), so there may very well be media interviews.
There are no non-Bill (>1yr in maturity) US Treasury auctions this week.
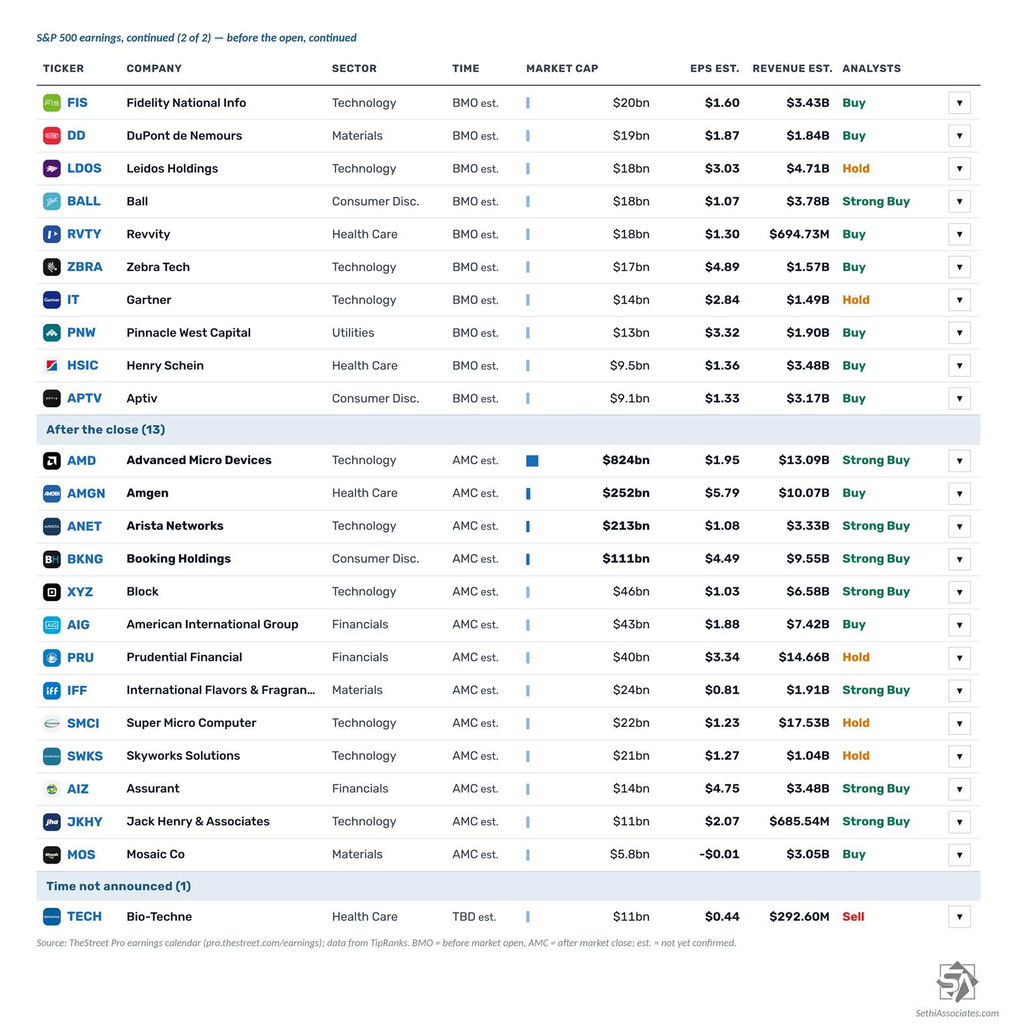
37 S&P 500 components report, seven of them with market caps over $100bn:
After the close: AMD ($AMD), Amgen ($AMGN), Arista Networks ($ANET), Booking Holdings ($BKNG), Block ($XYZ), AIG ($AIG), Prudential Financial ($PRU), International Flavors & Fragrances ($IFF), Super Micro Computer ($SMCI), Skyworks Solutions ($SWKS), Assurant ($AIZ), Jack Henry & Associates ($JKHY) and Mosaic ($MOS)
Before the open: Pfizer ($PFE), Eaton ($ETN), Marathon Petroleum ($MPC), Apollo Global Management ($APO), Ametek ($AME), Keurig Dr Pepper ($KDP), Waters ($WAT), Yum! Brands ($YUM), Sysco ($SYY), Archer-Daniels-Midland ($ADM), Fiserv ($FISV), Expeditors International ($EXPD), Broadridge Financial ($BR), Fidelity National Information Services ($FIS), DuPont ($DD), Leidos ($LDOS), Ball ($BALL), Revvity ($RVTY), Zebra Technologies ($ZBRA), Gartner ($IT), Pinnacle West ($PNW), Henry Schein ($HSIC) and Aptiv ($APTV)
Time not announced: Bio-Techne ($TECH)
Outside the S&P 500, Shopify ($SHOP), Energy Transfer ($ET), Ferrari ($RACE), Bayer ($BAYRY) and Intesa Sanpaolo ($ISNPY) report.
Ex-US highlights include the Reserve Bank of Australia’s decision (10:30pm ET Monday; Deutsche Bank expects a hold), October CPI from Switzerland, South Korea and Turkey (plus Turkey PPI), New Zealand’s Q3 labor force survey, Japan’s October monetary base and France’s September budget balance. ECB Governing Council members Kocher, Dolenc, Radev, Escriva, Moulin, Nagel and Sleijpen speak, as do the Bank of Canada’s Macklem and Rogers, and UK Chancellor of the Exchequer Healey takes oral questions in the House of Commons.
Japanese markets are closed for Culture Day.
From Christophe Barraud’s international Week Ahead rundown:
Another drawdown in Tech, following its worst month since March 2025, overshadowed six sectors advancing more than 1%.
Your AI will call their AI. Here’s the stock I’m buying for that.
September Flash PMI, Zuckerberg’s Meta Connect keynote, and other headlines are moving the market this morning.
A sixth day of gains for semiconductors drives the Nasdaq-100 to its first record since June while a fifth day of losses for crude boosted small caps
– $GRML +44% (extends the high-volume Greenland critical-minerals momentum rally)
– $VKTX +25% (positive VK2735 maintenance data showed strong weight loss and high retention with biweekly and monthly dosing)
– $VICR +8.7% (raises Q3 sequential revenue-growth guidance to more than 20% from nearly 10% on V4PD-license royalties)
– $ONON +8.0% (sets high-teens constant-currency sales growth and 22%+ EBITDA-margin targets through 2029 and authorizes a $1B buyback)
– $SHOP +5.1% (no clear fresh catalyst identified; unusually large premarket move in a highly followed stock)
– $RCL +2.4%, CCL +3.0%, NCLH +2.7% (cruise operators rise as crude drops, easing fuel-cost pressure)
– $FSLR +1.8% (rate-sensitive solar shares benefit as Treasury yields retreat)
– $CLDX -20% (positive Phase 3 CSU results trigger a sell-the-news reaction after the anticipated binary readout)
– $DAVA -13% (CFO placed on leave amid an internal accounting investigation disclosed in a 6-K)
– $LH -6.2%, DGX -6.9% (CMS proposes laboratory reimbursement cuts of up to 15% beginning in 2027)
– $VLO -2.1%, $PSX -2.0% (energy names fall as crude drops on easing geopolitical risk)
– $STX -1.4%, WDC -1.4% (storage names pull back with the semiconductor complex after the prior session’s AI-driven rally)
SOURCE: Trade The News
What to watch with SpaceX earnings, U.S munition pain point, Duke Energy’s capital plan, and other headlines are moving stocks this morning.