Upside, Downside Movers in the Morning

Upside
– $BLZE +34% (Q3 beat as B2 cloud-storage growth accelerated to 47% and large AI and core-workload agreements expanded)
– $AEIS +12% (record Q3 and strong Q4 guide on semiconductor and data-center power demand)
– $LSCC +11% (record Q3 beat and strong Q4 and 2027 outlook on AI-data-center FPGA demand)
– $GRAB +10% (Q3 growth and margins beat as revenue and EBITDA guidance was raised and buybacks continued)
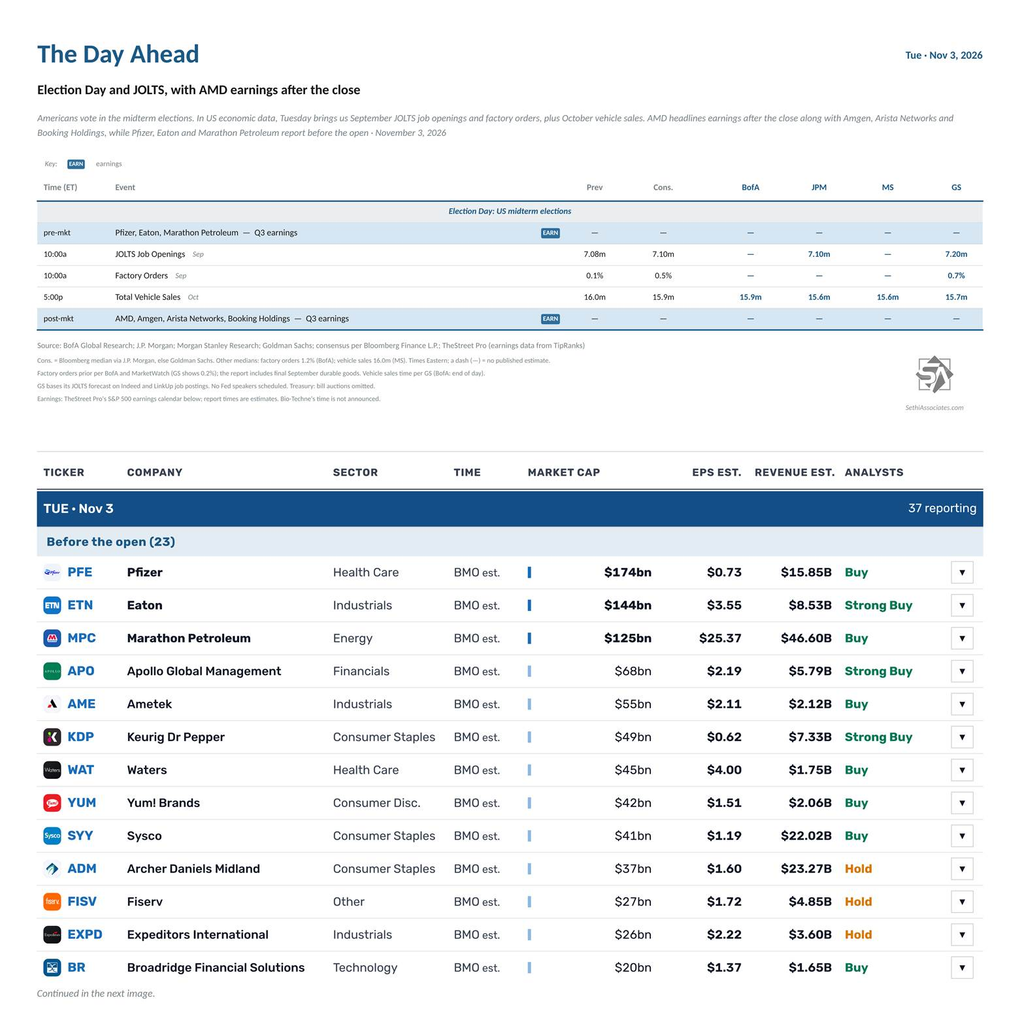
– $RVTY +10% (Q3 beat and FY outlook was raised)
– $FISV +9.8% (reaffirmed outlook, doubled its savings target to $1B and set a $500M Q4 buyback despite flat organic revenue)
– $FN +9.2% (record revenue beat and strong Q2 guide on broad optical-program ramps)
– $NBIX +8.0% (Q3 beat and INGREZZA sales outlook was raised)
– $BE +6.9% (MOU targets at least 1 GW of California fuel-cell power paired with carbon capture)
– $JD +4.7% (China market-support measures and expected EU clearance for the Ceconomy acquisition)
– $CE +4.6% (Q3 profit beat and FY earnings and free-cash-flow outlook was raised)
– $MDGL +4.4% (Rezdiffra sales rose 50% and the company reached its first quarterly profit)
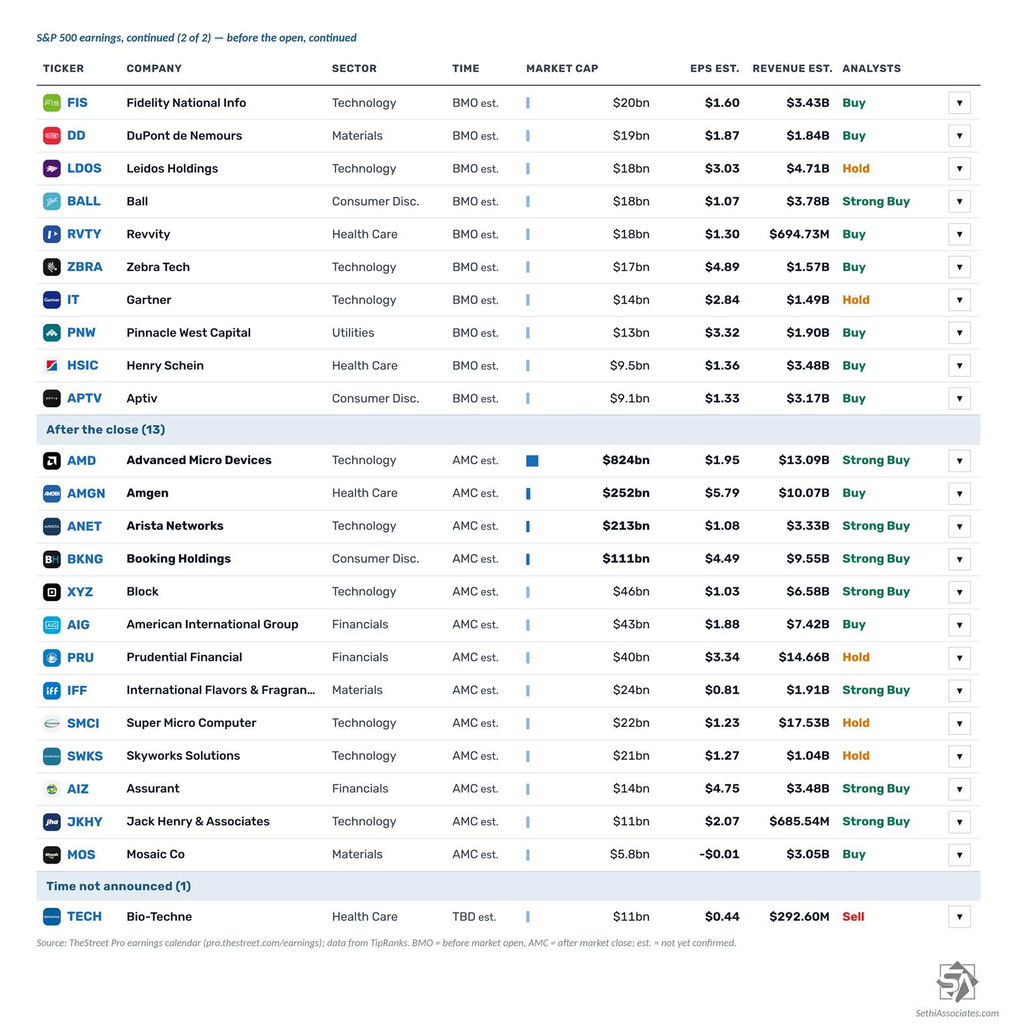
– $MCHP +3.4%, $SNDK +5.8%, $MU +4.7%, $LRCX +5.0%, $INTC +4.6%, $AMD +4.4% (chip names rebound from the recent selloff as fresh results reinforce AI-infrastructure demand)
Downside
– $ZBRA -17% (quarter beat and outlook raised, but adjusted operating margin contracted sharply and results fell short of elevated expectations)
– $SHOP -15% (Q3 cleared the published consensus bar, but Q4 low-30s revenue and high-20s gross-profit growth disappointed elevated expectations)
– $DT -14% (quarter beat, but acquisition dilution drove cuts to the full-year EPS and margin outlook)
– $IT -6.2% (profit beat and guidance raise, but contract-value growth remained soft at 2.5%)
– $PLTR -4.7% (blowout quarter and guidance raise, but total contract-value growth slowed sharply, triggering a high-expectations sell-the-news reaction)
– $KMX -4.2% (strategic update targets mid-single-digit unit growth and mid-teens adjusted EPS growth through fiscal 2030, but the framework disappointed investors)
– $AAPL -3.8% (fiscal Q4 beat, but holiday-quarter gross-margin guidance disappointed on higher memory and AI costs)
– $DDOG -2.8%, $TTD -1.0%, $NOW -1.0% (high-multiple software names weaken alongside $PLTR on AI-valuation scrutiny and pre-earnings de-risking)
– $DOCN -2.0% (strong growth and revenue outlook, but the Q4 profit outlook and heavy data-center capacity spending weighed)
– $HL -1.3% (precious-metals miners fall as silver drops and gold softens)