Mondelez Up, Intel Down: Upside, Downside Movers in the Morning

Upside
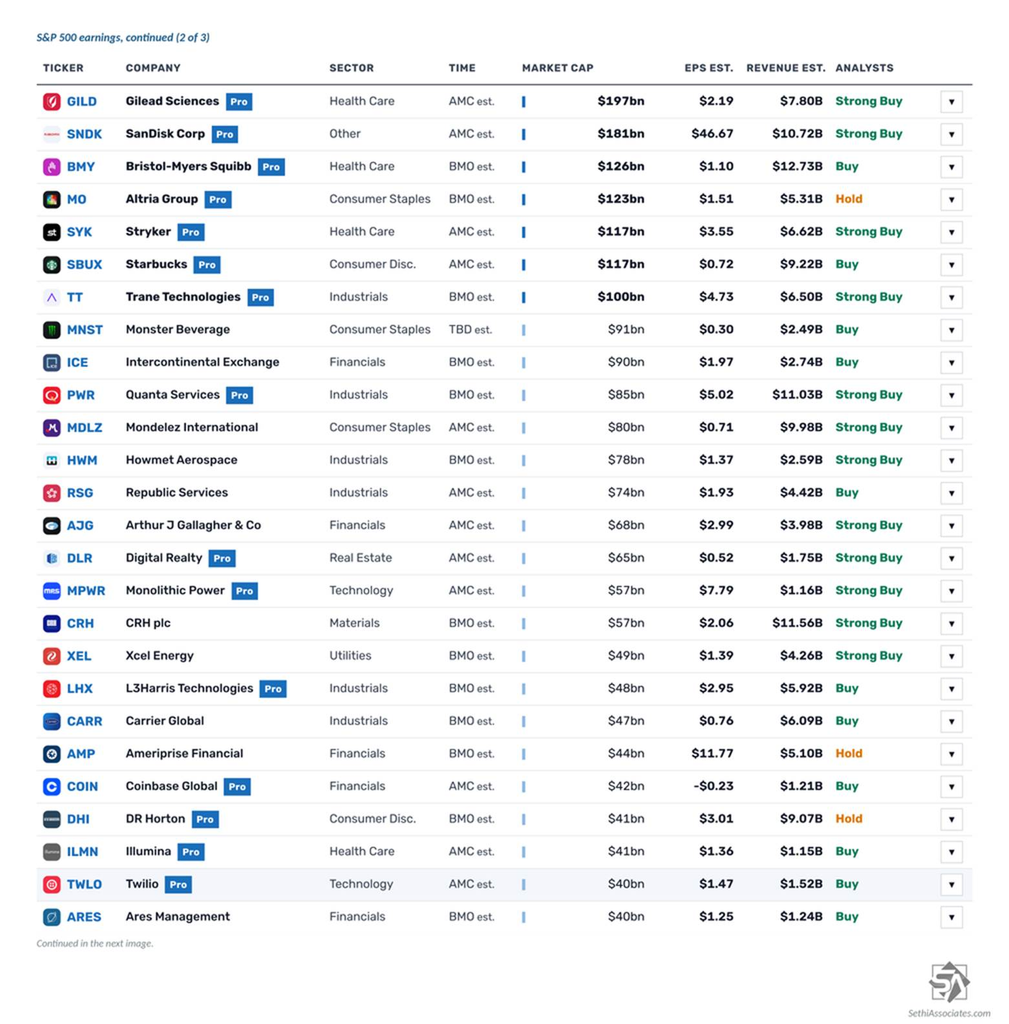
– $REGN +6.9% (Q3 profit and revenue materially topped expectations)
– $BTSG +6.4% (Q3 beat and full-year revenue and adjusted EBITDA guidance raised)
– $MDLZ +6.4% (profit beat, volume-led growth and upbeat margin and 2027 commentary)
– $RIVN +6.4% (Q3 beat and 2026 delivery outlook raised)
– $AZN +5.9% (Q3 revenue and profit beat on strong oncology growth; FY guidance reaffirmed)
– $MICC +5.4% (Q3 update showed double-digit growth at core brands and more than 30% Yasso growth)
– $GILD +5.1% (Q3 beat and product-sales outlook raised on strong HIV growth)
– $CL +5.0% (Q3 beat, volume and gross margin improved and FY profit guidance was raised)
– $TAK +4.4% (first-half profit beat and FY outlook upgraded, primarily reflecting FX benefits)
– $FDXF +3.9% (inaugural standalone results beat and adjusted margin outlook was raised)
– $ICE +3.7% (extends post-earnings gains after record Q3 results and a higher recurring-revenue outlook)
– $SNY +3.6% (Q3 delivered double-digit sales and profit growth and FY guidance was raised)
– $GD +3.4% (Q3 beat with broad segment growth and robust bookings)
– $DXCM +3.0% (Q3 beat with margin expansion and higher FY revenue and profitability guidance)
– $EXC +2.5% (Q3 beat and FY guidance narrowed while long-term EPS growth was affirmed near the top of its range)
Downside
– $ATEC -32% (Q3 missed as weaker biologics revenue drove cuts to the FY revenue, EBITDA and free-cash-flow outlooks)
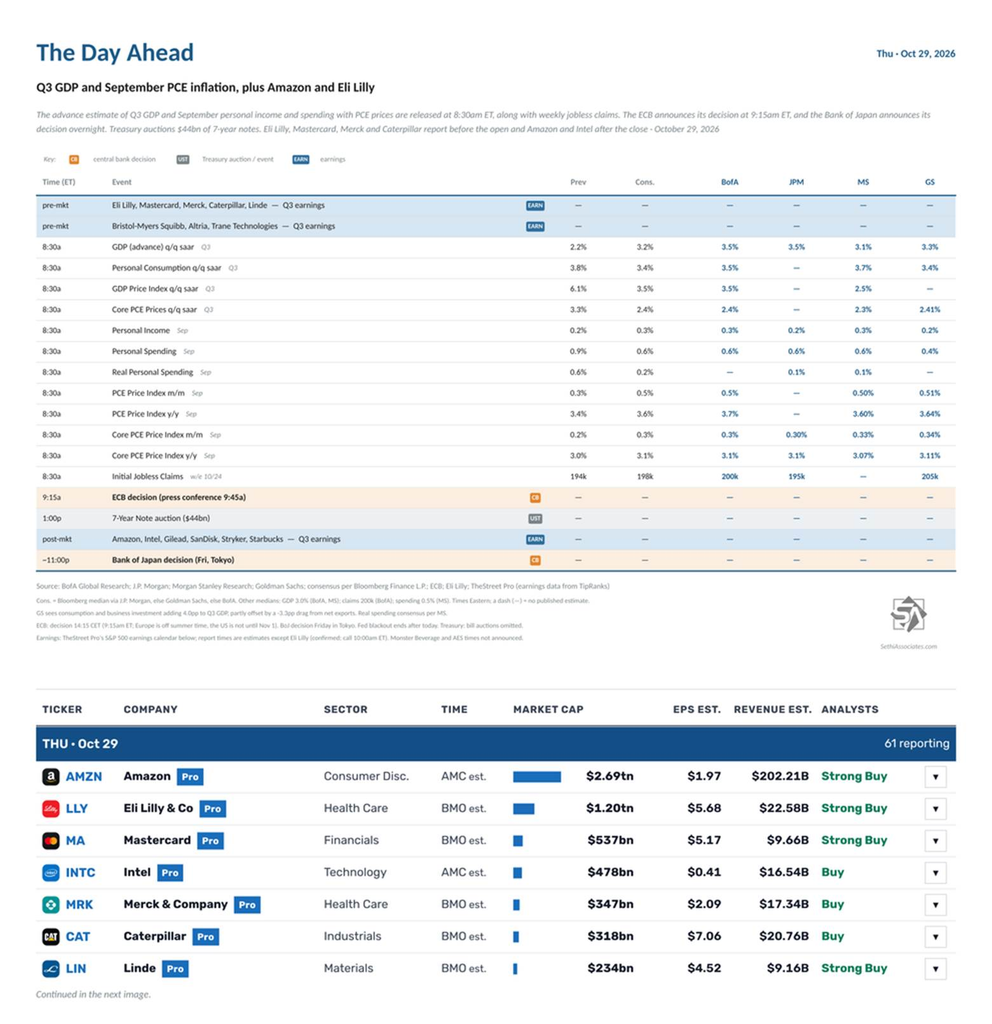
– $INTC -25% (Q4 revenue, profit and gross-margin guidance fell well short as the PC slowdown is expected to persist into 2027)
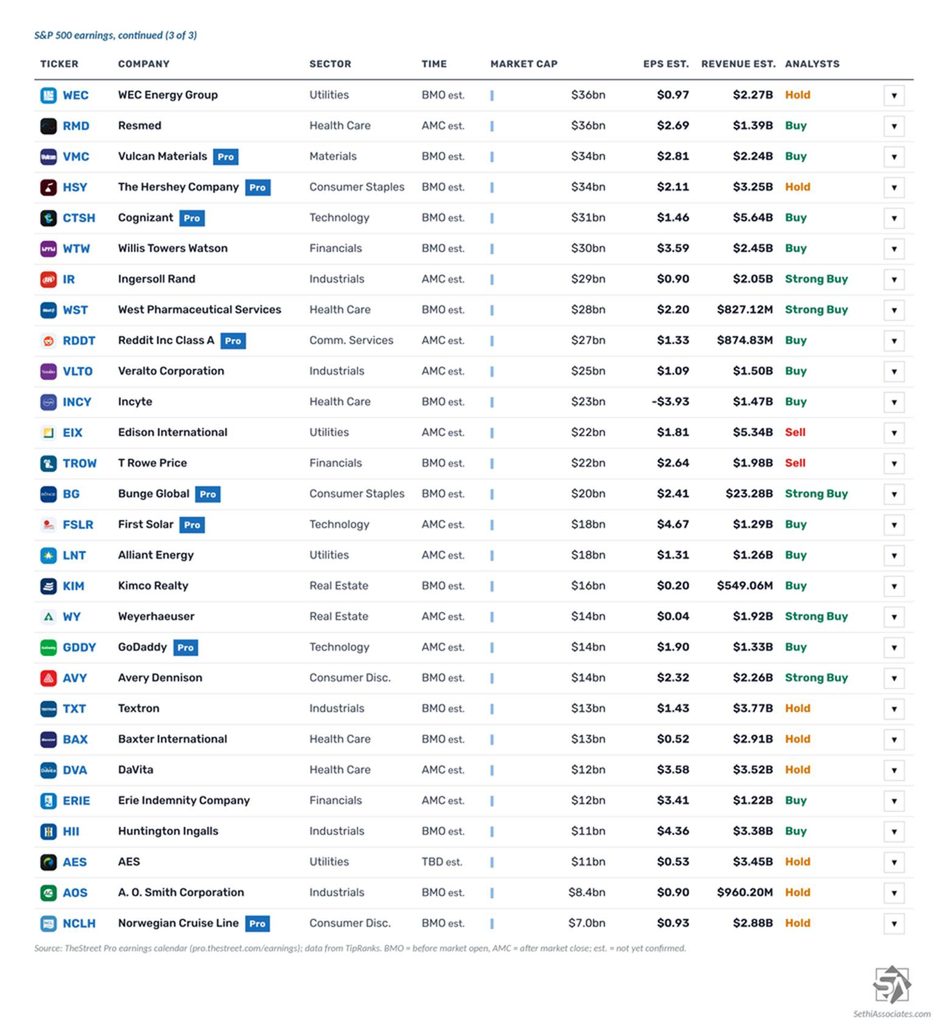
– $RDDT -22% (strong headline growth was overshadowed by a 2% decline in US daily active users)
– $TWLO -19% (Q3 beat and FY outlook rose, but Q4 organic growth is set to slow sharply and operating-profit guidance disappointed)
– $RBLX -16% (Q4 bookings forecast calls for a 10% to 15% year-over-year decline)
– $ILMN -13% (revenue missed and slowing instrument growth outweighed a guidance raise partly helped by tariff refunds)
– $DELL -12%, HPQ -10%, P -7.8%, HPE -7.6% (hardware and storage names tumble as the PC warning and heavy AI spending trigger broad tech de-risking)
– $SYK -10% (Q3 sales and profit missed and the FY outlook was cut amid softer hip and knee demand)
– $SNDK -9.4% (strong quarter and guidance trigger a high-expectations sell-the-news reaction as consumer revenue fell sharply)
– $CCJ -8.7% (Q3 results fell year over year as a longer Key Lake outage raised costs and Westinghouse equity earnings declined)
– $CRDO -8.7%, ARM -9.5%, AMD -9.8%, ASX -8.7%, SMTC -9.5%, NVDA -2.7% (semiconductors fall after the weak chip outlook sparks a global technology rout)
– $COHR -8.8%, BE -9.0%, NBIS -8.3%, GLW -7.1% (AI-infrastructure names unwind as negative free cash flow renews concerns over capex returns)
– NWG -8.1% (quarterly profit fell, impairment losses nearly doubled and the next buyback decision was deferred)
– WDC -8.1%, STX -7.2% (storage names fall alongside the memory selloff and broader AI-hardware de-risking)
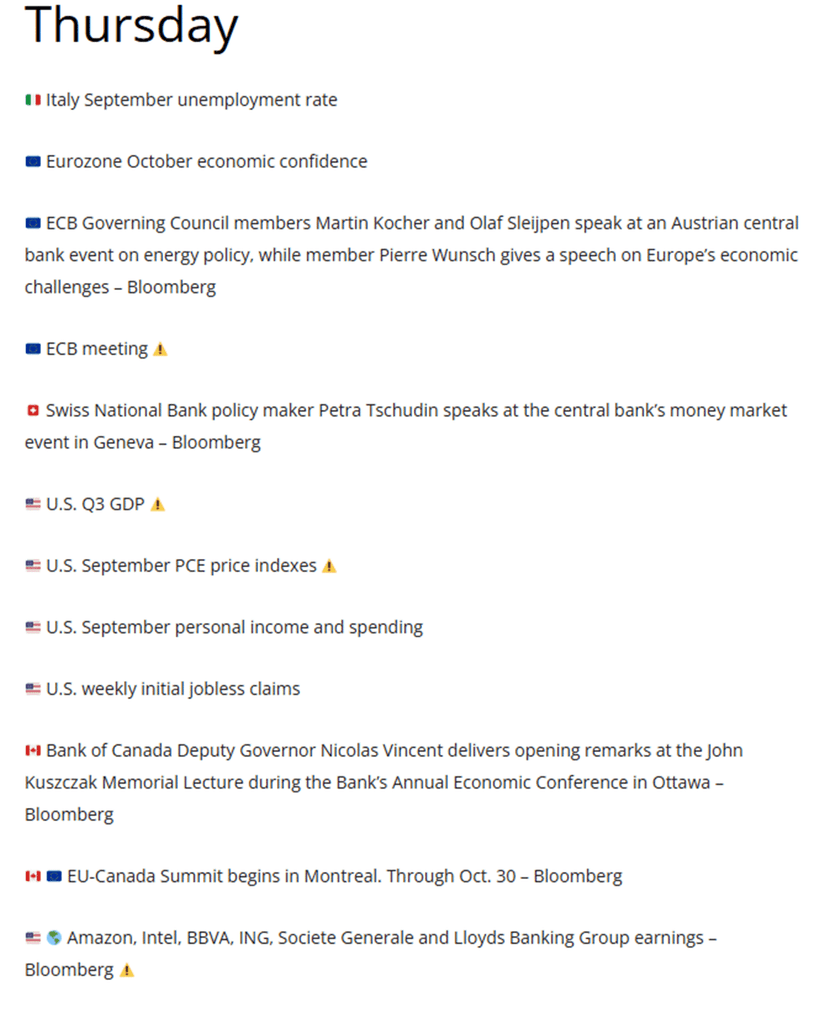
– AMZN -7.4% (Q3 sales and profit missed, free cash flow turned deeply negative and the holiday-quarter sales outlook was cautious)
– PINS -7.3% (Q3 revenue missed guidance and the Q4 outlook implies further growth deceleration)