More Tales From Nvidia: Oh What a Night! (Issue #266!)

* As I recall it ended much too soon…
Oh, what a night
Late December back in ’63
What a very special time for me
As I remember what a night
Oh, what a night
You know I didn’t even know her name
But I was never gonna be the same
What a lady, what a night
Oh, I got a funny feeling
When she walked in the room
And I, as I recall
It ended much too soon
Oh, what a night
Hypnotizing, mesmerizing me
She was everything I dreamed she’d be
Sweet surrender, what a night
– Frankie Valli & The Four Seasons, Oh What A Night
Well the hits keep on coming.
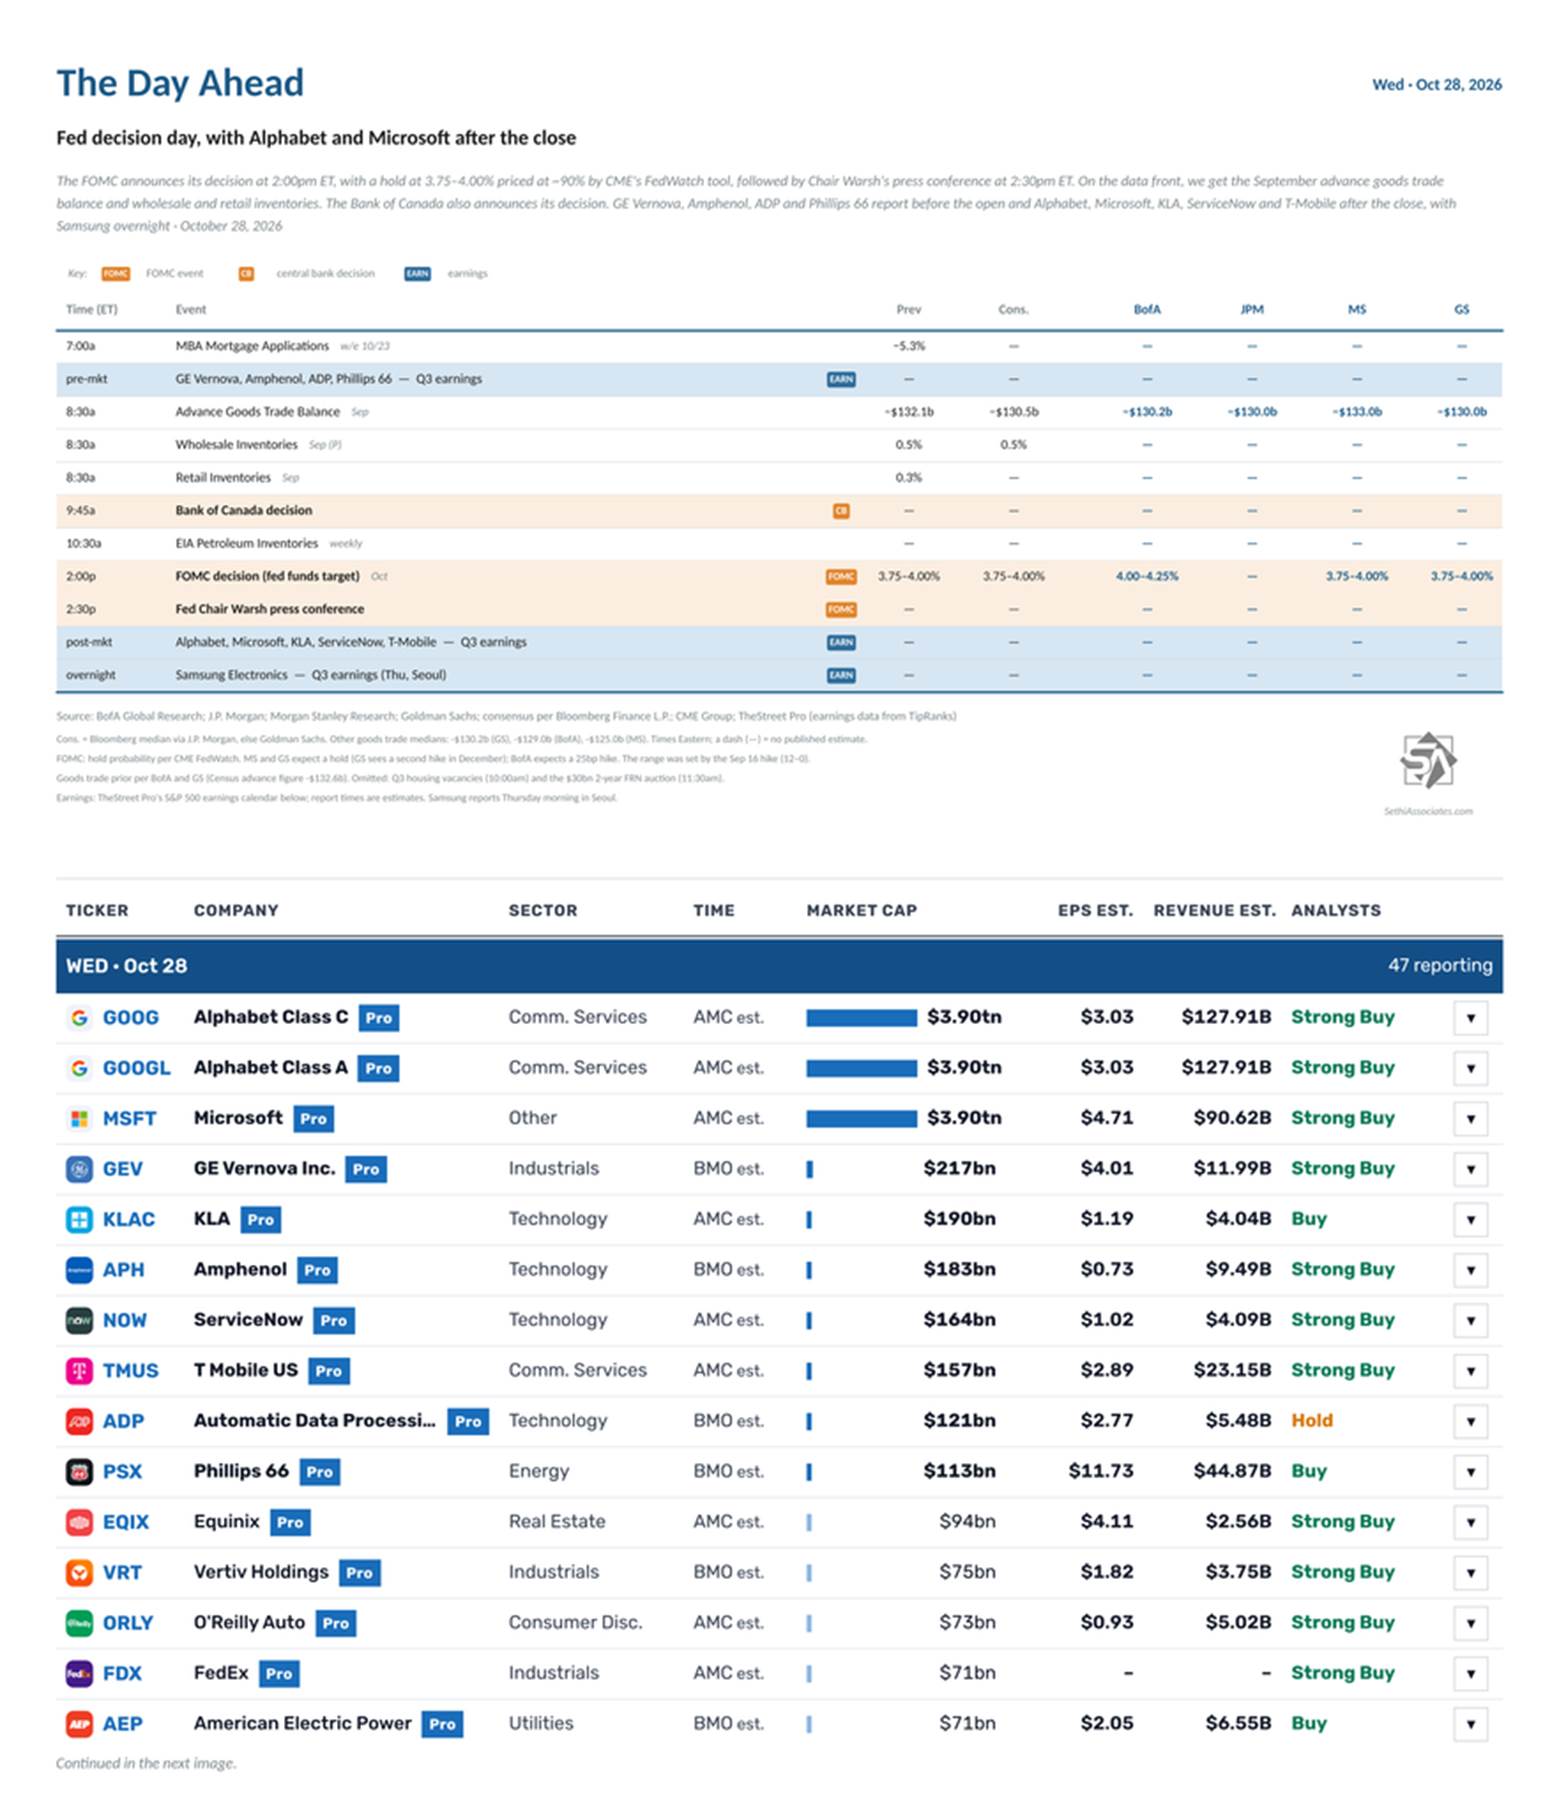
Amazon ($AMZN) free cash flow just came in at negative $42.4 billion versus expectations of negative $7.7 billion. During the quarter they already had to issue $48 billion of debt. How much more capital will they now need to raise? Further, they spent $76 billion in capex, but now guidance for next quarter implies that number going down to $48 billion, which is a 37% sequential decline.
How is this good for suppliers? Maybe ask Intel ($INTC)? Their stock price is only down 22% after hours because of their guidance as they try to keep up with ServiceNow ($NOW). Remember, Amazon is one of the companies that told us they had racks of unused equipment (and chips) sitting in warehouses, and that is when things were presumably good. And there was another story that GPUs are sitting unutilized half of the time. Then of course 80% of end demand appears to be coming from VC startups that do not need to exist.
I also wonder what Intel is seeing that Microsoft ($MSFT) is not seeing, or maybe Microsoft is per the aforementioned shrinking bookings and flat backlog?
When the cash does not come from the business, it comes from someplace else. Long-term debt nearly tripled in nine months, from $65.6 billion at the end of 2025 to $173.1 billion at the end of September, due to $115.1 billion of new long-term borrowing year-to-date ($48.1 billion in Q3). Cash fell from $86.8 billion to $55.8 billion. Interest expense more than tripled to $1.7 billion in Q3, from $0.5 billion a year ago. “Other long-term liabilities” nearly tripled too, to $99.9 billion from $36.0 billion. And who knows what else may be lurking off balance sheet. When is the next offering, and will it be equity or debt?
With all of this, everything missed, including Amazon Web Services by a few percent, and guidance was also light.
I go back to this issue (previously discussed in the last issue of “More Tales”) and the following chart which shows the amount of depreciation on the come for the big hyperscalers. Meta, Amazon and Google ($GOOGL) are already cash flow negative. Their cash flow now tells you where earnings are headed in the future as the massive depreciation bolus makes its way into the P&L.
Per the chart, as usual the sell-side models at the individual company level are all B.S. They do not flow enough depreciation into the P&L going forward. They make up too much revenue on the come in the future. Then they assume much too high of a margin on that revenue, especially given all the capacity coming on line, that will have to be sold. It is all made-up crap. They can’t even get it right for the current quarter, you think these models are anywhere close 2-3 years out?
The whole earnings growth story that has been driving these companies, and equities overall (which is really just these companies), forget about it. With this much depreciation on the come, it is quite challenging for earnings to grow. Stagnant earnings, frankly, would be a great outcome relative to what might actually happen.
The whole AI trade is busted, but everyone is still all in (including a lot of highly levered Leotard’s and highly levered retail). The spenders will have to slow their spending. Demand is clearly slowing, and their balance sheets are broken. That is no good for the suppliers.
The spenders are screwed too, because they have all spent too much money, there is too much capacity being put in place, and it is all a big no differentiated product. Then they have scads of depreciation on the come. The spenders will not be able to cut their way out of the mess.
Then the whole circular ecosystem is entangled with itself with promises they all cannot afford to keep, nor will be possible to keep. The big winners are going to be the lawyers as this spaghetti of a circular mess is litigated to oblivion. Not even the central bank of Nvidia ($NVDA) can bail this thing out, although I am sure they will try until they too end up impaling themselves. In fact, their cash flow and balance sheet is already telling a very different story than their earnings as well. I suspect the lawyers are already sending them lots of business cards based on what they see coming as Nvidia is at the center of the whole mess.
Oh, and per the prior on Bill Gurley and the Anthropic IPO, he said these things back in 2008. Boy did he have no idea how much worse it was going to get both in terms of the behavior of the venture markets and the public markets, which are both intertwined:
With the economic collapse in the fall of 2008, Gurley garnered attention when he sent a letter to his portfolio companies, advising CEOs to exercise caution in spending but to look for and take advantage of opportunities that become available during harsh economic times. In a 2015 interview Gurley said of private tech investing, “it’s my belief that Silicon Valley and the venture-backed businesses have moved into a world that is both speculative and unsustainable.” Gurley’s warnings, and posts on his personal blog, Above the Crowd, on venture capital spending, have been widely discussed in the industry.
Post Script
Interesting comment from what is now a former prominent venture capitalist about the IPO process. This is what investing has become, at least for the private investors. It is a game of markups. Not so different than kiting stock back and forth.
At the end of the food chain are the bankers, who want to keep the game going. The IPO price is not a function of the value of the underlying business. It is reverse engineered to “reward” investors in the prior round who are part of the game and continual big fee payers and generators, at the expense of the public including widows and orphans. The conversations are all had along the way about what the next round can be marked up to, and at what valuation the IPO price will ultimately be at.
The bankers also have the additional incentive of trying to keep the whole circular AI game going, because all of their lines of business benefit from it. They do not want the party to end. Like Chuck Prince said at the peak of the housing bubble, when the music is playing you keep dancing. How did that end for Chuck and everyone else? At any rate, it is no coincidence that the world’s largest bank has signed up to lead the Anthropic IPO:
With regard to reverse engineering price, Anthropic’s fundamentals have obviously deteriorated, yet there has been no change in the theoretical IPO valuation. Just more obfuscation. The disappointing Q3 numbers and obvious decay in trajectory in Q3 has been left blank in the S-1.
The governance and insider unlocks are a joke (per the point about rewarding investors). They are basically telling you margins will get worse, not better, per page 134, which states “we expect our use of short-term compute to increase in the near term an in turn to compress our operating margin.” This is the exact opposite of what is meant to happen when a business scales. The whole thing is beyond the pale from my perspective.
This is the wholesale dumping of a faltering business with ridiculous governance on to the public at an unheard of valuation with ridiculous terms. Whether or not legal doublespeak and disclaimers allow for this to happen does not mean it should happen or that anyone should stand behind this and actually facilitate it happening. It frankly is gross. Here is a good summary of what is in the S-1:
“I believe that Anthropic is intentionally misleading investors at a scale unseen in the history of IPOs. Whatever excitement anyone might have about cashflows or the stretched definition of “profitability” is irrelevant, as Anthropic is, by its own admission and its unbelievable obligations, a completely different company to the one it was in the second quarter of this year.”
Here is an interesting nit that flew under the radar. On their conference call, the Microsoft CFO referred to GPUs as “short lived assets.” She said 75% of their capex is now directed to these “short lived assets.” So much for those lengthy depreciation curves. It should really be accelerated depreciation, under a much shorter timeline. The reason compute price went up over the short term is access to power, not the underlying value of the silicon or servers, which continue to depreciate apace. ~80% of demand for compute is coming from VC startups that do not need to exist. My guess is compute prices will soon head the way of token prices. At any rate, anyone lending against chips as collateral deserves to lose their money.
Speaking of Microsoft, they just turned around and announced a $25 billion debt offering, because they too need cash. This is after Meta who is selling $90 billion of equity, and SpaceX ($SPCX), which just did $40 billion more of debt. I do not even understand the capital structure choices. MSFT is trading at a 30x P/E, and SpaceX lord knows what multiple. I would be selling equity hand over fist. Not sure if they prioritize their short-term stock price, or just keeping the float thin so the stock is more easily pushed around.
Google’s business is obviously under pressure. Microsoft’s business is less obviously under pressure. The revenue and EPS print was good, which is what the stock reacted to AH. But their bookings shrunk and their backlog did not grow. That is the leading indicator, and why the actual trading is quite different from the AH reaction. Frankly I am surprised the stock is not down more.
Due to the pressure on their business, both Microsoft and Google came in under their expected capex. This tells you what they now think about their forward prospects. If capex upside was good for the AI trade, Capex downside should be bad. Further, it seems things are slowing for both sides of the equation. Ergo the spenders are struggling on the revenue side, not good for them. And they are cutting on the capex side, so not good for the receivers. Ergo double whammy.
Microsoft spent $38 billion versus $46 billion estimates, and Google spent $51 billion versus $56 billion estimated. Forward commentary about capex staying intact should be largely ignored, that is just akin to not being willing to fess up that business is slowing, which it obviously seems to be doing. At any rate, Google is in the negative free cash flow bucket along with Amazon and Meta now. All the depreciation is on the come.
Cash flow tells the story now about what earnings are going to do in the future. Google is still FCF negative despite spending $5 billion less capex than was expected. FCF came in at -$9 billion versus -$3.5 billion expected. When will Google be joining the capital raising party?
Meanwhile, as everything goes down, Apple ($AAPL) goes up again, to another ATH for both the stock price and P/E, while nothing good is going on there. If being viewed as NOT AI is good, then shouldn’t AI be viewed as not good? Once again the rotation game, there is no real selling yet. But it is so odd. People could go to cash, or into something not tech. But there is just the reflexive behavior out of one tech name, into another, for no real reason.
Good luck for the agents, like Muse. I continue to believe they will be cut off at the knees by nearly every business they try to involve themselves with. I also think the novelty will quickly wear off for those that downloaded Muse. I think the download rate will also slow, and it may have slowed already.
This blast email out from B of A today to their account holders:
Protecting your finances in the AI World
At Bank of America, we’re continuing to invest in innovative technologies, including AI, to make your financial life easier, more personal and more secure. As other broad-ranging tools are introduced to help manage finances, we encourage you to keep security top of mind.
Please remember that your username and password should never be shared with another person or provided to an outside service, including an AI-enabled tool or agent that offers to act on your behalf.
If you do share your credentials, keep in mind that you’re responsible for activity resulting from that access.
We’re excited about what AI used responsibly can deliver. As your financial partner, we’ll continue to bring you innovative services while helping you stay secure and protect what matters most.
Thank you for being our client.
And thank you for your attention to this matter.
Position: None