The Bulls Are Leaving the Building. That Could Improve the Odds of a Rally.

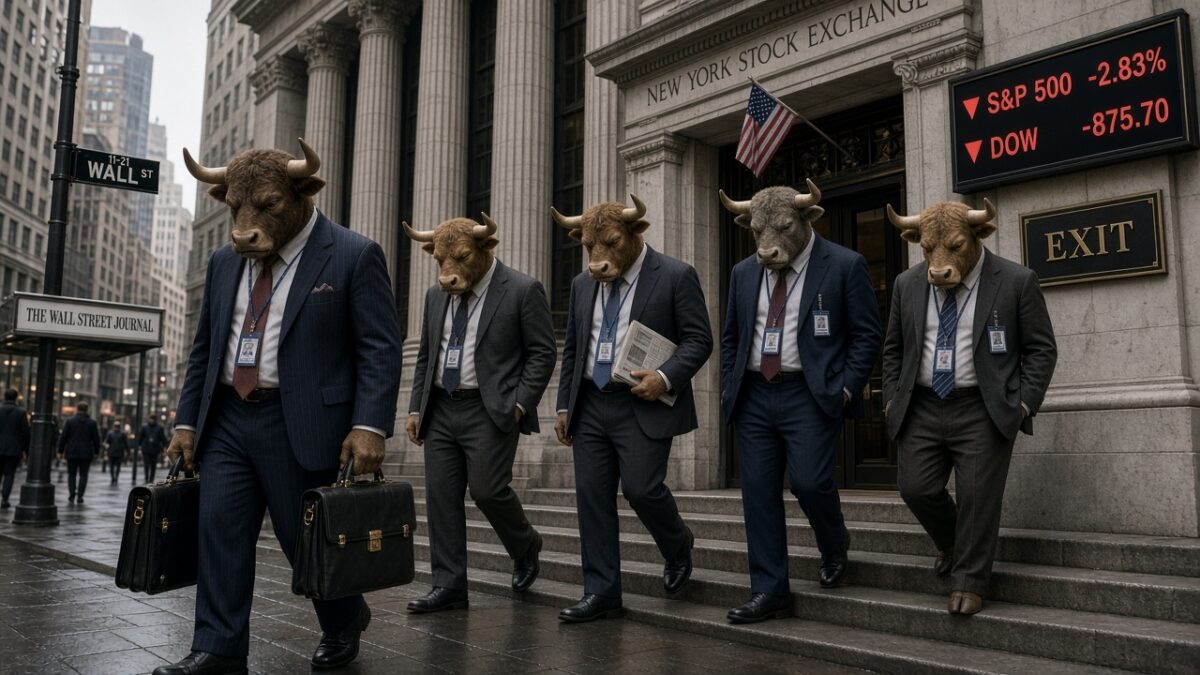
It’s counterintuitive, but if more people turn bearish, then there is more fuel for a rally as those investors jump back into the market.
It’s counterintuitive, but if more people turn bearish, then there is more fuel for a rally as those investors jump back into the market.
Stocks recovered from early losses as Tech bounced and the largest drop in 10- and 30-year yields in over a year saw five sectors gain over 1%.
Nvidia, the S&P 500, and the Nasdaq Composite are breaking out in unison.
Payrolls missed every estimate, raising bets for an October FOMC hold, and the Nasdaq-100 powered to a record high. But Treasury yields reversed an early drop.
Anthropic’s IPO timing, Boeing averts strike and other headlines moving the market this morning.
– AMOD +108.5% (closed a bitcoin-funded private placement and regained Nasdaq listing compliance)
– NIVF +40.0% (closed an approximately $1.25M public offering)
– SDEV +36.0% (extends Thursday’s surge in the SKY-token treasury name; no clear fresh company-specific catalyst identified)
– TNMG +20.0% (agreed to sell its Japanese business in a $5.5M management buyout)
– $SYNA +15.0%, ON +8.0% (revised merger makes ON’s acquisition of SYNA an all-cash deal at $123 per share)
– $CYPH +8.5%, $FWDI +6.5%, $MSTR +5.0%, $COIN +1.5% (digital-asset treasury and crypto-linked names rise as Bitcoin and major tokens rally)
– $BETR +7.5% (Cantor Fitzgerald upgrades to Overweight from Neutral)
– $XRPN +7.0% (shareholders approved the proposed business combination with Evernorth)
– $RZAI -21.0% (extends volatile post-direct-listing selling after Thursday’s 29% drop)
– $NXL -20.0% (gives back part of Thursday’s 76% spike following a 10-year Latin American distribution agreement)
– $STX -11.5%, WDC -7.0% (HDD makers fall after Toshiba outlined plans to double capacity and target sharply higher market share)
– $NKE -9.0% (mixed FQ1 as revenue missed and the FY sales outlook implied a surprise steep decline, alongside job cuts and a business reorganization)
– $FICO -8.5%, $EFX -3.5%, $TRU -2.5% (mortgage-credit names fall on a reported FHFA plan requiring lenders to pull data from two credit bureaus instead of three for GSE loans)
– $ASTS -3.5% (B. Riley downgrades to Neutral from Buy)
Let’s check on calls to release diesel reserves, the buildup of troops in the Middle East, crude prices and … why the banks could rally.
Treasury yields move up, oil rises, Nike earnings, and other headlines moving the market this morning.
A cooler-than-expected core PCE lifted stocks early, but a rebound in yields and a sharp final-hour selloff left the Nasdaq as the lone gainer on the day and month.