Key Earnings See Negative Reactions as Rotation Hits a Bump in the Road

SpaceX spent more, Tesla spent less, and Meta proved its spending works. The market is selling all three.
SpaceX spent more, Tesla spent less, and Meta proved its spending works. The market is selling all three.
Blowout SpaceX results lifted a swath of AI names, sending the Nasdaq up over 1%.
One stop remains in our AI series, and it’s the one folks rarely think about.
Super Micro Computer crushes expectations while United Airlines and Alaska Airlines confirm energy input concerns. Those and other headlines are moving the market this morning.
Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
From my evening update:
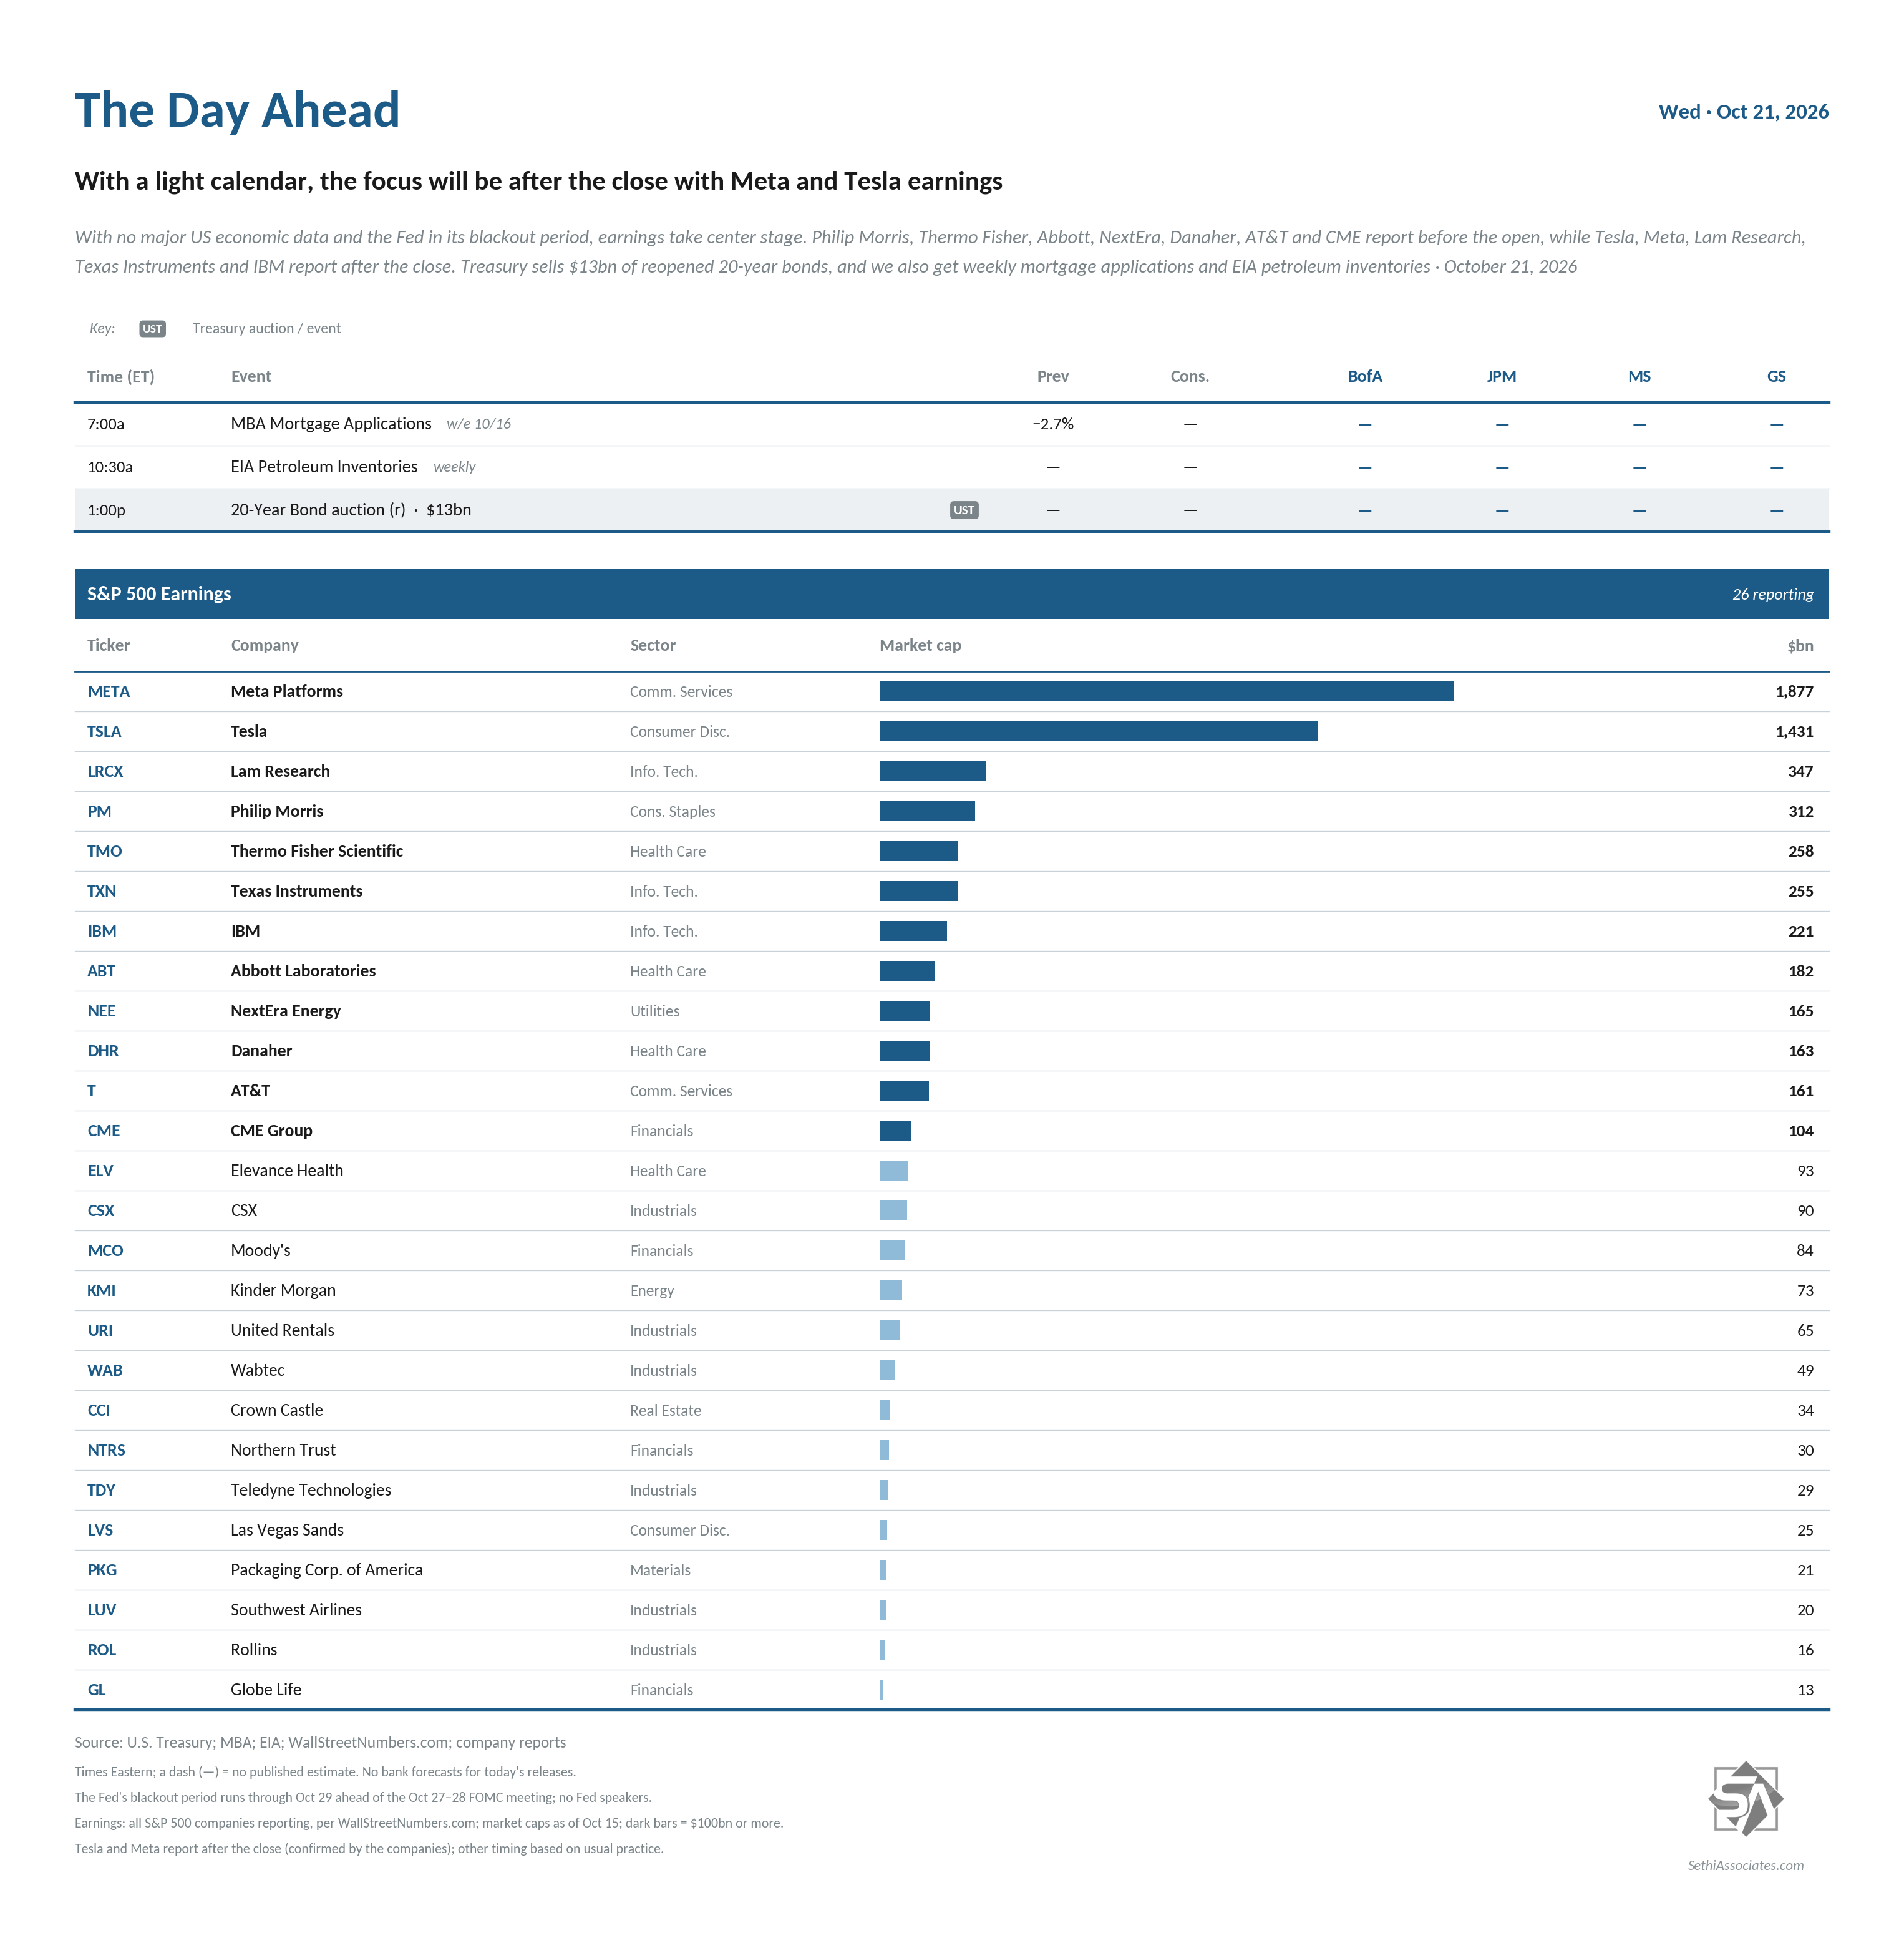
US economic data is light Wednesday, with only weekly mortgage applications and EIA petroleum inventories.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions resume with a $13B 20-year bond reopening.
Q3 earnings season continues with 26 S&P 500 components including a number of AI-related names: Meta Platforms ($META), Tesla ($TSLA), Lam Research ($LRCX), Philip Morris ($PM), Thermo Fisher Scientific ($TMO), Texas Instruments ($TXN), IBM ($IBM), Abbott Laboratories ($ABT), NextEra Energy ($NEE), Danaher ($DHR), AT&T ($T), CME Group ($CME), Elevance Health ($ELV), CSX ($CSX), Moody’s ($MCO), Kinder Morgan ($KMI), United Rentals ($URI), Wabtec ($WAB), Crown Castle ($CCI), Northern Trust ($NTRS), Teledyne Technologies ($TDY), Las Vegas Sands ($LVS), Packaging Corp. of America ($PKG), Southwest Airlines ($LUV), Rollins ($ROL) and Globe Life ($GL).
Ex-US highlights are UK September CPI, PPI, RPI, public finances, August house price index, Japan September trade balance, New Zealand Q3 CPI.
Easing long-term yields and oil prices lifted the Russell 2000 to its best day since early August and saw 9 of 11 S&P 500 sectors higher, even as weakness in Tech dragged on the cap-weighted index.
– $IRON +52% (Phase 3 APOLLO trial met all primary and secondary endpoints in erythropoietic protoporphyria)
– $AAME +41% (long-delayed 2025 annual report was filed, showing a return to annual profitability)
– $XLAB +24% (extends rally after securing an $8.2M AI-server order)
– $TCRT +20% (extends volatile rally tied to a proposed acquisition and financing of up to $350M)
– $MEDS +15% (extends rally after outlining peptide-compounding expansion and licensing a direct-to-consumer GLP-1 platform)
– $CLF +11% (Q3 profit and EBITDA beat expectations, Q4 EBITDA was guided higher and 2027 EBITDA is expected to exceed $4B)
– $NBIS +7.5%, $CRWV +7.7%, $BE +5.2%, $SMCI +4.1%, $IREN +5.9% (AI-infrastructure names rebound from last week’s financing-driven selloff as Treasury yields ease)
– $CRDO +4.7%, $TER +5.1%, $LRCX +4.6%, $AMD +3.7%, $MU +3.7%, $AVGO +3.1% (chip names rebound from last week’s AI-led selloff ahead of key sector earnings)
– $INTC +4.3% (JPMorgan upgrades to Neutral from Underweight as confidence in the turnaround improves)
– $VAI +4.0% (agrees to acquire an 18MW Ohio computing center)
– $DDOG +3.9% (Bernstein upgrades to Outperform and sharply raises its price target on stronger AI-consumption trends)
– $ACTU -9.1% (files to sell 40M shares with 20M warrants)
AI worries are pressuring Tech and sending yields lower as we embark on a heavy earnings week including several names in the cross-hairs.
Another selloff in AI names broadened to encompass most of Tech, sending the Nasdaq-100 to its worst week since April 2025. Five sectors though would finish the week up 2% or more, as 30-year Treasury yields fell the most since April 2025.