Tech’s Monday Bounce Reverses, Pushing the Nasdaq 100 Into Correction

Another drawdown in Tech, following its worst month since March 2025, overshadowed six sectors advancing more than 1%.
Another drawdown in Tech, following its worst month since March 2025, overshadowed six sectors advancing more than 1%.
– $INO +262% (FDA grants accelerated approval to VOCERYQ to reduce surgery frequency in adults with recurrent respiratory papillomatosis)
– $PERI +31% (agrees to be acquired by Affle for $11.70 a share in cash, valuing the deal at about $420M)
– $IDXX +7.8% (Q3 beat and FY revenue and EPS outlooks were raised, outweighing a slightly lower margin range)
– $BABA +3.3% (China adds liquidity through a 100B-yuan swap facility, while reports point to BABA support for AAPL’s China AI rollout)
– $SKHY +3.2%, MU +1.1%, WDC +1.0%, SMTC +1.3% (memory and connectivity names rebound from Friday’s chip rout as Deutsche Bank turns bullish on US technology)
– $GFI +3.1%, AG +1.7%, HL +1.9% (gold and silver miners rebound as precious-metal prices recover)
– $RIVN +3.0% (UBS upgrades to Buy on valuation after the recent selloff)
– $CRWD +2.6% (Deutsche Bank upgrades to Buy)
– $EL +2.3% (Q1 beat with strong margin expansion and the FY sales, margin and EPS outlook raised)
– $AU +2.2% (TD Cowen initiates at Buy as gold rebounds)
– $FORM +1.7% (Freedom Capital upgrades to Buy after record Q3 results and the recent pullback)
– $CRWV +1.4%, BE +1.2%, $VRT +1.3% (AI-infrastructure names rebound with technology after the sharp three-week selloff)
– $KPTI -69% (files Chapter 11 and names Ayrmid as lead bidder in a court-supervised sale process)
– $PGEN -28% (falls on new RRP competition after the FDA approves INO’s VOCERYQ)
– $KOS -9.2% (Q3 profit and revenue missed expectations as crude prices retreat)
– $CHKP -6.3% (Q3 revenue slipped and missed expectations as management said the recovery is taking longer than anticipated)
– $EQNR -2.9%, $OXY -2.0%, $APA -1.9%, $XOM -1.3%, $CVX -1.1% (oil producers fall as crude drops nearly 4% on renewed US-Iran diplomacy)
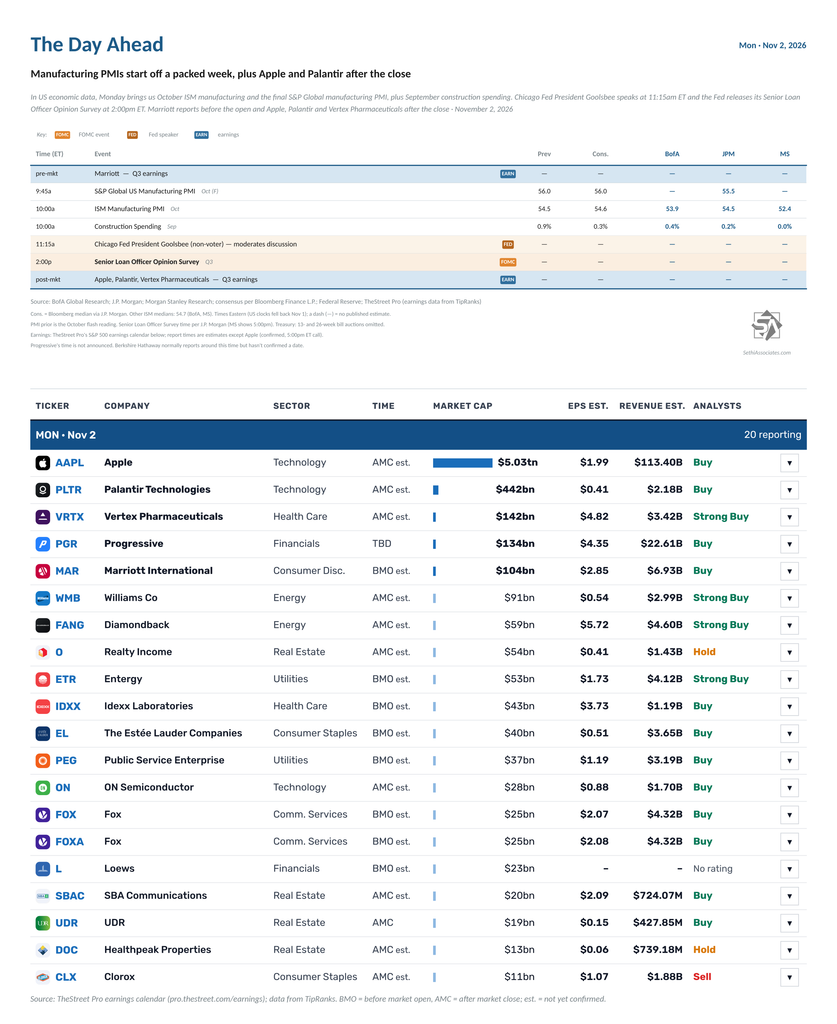
In US economic data, Monday brings us October ISM manufacturing and the final S&P Global manufacturing PMI. September reports are construction spending.
In terms of the Fed, Chicago Fed President Goolsbee (non-voter) moderates a discussion at 11:15am ET, and the Fed releases its Senior Loan Officer Opinion Survey at 2pm ET.
There are no Non-Bill (>1yr in maturity) US Treasury auctions this week, but we’ll get the Treasury’s borrowing amounts for the fourth quarter today.
19 S&P 500 components report, five of them with market caps over $100B:
Before the open: Marriott ($MAR), Entergy ($ETR), Idexx Laboratories ($IDXX), Estée Lauder ($EL), Public Service Enterprise Group ($PEG), Fox ($FOXA) and Loews ($L)
After the close: Apple ($AAPL), Palantir ($PLTR), Vertex Pharmaceuticals ($VRTX), Williams ($WMB), Diamondback Energy ($FANG), Realty Income ($O), ON Semiconductor ($ON), SBA Communications ($SBAC), UDR ($UDR), Healthpeak Properties ($DOC) and Clorox ($CLX)
Time not announced: Progressive ($PGR)
What to watch with SpaceX earnings, U.S munition pain point, Duke Energy’s capital plan, and other headlines are moving stocks this morning.


