Intel’s record drop leads a cascade in chip names with the S&P 500 and Nasdaq seeing their worst session since June, while defensive buying gave the Consumer Staples ETF its best month on record.
Over 400 of the S&P 500’s components were higher even as the index ended lower and the Russell 2000 gained for a fourth day while Amazon and Intel dropped after hours
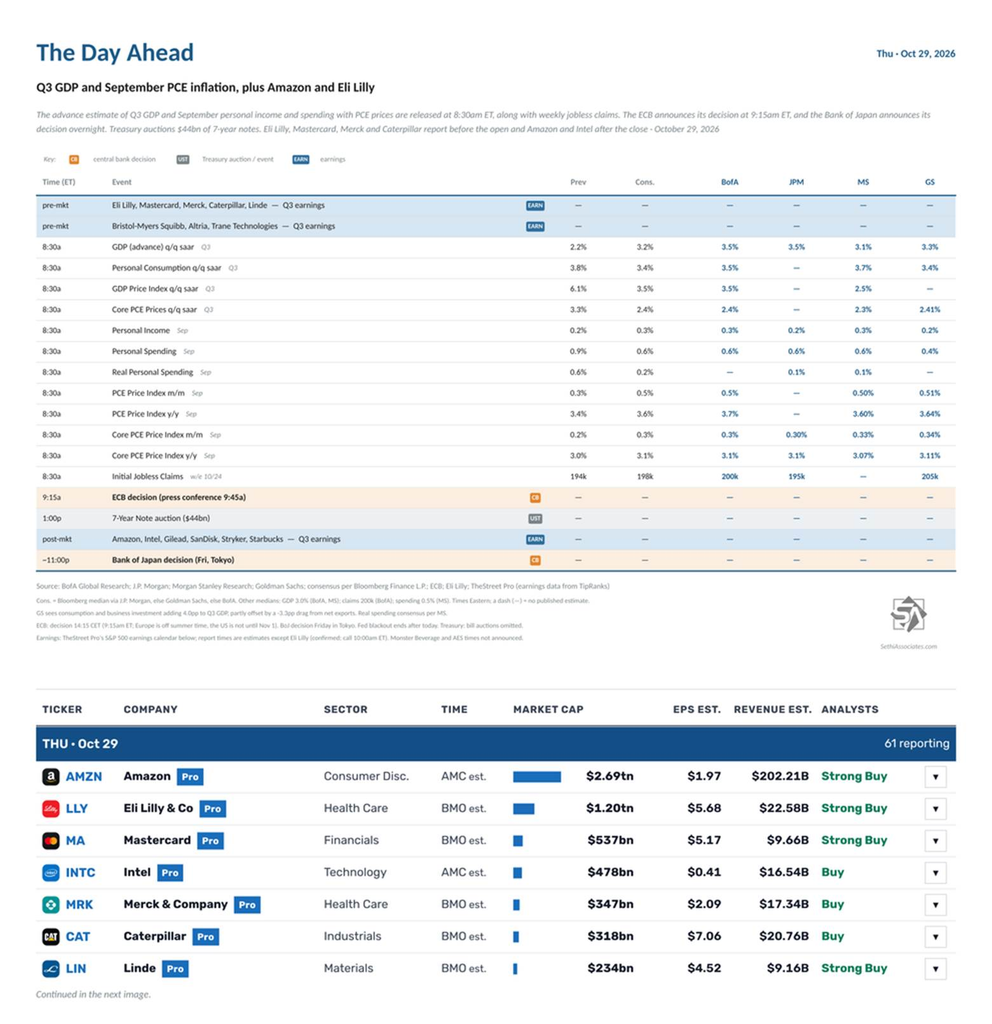
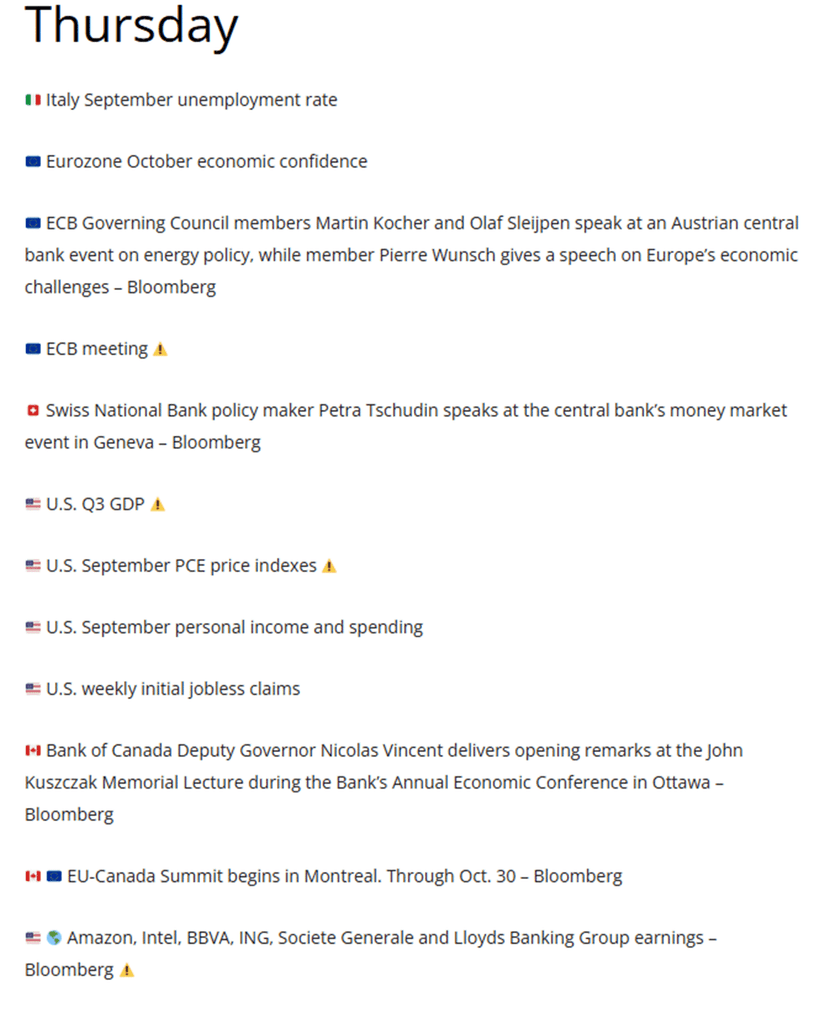
US economic data includes the advance estimate of Q3 GDP, which will incorporate September personal income and spending with PCE prices that will also be separately reported. We’ll also get weekly unemployment claims.
The Fed’s blackout period extends until midnight, with Fed speakers resuming Friday.
The non-Bill (>1yr in maturity) US Treasury auction is $44bn of 7-year notes.
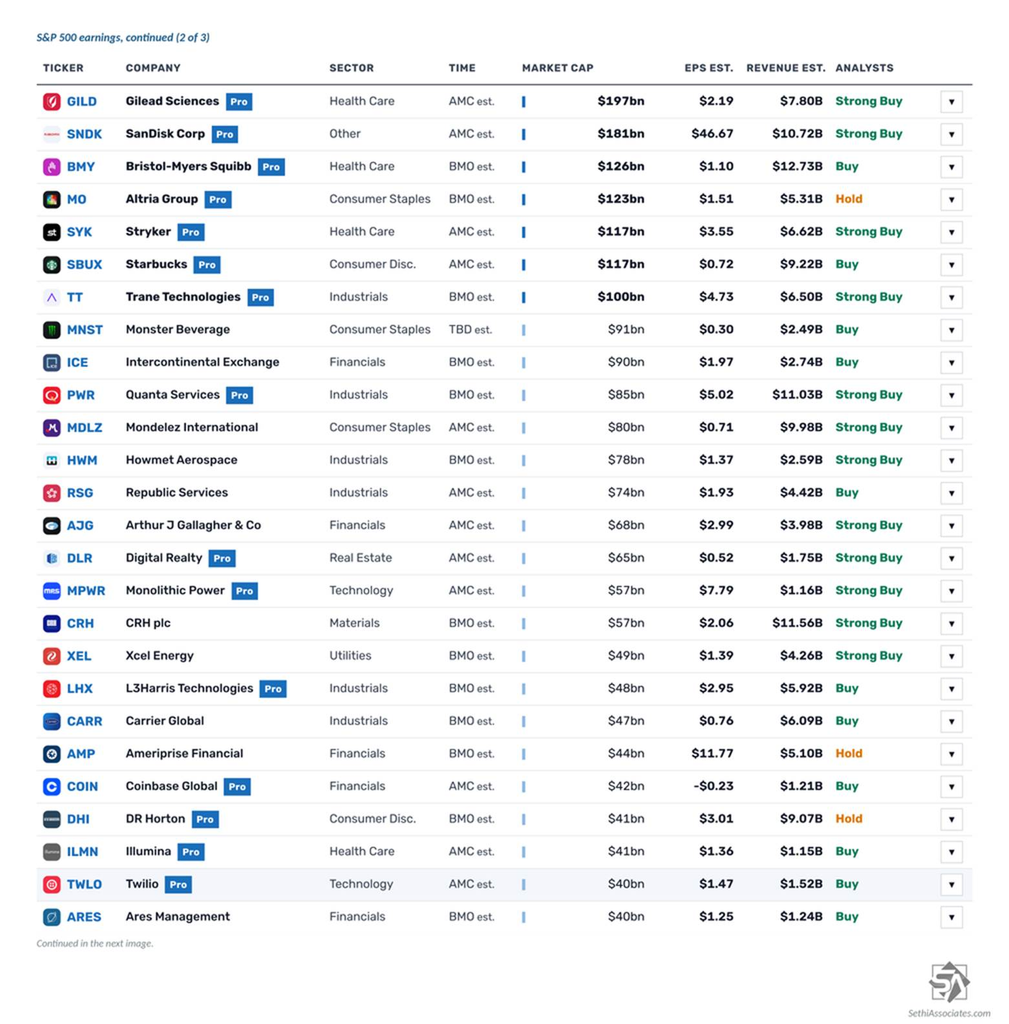
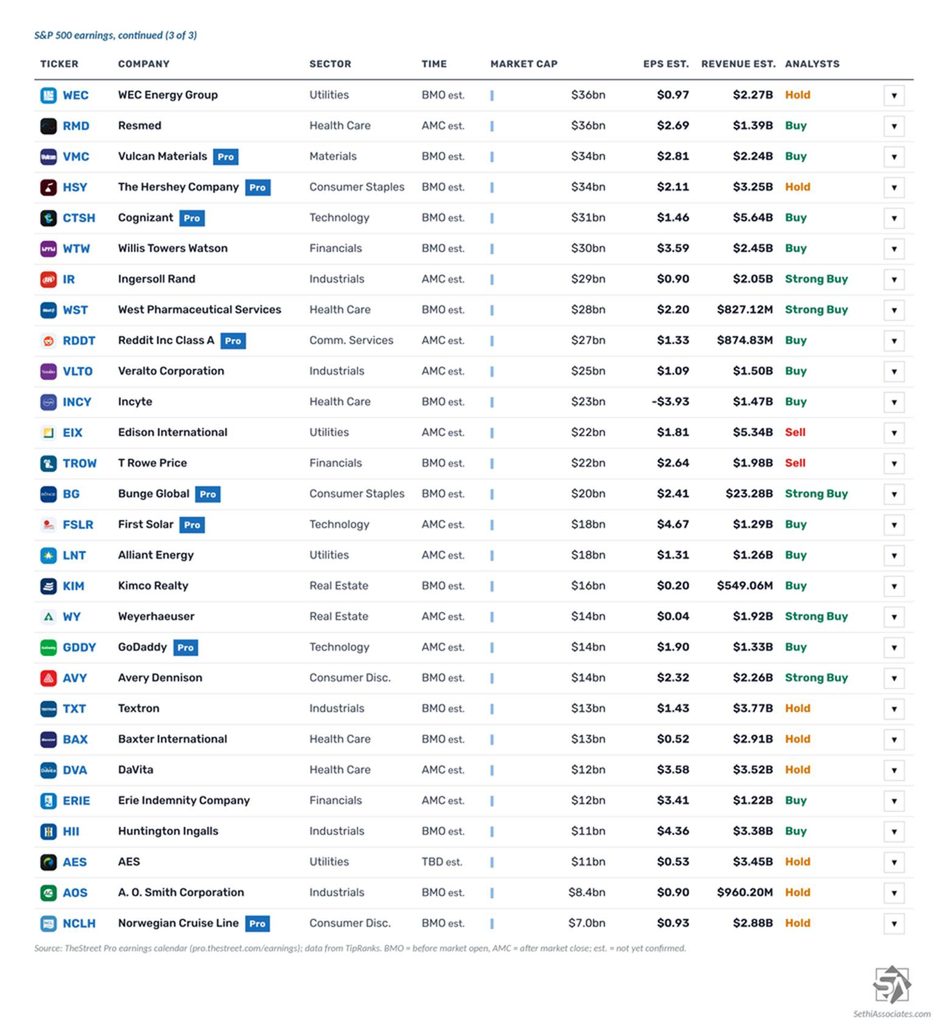
61 S&P 500 components report, 14 of them with market caps over $100bn:61 S&P 500 components report, 14 of them with market caps over $100bn:
Before the open: Eli Lilly ($LLY), Mastercard ($MA), Merck ($MRK), Caterpillar ($CAT), Linde ($LIN), Bristol Myers Squibb ($BMY), Altria ($MO), Trane Technologies ($TT), Intercontinental Exchange ($ICE), Quanta Services ($PWR), Howmet Aerospace ($HWM), CRH ($CRH), Xcel Energy ($XEL), L3Harris ($LHX), Carrier ($CARR), Ameriprise ($AMP), D.R. Horton ($DHI), Ares Management ($ARES), WEC Energy ($WEC), Vulcan Materials ($VMC), Hershey ($HSY), Cognizant ($CTSH), WTW ($WTW), West Pharmaceutical ($WST), Incyte ($INCY), T. Rowe Price ($TROW), Bunge ($BG), Kimco Realty ($KIM), Avery Dennison ($AVY), Textron ($TXT), Baxter ($BAX), Huntington Ingalls ($HII), A.O. Smith ($AOS) and Norwegian Cruise Line ($NCLH)
After the close: Amazon ($AMZN), Intel ($INTC), Gilead ($GILD), SanDisk ($SNDK), Stryker ($SYK), Starbucks ($SBUX), Mondelez ($MDLZ), Republic Services ($RSG), Arthur J. Gallagher ($AJG), Digital Realty ($DLR), Monolithic Power ($MPWR), Coinbase ($COIN), Illumina ($ILMN), Twilio ($TWLO), ResMed ($RMD), Ingersoll Rand ($IR), Reddit ($RDDT), Veralto ($VLTO), Edison International ($EIX), First Solar ($FSLR), Alliant Energy ($LNT), Weyerhaeuser ($WY), GoDaddy ($GDDY), DaVita ($DVA) and Erie Indemnity ($ERIE)
Time not announced: Monster Beverage ($MNST) and AES ($AES)
Outside the US, Shell ($SHEL), TotalEnergies ($TTE) and Volkswagen ($VWAGY) report.
Ex-US highlights include a policy decision from the ECB, UK September net consumer credit and M4, Japan October consumer confidence index, Italy September unemployment rate, October consumer confidence index, economic sentiment and manufacturing confidence, Eurozone October economic confidence and Sweden Q3 GDP indicator.
The Fed held rates steady with two hawkish dissents, Oracle’s aggressive long-term targets lifted AI names, but Alphabet fell about 9% after missing expectations.
– $CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)
– $NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)
– $LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)