Eli Lilly Up, Nvidia Down: Upside, Downside Movers in the Morning

Upside

– $LUNR +10% (record Q3 revenue, margin and positive free cash flow, with backlog reaching $1.9 billion)

– $TTEK +10% (Q4 beat, backlog rose 13% and the FY27 outlook pointed to continued growth)

– $DPU +9.4% (completed deliveries under a $4.8 million robot resale contract)

– $FIGR +6.8% (Q3 earnings reaction after marketplace volume reached the high end of prior guidance)

– $LLY +1.6% (China approves oral GLP-1 weight-loss drug orforglipron)

Downside

– $NBIS -15% (Q3 revenue beat, but the 2026 outlook moved to the low end, the ARR target slipped to February and capex increased)

– $EYE -13% (Q3 profit beat and margins expanded, but FY comparable-sales guidance was cut to 2%-3% from 3%-5%)

– $CRWV -11%, $IREN -7.8%, $SMCI -6.9%, $APLD -6.6%, $DELL -6.2% (AI-infrastructure names sell off as the NVDA leadership crisis hits risk appetite; $CRWV also gives back part of its post-earnings surge)

– $CTVA -10% (Q3 sales fell 9% and the FY outlook was cut on weaker Brazil conditions and pricing pressure)

– $NVDA -8.6% (reports the board is weighing Jensen Huang’s ouster amid widening governance and national-security scrutiny; multiple downgrades add pressure)

– $AAOI -7.8%, $SNDK -7.2%, $AXTI -7.8%, $COHR -6.1%, $MU -5.3%, $LITE -5.4% (AI optical, memory and component suppliers fall as the $NVDA crisis ripples through the hardware chain)

– $FPS -7.4% (Q1 exceeded preannounced guidance and the FY outlook was raised, but strong results were already priced as AI-power names sold off)

– $MSTR -6.7%, $MARA -5.9%, $CLSK -5.5%, $RIOT -5.3%, $COIN -4.5% (crypto-linked stocks fall as Bitcoin declines and broader risk appetite weakens)

– $BABA -5.0% (report says the US is preparing restrictions on Chinese AI companies remotely accessing advanced chips through overseas data centers)

Nvidia’s Selloff Ripples Down the ‘Circular Web’ of Companies It Backs as Board Weighs Huang’s Future

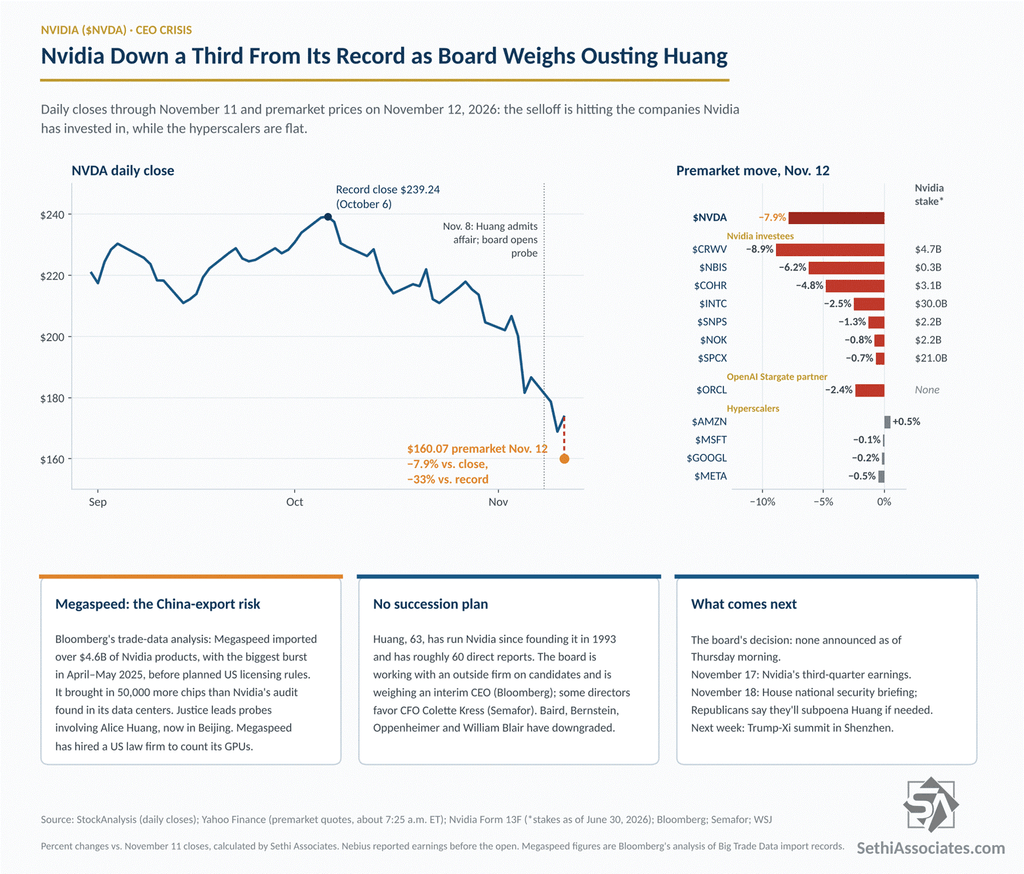
Nvidia ($NVDA) is down about 8% premarket to around $160 after The Wall Street Journal reported Wednesday evening that the board is preparing to oust CEO Jensen Huang. The board met late Wednesday, but as of this morning it hasn’t announced a decision, per Bloomberg’s live blog. At $160, the stock is down a third from its October 6 record close of $239.24, erasing Wednesday’s 2.9% bounce and then some.

Bloomberg reports the board is working with an outside firm on candidates and weighing an interim CEO, and, citing Semafor, that some directors favor CFO Colette Kress. Wall Street is stepping back: Baird, Bernstein, Oppenheimer and William Blair have all downgraded the stock this week, and Morgan Stanley dropped it as a top pick (Bloomberg).

The Selloff Is Hitting Nvidia’s Investees, Not Its Biggest Customers

A telling signal is who’s falling with Nvidia: the circular web of companies it funds that in turn buy its chips. All seven of Nvidia’s major public stakes, per its latest 13F filing, are lower premarket: CoreWeave ($CRWV) down 9.7%, Nebius ($NBIS) 9.2%, Coherent ($COHR) 4.9%, Intel ($INTC) 3.0%, Synopsys ($SNPS) 1.3%, Nokia ($NOK) 1.3% and SpaceX ($SPCX) 0.6%. Oracle ($ORCL), tied in through OpenAI’s Stargate project rather than an Nvidia stake, is off 2.8%.

Meanwhile, the hyperscalers that buy the bulk of Nvidia’s chips are flat: Amazon ($AMZN) +0.2%, Microsoft ($MSFT) −0.1%, Alphabet ($GOOGL) −0.2% and Meta ($META) −0.6%. Rivals Advanced Micro Devices ($AMD) and Broadcom ($AVGO) are higher, as investors bet they could pick up business (Bloomberg).

Two caveats: CoreWeave jumped nearly 25% Wednesday on strong results (more on that here), so it’s only giving back part of that gain, and Nebius reported third-quarter results this morning.

Washington and Megaspeed

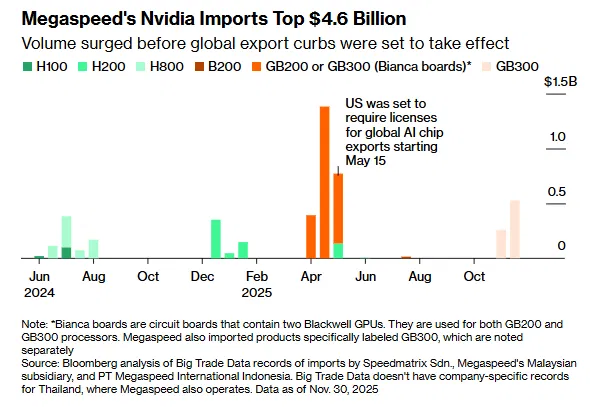
The bigger long-term issue is national security. Huang has admitted an affair with Alice Huang (no relation), a former executive at Megaspeed, a Singapore-based Nvidia cloud partner, whom U.S. officials reportedly suspect of working for Chinese intelligence. Bloomberg’s analysis of trade records shows Megaspeed imported more than $4.6 billion of Nvidia products and brought in 50,000 more chips than Nvidia’s own audit found in its data centers. Overnight, Megaspeed said it had hired a U.S. law firm to count its GPUs and review its export compliance, and Bloomberg reports Alice Huang has resurfaced in Beijing.

On Capitol Hill, House China committee chair John Moolenaar and House Foreign Affairs chair Brian Mast say they’ll likely subpoena Huang if he doesn’t agree to a closed-door briefing. Sen. Kevin Cramer said Huang should resign, and Sens. Elizabeth Warren and Chris Coons have asked the administration to preserve all records on Nvidia chip exports. Bloomberg notes the scandal also complicates next week’s Trump-Xi summit in Shenzhen.

Strong Demand

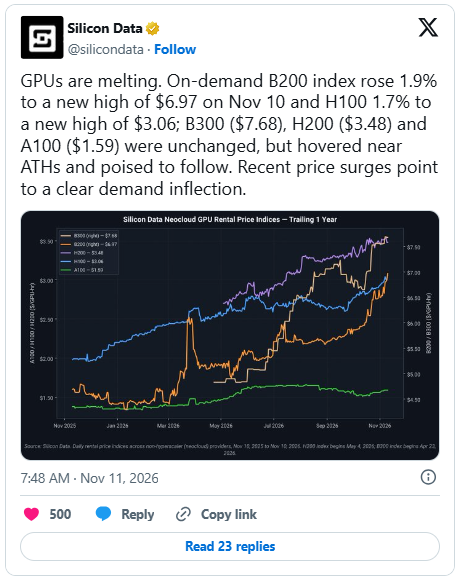
Whatever happens with Huang, though, there remains fierce demand for Nvidia’s products. November 10, at $6.97 and $3.06 an hour. The B300 and H200 are hovering just below theirs, and the H100 is up roughly 50% from a year ago. That comes on top of CoreWeave saying this week it has 10x as much qualified demand as capacity through 2027, showing the market for Nvidia’s chips going into this was as tight as it’s been.

It also matters for the circular-financing worry: rental rates are what back the GPU-collateralized loans to the neoclouds, so firm prices mean that collateral is holding up for now at least.

What to Watch

A quick decision that names an insider such as Kress would signal continuity, but either way the stock is likely to stay under pressure without a successor who was groomed for the job.. ClearBridge’s Michael Feldman warned of a shift from “a Jensen premium to an execution discount” (Bloomberg). Nvidia will report third-quarter results on November 17, the day before Huang is due before House national security committees. For CoreWeave, Nebius and the rest of the companies Nvidia has backed, the question is whether Nvidia keeps writing checks under new leadership.

More on TheStreet Pro

At the time of publication, in terms of securities mentioned, Sethi was long AMD, AMZN, GOOGL, META, MSFT, NVDA and ORCL.

Chips Stocks Up, Inovio & Alcon Down: Upside Downside Movers in the A.M.

Upside

– $FOSL +23% (Q3 beat, gross margin surged and the FY sales and profit outlook was raised)

– $SATL +21% (record Q3 revenue, positive adjusted EBITDA and a post-quarter deal to sell three in-orbit satellites for about $37M)

– $RSKD +20% (Q3 revenue growth accelerated to 41% and revenue and adjusted EBITDA guidance was raised for a third time)

– $GEVO +18% (record Q3 results and higher 2026 EBITDA outlook, helped by carbon-credit sales)

– $CRWV +15% (Q3 revenue beat, the FY outlook was raised and backlog climbed to $132.5B)

– $NBIS +13%, $IREN +7.7%, $DELL +8.1%, $SMCI +5.8%, $VRT +6.2%, $ORCL +5.2% (AI-infrastructure names rise as CoreWeave’s beat-and-raise and customer-prepayment outlook ease demand and funding fears)

– $LITE +9.8%, $COHR +10.1%, $CRDO +8.1%, $AXTI +9.7%, $CIEN +7.9%, $AAOI +7.2% (AI-networking and optical suppliers rally on the stronger infrastructure-demand read-through)

– $STX +9.4%, $SNDK +8.8%, $WDC +8.7%, $MU +7.5% (AI storage and memory names rise on stronger infrastructure-demand expectations)

– $MRVL +9.3%, $TER +7.2%, $ALAB +8.2%, $ARM +6.6%, $INTC +6.5%, $AMD +5.6% (chip complex rallies as CoreWeave’s outlook reassures investors on AI compute demand)

– $NVDA +3.8%, $AVGO +4.5% (megacap chip names rebound as AI-infrastructure sentiment improves)

Downside

– $INVZ -17% (Q3 revenue missed badly and FY sales guidance came in far below expectations)

– $LWLG -16% (volume-production target slipped to 2028 as foundry and qualification delays extended timelines)

– $BV -13% (Q4 missed and FY2027 revenue guidance fell short)

– $GPRO -10% (delayed its Q3 filing and warned lender defaults could jeopardize the planned merger)

– $STIM -10% ($30M underwritten offering priced at $1.60 a share)

– $INO -9.7% (Q3 loss missed expectations despite the recent FDA approval, while fresh financing added stock supply)

– $VELO -8.1% (Q3 loss widened, the gross-margin target was withdrawn and the positive-EBITDA timeline moved to 2028)

– $ALC -4.2% (sales missed as implantables weakened, while market-growth and EPS-growth outlooks were narrowed)

Mondelez Up, Intel Down: Upside, Downside Movers in the Morning

Upside

– $REGN +6.9% (Q3 profit and revenue materially topped expectations)

– $BTSG +6.4% (Q3 beat and full-year revenue and adjusted EBITDA guidance raised)

– $MDLZ +6.4% (profit beat, volume-led growth and upbeat margin and 2027 commentary)

– $RIVN +6.4% (Q3 beat and 2026 delivery outlook raised)

– $AZN +5.9% (Q3 revenue and profit beat on strong oncology growth; FY guidance reaffirmed)

– $MICC +5.4% (Q3 update showed double-digit growth at core brands and more than 30% Yasso growth)

– $GILD +5.1% (Q3 beat and product-sales outlook raised on strong HIV growth)

– $CL +5.0% (Q3 beat, volume and gross margin improved and FY profit guidance was raised)

– $TAK +4.4% (first-half profit beat and FY outlook upgraded, primarily reflecting FX benefits)

– $FDXF +3.9% (inaugural standalone results beat and adjusted margin outlook was raised)

– $ICE +3.7% (extends post-earnings gains after record Q3 results and a higher recurring-revenue outlook)

– $SNY +3.6% (Q3 delivered double-digit sales and profit growth and FY guidance was raised)

– $GD +3.4% (Q3 beat with broad segment growth and robust bookings)

– $DXCM +3.0% (Q3 beat with margin expansion and higher FY revenue and profitability guidance)

– $EXC +2.5% (Q3 beat and FY guidance narrowed while long-term EPS growth was affirmed near the top of its range)

Downside

– $ATEC -32% (Q3 missed as weaker biologics revenue drove cuts to the FY revenue, EBITDA and free-cash-flow outlooks)

– $INTC -25% (Q4 revenue, profit and gross-margin guidance fell well short as the PC slowdown is expected to persist into 2027)

– $RDDT -22% (strong headline growth was overshadowed by a 2% decline in US daily active users)

– $TWLO -19% (Q3 beat and FY outlook rose, but Q4 organic growth is set to slow sharply and operating-profit guidance disappointed)

– $RBLX -16% (Q4 bookings forecast calls for a 10% to 15% year-over-year decline)

– $ILMN -13% (revenue missed and slowing instrument growth outweighed a guidance raise partly helped by tariff refunds)

– $DELL -12%, HPQ -10%, P -7.8%, HPE -7.6% (hardware and storage names tumble as the PC warning and heavy AI spending trigger broad tech de-risking)

– $SYK -10% (Q3 sales and profit missed and the FY outlook was cut amid softer hip and knee demand)

– $SNDK -9.4% (strong quarter and guidance trigger a high-expectations sell-the-news reaction as consumer revenue fell sharply)

– $CCJ -8.7% (Q3 results fell year over year as a longer Key Lake outage raised costs and Westinghouse equity earnings declined)

– $CRDO -8.7%, ARM -9.5%, AMD -9.8%, ASX -8.7%, SMTC -9.5%, NVDA -2.7% (semiconductors fall after the weak chip outlook sparks a global technology rout)

– $COHR -8.8%, BE -9.0%, NBIS -8.3%, GLW -7.1% (AI-infrastructure names unwind as negative free cash flow renews concerns over capex returns)

– NWG -8.1% (quarterly profit fell, impairment losses nearly doubled and the next buyback decision was deferred)

– WDC -8.1%, STX -7.2% (storage names fall alongside the memory selloff and broader AI-hardware de-risking)

– AMZN -7.4% (Q3 sales and profit missed, free cash flow turned deeply negative and the holiday-quarter sales outlook was cautious)

– PINS -7.3% (Q3 revenue missed guidance and the Q4 outlook implies further growth deceleration)

SoFI Up, HSBC Down: Upside, Downside Movers in the Morning

Upside

– $MFIC +23% (ARCC agrees to acquire it for $10.88 per share in cash and stock, valuing the transaction at about $2.6B)

– $INIO +14% (record Q3 results and FY26 revenue and EBITDA outlooks were raised)

– $CLS +12% (Q3 beat, FY26 outlook raised and initial 2027 guidance called for 90% revenue growth on accelerating AI-infrastructure demand)

– $SOFI +11% (record Q3 revenue and EBITDA, strong member growth and a raised FY26 outlook)

– $FER +9.9% (no clear fresh catalyst identified; unusually large, liquid move ahead of 9M results after the U.S. close)

– $RCL +5.3% (Q3 beat, bookings remained strong and the full-year profit outlook was raised)

– $CRDO +4.3%, $SKHY +3.2%, $COHR +2.7%, $AMKR +3.6%, $LITE +2.6%, $AVGO +2.9% (AI-chip and optical-connectivity names rise as the CLS outlook reinforces accelerating hyperscaler demand)

– $JCI +4.3% (Q4 beat and the FY27 profit outlook topped expectations)

– $SPGI +3.8% (FY26 outlook raised and a strategic review of Capital IQ businesses was launched)

– $NBIS +3.7%, BE +3.3%, CRWV +3.6%, VRT +2.2% (AI-infrastructure names gain after CLS said customer demand forecasts continue strengthening into 2027 and 2028)

– $NCLH +2.2%, CCL +2.7% (cruise peers rise after RCL beat expectations and raised its full-year profit outlook)

– $CDNS +1.8% (Q3 beat, FY outlook raised, backlog reached a record $8.2B and a $2.5B buyback was added)

– UPS +1.8% (Q3 beat and FY26 revenue and profit forecasts were raised as shipment mix and cost reductions improved)

Downside

– $XYL -8.5% (Q3 update disappointed, with investors focusing on softer revenue expectations)

– $WSO -8.3% (Q3 profit missed expectations)

– $HSBC -6.7% (Q3 revenue and pretax profit missed expectations, outweighing a new $1B buyback)

– $HLT -4.4% (Q3 earnings beat, but revenue missed and the raised RevPAR outlook was not enough for elevated expectations)

– $SHW -3.8% (Q3 results and outlook disappointed as housing-linked demand remained soft)

– $ONON -3.3% (no clear fresh catalyst identified; unusually large, high-volume premarket decline)

– $MAR -2.0% (hotel peer slips in sympathy with HLT after its revenue miss)