Psst: These Two Biotech Plays Look Like Great Under-the-Radar Deals

The major indexes have pulled back some after the Nasdaq and S&P 500 hit record highs on Tuesday. The Nasdaq fell around 1.3% on Thursday as AI-related names like Nvidia Corp. ($NVDA) dropped after OpenAI posted an annual run rate under previous reported levels. Market breadth remains putrid as can be seen below.
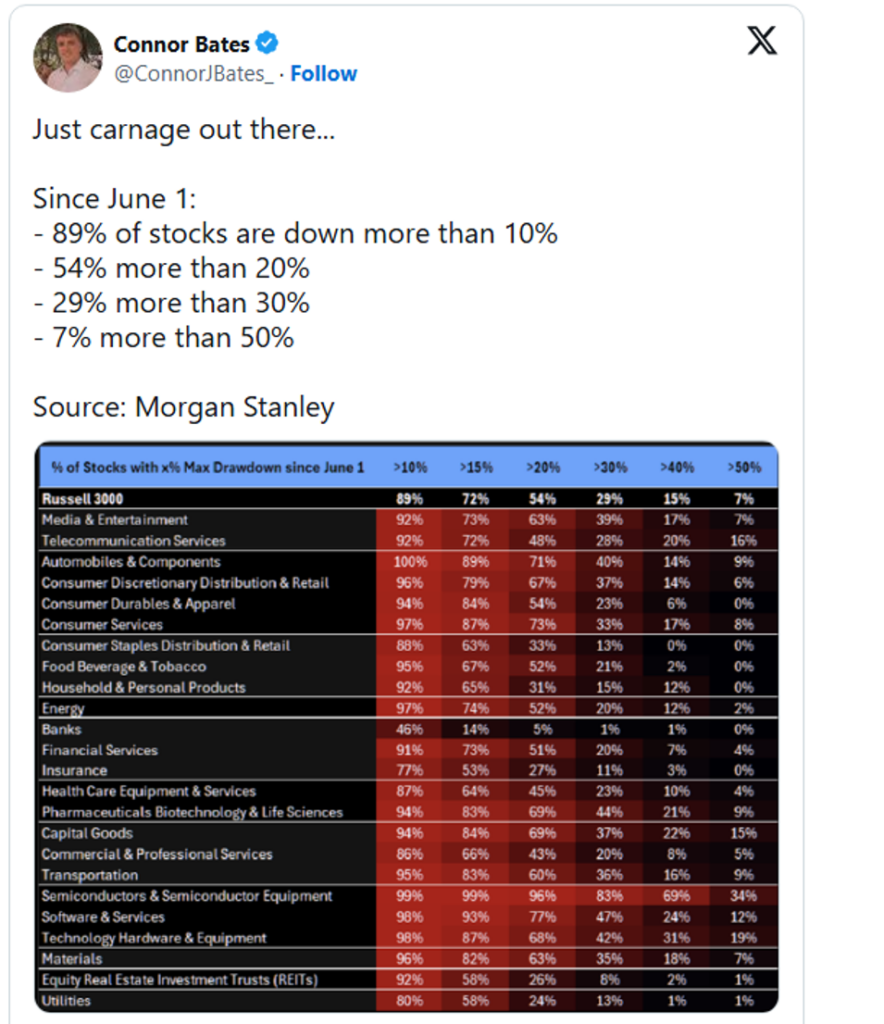
In addition, the major banks — including JPMorgan Chase & Co. ($JPM), Morgan Stanley ($MS), and Capital One ($COF) — are all in official correction territory, sporting declines of 11% to 25% from recent highs. Biotech, one of my favorite hunting grounds, has been a laggard as well with the State Street SPDR S&P Biotech ETF ($XBI) down some 13% from its highs in mid-August. Biotech M&A has ebbed since posting a sharp uptick in volume in the first half of 2026. Pacira BioSciences, Inc. ($PCRX), which I have a small holding within, was purchased with a solid buyout premium yesterday.
Trying once again to end the trading week on a positive note, today’s column will highlight two solid growth-at-a-reasonable-price plays within the biotech and biopharma sector. I have increased my position within each name this week via covered-call orders.
Let’s start with Arcutis Biotherapeutics, Inc. ($ARQT). This small-cap biopharma is not getting credit for a spate of positive news in this weak tape. Its pipeline-in-a-product, Zoryve now has Food and Drug Administration approval for seven conditions including atopic dermatitis and plaque psoriasis. Zoryve is a highly potent and selective phosphodiesterase-4 (PDE4) inhibitor and comes in a variety of foam and topical cream formulations.
Arcutis posted Q2 results in August that easily beat both top and bottom-line expectations. Revenues were up 59% on a year-over-year basis and 23% sequentially from Q1. Management also boosted its full year sales guidance from a range of $480 million to $495 million to $525 million to $540 million. The company is moving toward profitability with earnings of over 40 cents a share projected in fiscal 2026, followed by over $1.30 a share in fiscal 2027 and north of two bucks a share of profit estimated for fiscal 2028. At just over $24 a share, that growth has more than a reasonable valuation. Arcutis also possesses a rock-solid balance sheet.
I have also added to my stake in mid-cap BioMarin Pharmaceutical ($BMRN) as the shares are down some 20% from recent highs in mid-August. BMO Capital Markets noted that month the market’s worries around the potential market share erosion of its key asset Voxzogo is overstated and I concur.
BioMarin also just announced it will take an in-process research and development (IPR&D) expense of $283 million. This is tied to its recent purchase of Dutch biotech Alesta in August. It needs to be noted this is a one-time cost. The acquisition brought a candidate that is in mid-stage development for hypophosphatasia, which is a strategic fit for BioMarin’s rare disease pipeline and portfolio. The company easily beat the top and bottom-line consensus when it reported second quarter numbers in August.
Biomarin is one of the few stocks in the biotech sector or the market that has a price/earnings-to-growth ratio nicely under one, making it all the more attractive.
At the time of publication, Jensen was long ARQT, BMRN, PCRX and XBI
