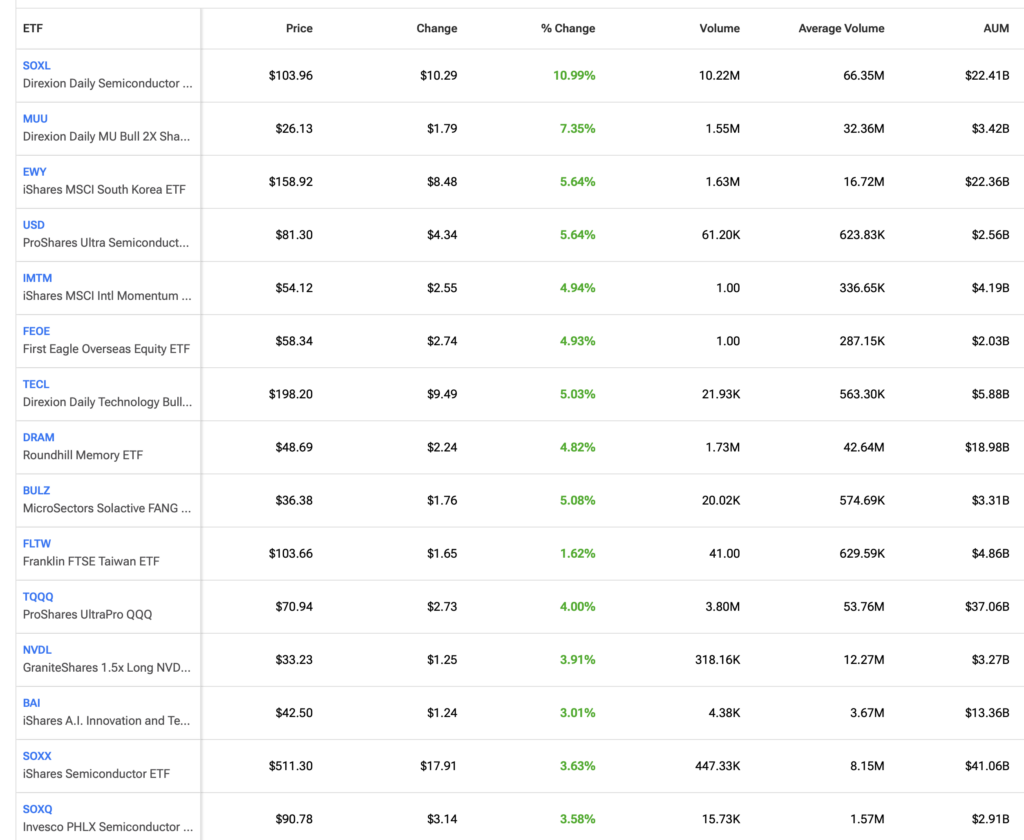
Charting the ETF Action in the A.M.

Source: TipRanks
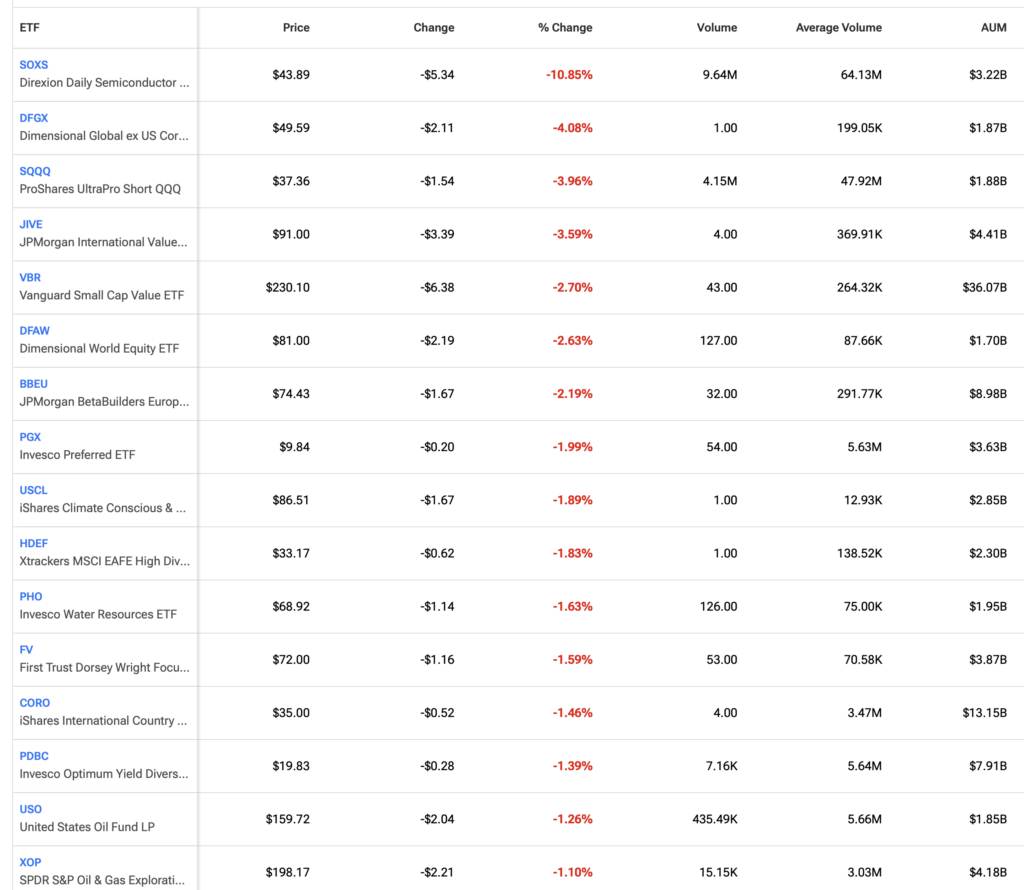
Source: TipRanks
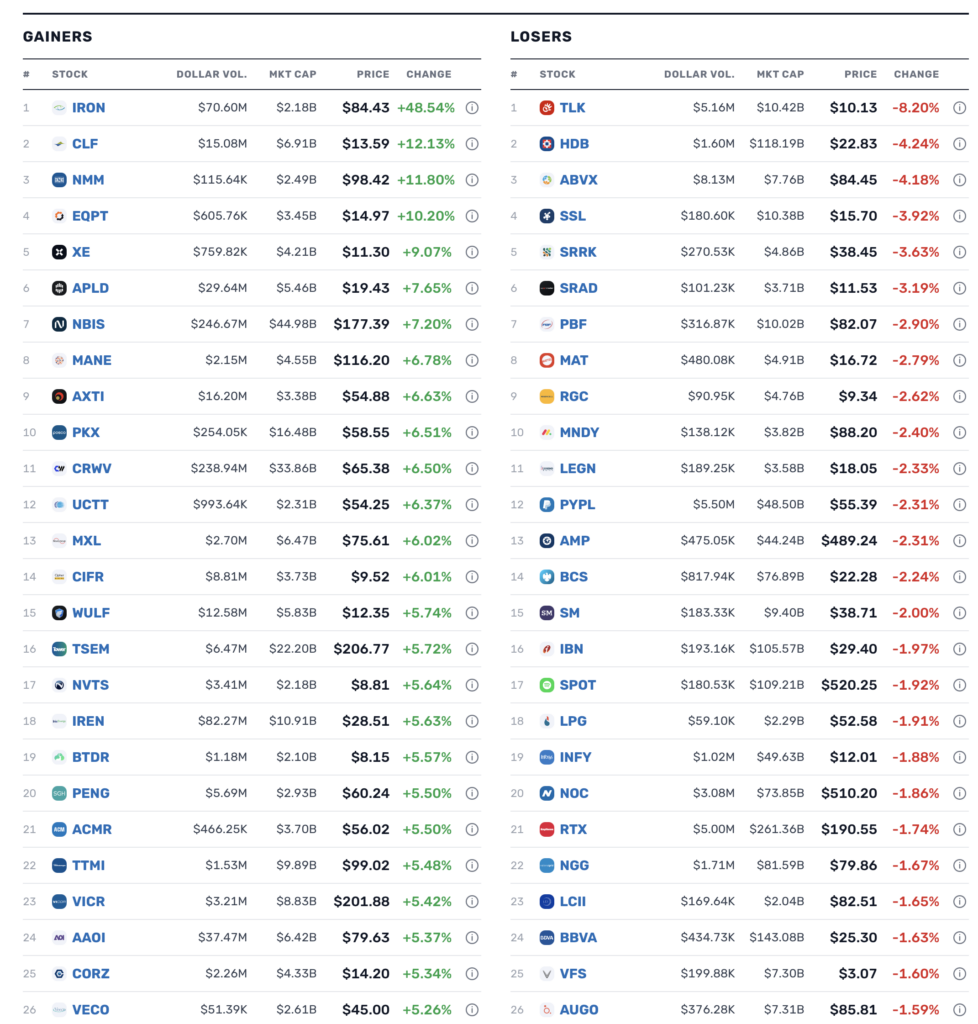
– $IRON +52% (Phase 3 APOLLO trial met all primary and secondary endpoints in erythropoietic protoporphyria)
– $AAME +41% (long-delayed 2025 annual report was filed, showing a return to annual profitability)
– $XLAB +24% (extends rally after securing an $8.2M AI-server order)
– $TCRT +20% (extends volatile rally tied to a proposed acquisition and financing of up to $350M)
– $MEDS +15% (extends rally after outlining peptide-compounding expansion and licensing a direct-to-consumer GLP-1 platform)
– $CLF +11% (Q3 profit and EBITDA beat expectations, Q4 EBITDA was guided higher and 2027 EBITDA is expected to exceed $4B)
– $NBIS +7.5%, $CRWV +7.7%, $BE +5.2%, $SMCI +4.1%, $IREN +5.9% (AI-infrastructure names rebound from last week’s financing-driven selloff as Treasury yields ease)
– $CRDO +4.7%, $TER +5.1%, $LRCX +4.6%, $AMD +3.7%, $MU +3.7%, $AVGO +3.1% (chip names rebound from last week’s AI-led selloff ahead of key sector earnings)
– $INTC +4.3% (JPMorgan upgrades to Neutral from Underweight as confidence in the turnaround improves)
– $VAI +4.0% (agrees to acquire an 18MW Ohio computing center)
– $DDOG +3.9% (Bernstein upgrades to Outperform and sharply raises its price target on stronger AI-consumption trends)
– $ACTU -9.1% (files to sell 40M shares with 20M warrants)
Microsoft walks on Nscale, food inflation poised to accelerate and other headlines moving the market this morning.
Source: TheStreet Pro
Source: TipRanks
Remembering Oct. 19, 1987; also an AI warning from Wall Street Journal and a check on the market’s charts.
“The monster – men made it, but they can’t control it.”
-John Steinbeck (hat tip Keith McCullough)
Someone knew.
Someone knew about the proposed Russian/U.S./Chinese Summit.
S&P futures opened -16 handles Sunday night at 6 PM and immediately rallied. At one point the E-minis were +65 handles and now have “settled in” at +37 handles.
The markets looked like we would have a dramatic Monday drop following Friday’s schmeissing (futures were trading lower throughout the weekend).
I remain bearish. However, as I mentioned on Friday, given the uncertainty of the markets and the news, the dominance of passive products and strategies (with machines and algos) that exaggerate short-term moves (they know everything about price and nothing about volume) coupled with what appears to be frequent leaks of policy I am limiting my index trading. When I do trade (on the short side) it is for very quick trades.
My comments of Friday remain very much intact:
* But more to the left!
The volatility of certain sectors demonstrated yesterday — particularly semiconductors and memory — is growing extreme and (to be honest) I am not sure what it portends for the near or intermediate term.
I do know when Micron (MU) trades down to $858 and closes at $931 (+$17 on the day) and Sandisk (SNDK) trades down to $1,276 and closes at $1,391 (-$12) such wide intraday swings render trading difficult to impossible.
This extreme intraday volatility has become routine in a market that now more resembles a casino than a capital market.
As would be said on “American Bandstand” — I give it a 78 I am not sure of the beat but it’s hard to dance to.
American Bandstand – Record Review Beatle Edition
This sort of extreme volatility likely indicates a lot of uncertainty and depending on your risk appetite and profile, most should pass on trading these stocks. And if you are trading the QQQs one might reconsider VAR (“value at risk’) and reducing the size of your trading (and investing) positions.
I know I am.
BY Doug Kass · Oct 16, 2026, 6:45 AM EDT
Position: None
Chip stocks are bouncing Monday morning, but AI valuations built on predicted earnings are being questioned.
The S&P Short Range Oscillator is back to neutral at -0.08% vs. 0.74%.
I have no positions in the indices.
Position: None
Semiconductors are part of a long list of stocks that are down. The good news is that so many are down that this might be good news for investors.