I have spent an extraordinary amount of time over the last two years analyzing AI — whether AI will really produce productivity, if the capital spending spree will generate a reasonable return on invested capital, etc.
The more than 260 “More Tales From Nvidia” columns I have written are literally the tip of the analytical iceberg. However, the nuts and bolts and intricacies of demand and supply, complicated chip pricing (e.g. rent for the H100 Index closed at $2.88 and rent for the more recent GPU8300 is at $7.65), the depreciation/”half life” of chips (GPUs depreciate in only 4-6 years but the underlying debt lives on much longer!), how soon will broad AI adoption take place and whether the “marginal” neoclouds should even exist (their cost of capital is too high and hyperscalers (Microsoft ($MSFT) and Google ($GOOGL) have been building data centers for more than two decades and in all likelihood they won’t ultimately need neocloud providers), would send your heads spinning and I would lose most of readers in the first paragraph.
As an aside, one of the reasons I am so critical of the business media’s superficial coverage of AI investing is that I am 100% certain that the AI knowledge base of the circus barkers recommending tech companies on Fin TV is miles long but only inches deep. They generally repeat glittering generalities and made-up Perma Bullish narratives that lack substance and analysis. (This observation also applies to the pied pipers Dan Ives and Tom Lee. No change in financing or fundamentals impedes their eternal optimism!)
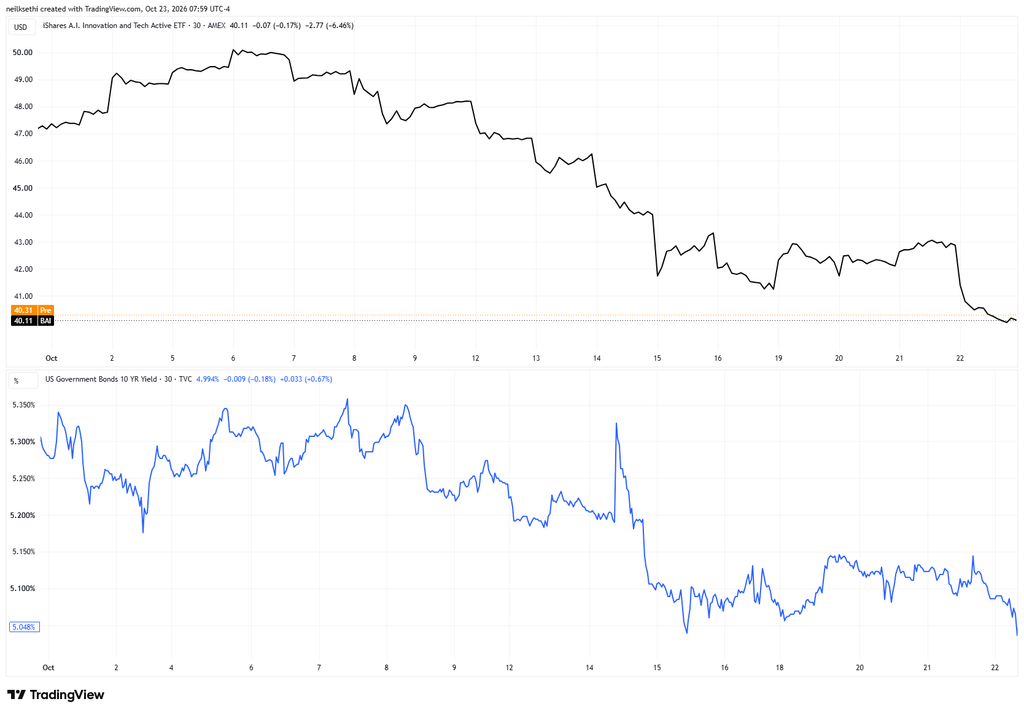
Below is from the firm Vital Knowledge — it is an excellent synthesis of what the ongoing and underlying problem is weighing on the AI situation.
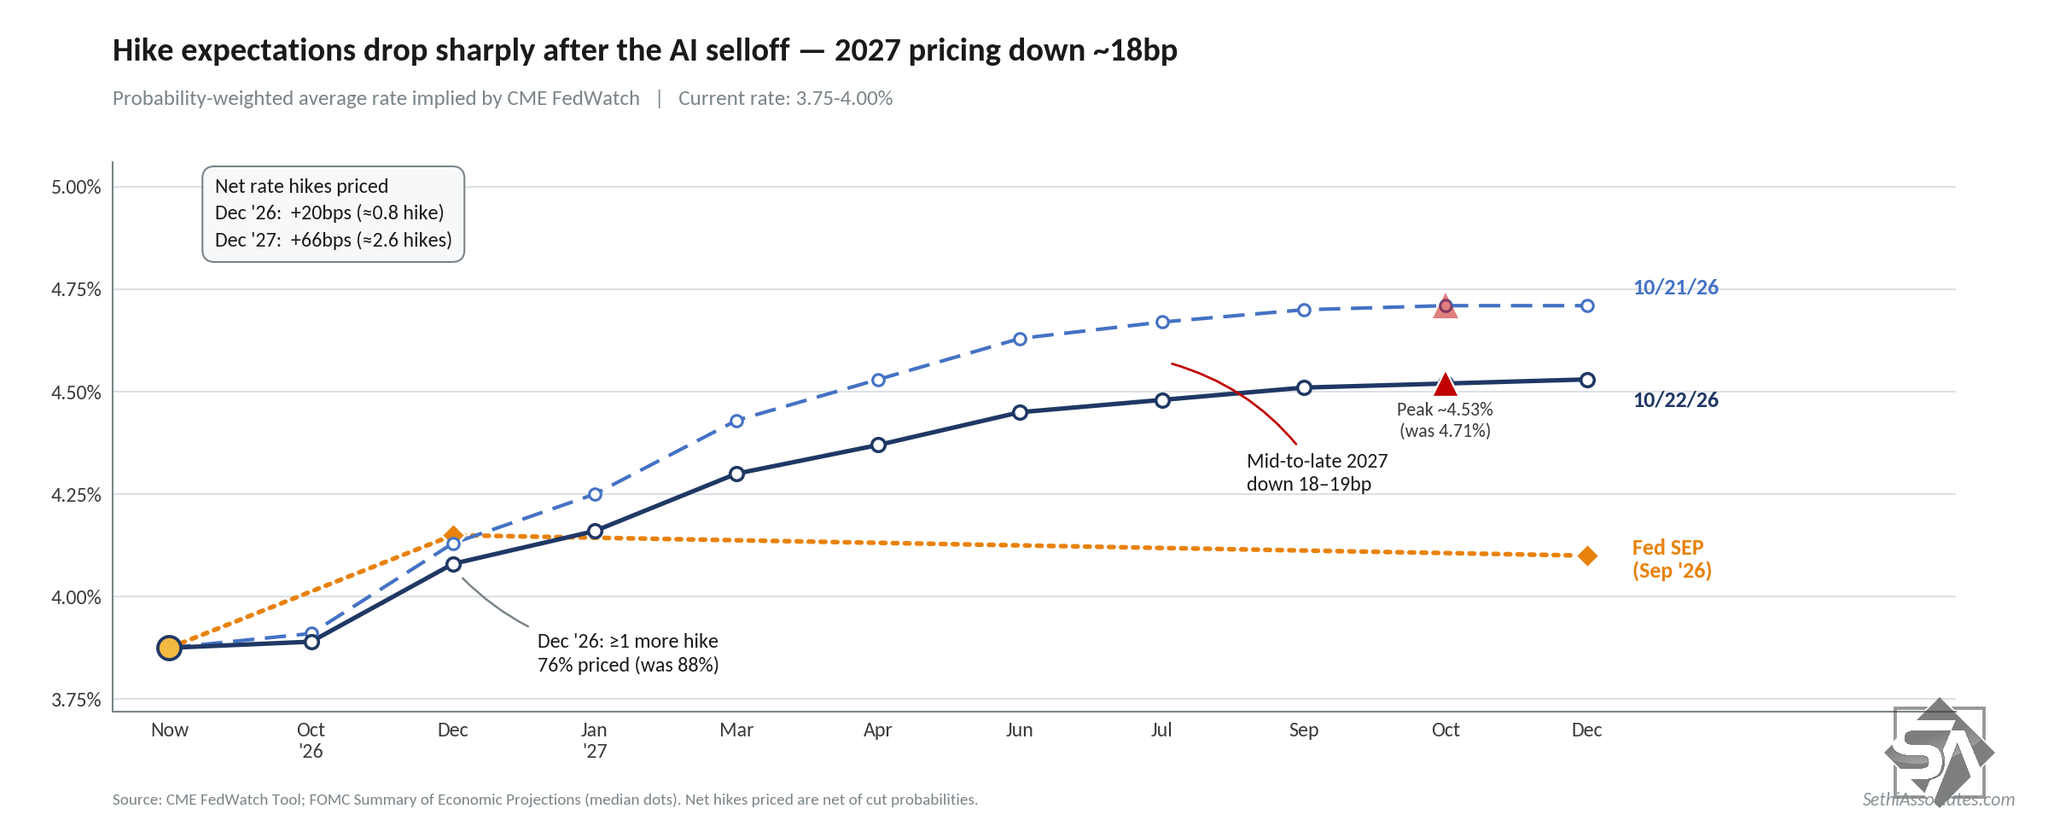
Amid all the noise around AI, the underlying problem for the industry is one that’s been present for a while: AI growth is dependent on capex (this is one of the most capital-intensive industries ever) and since capex is dramatically outpacing op. cash flow, companies are reliant on the largess of equity and debt investors to underwrite all the spending, but lately those markets are becoming increasingly less accommodating.
Because the issuance landscape for debt and equity has deteriorated materially, this will inevitably lead to a reduction in aggregate spending (the pool of capital willing to pay for everything is smaller than before, at least for now).
It used to be that investors could focus myopically on the big headline AI numbers (user growth, ARR, backlog, etc.), but that no longer suffices as these top line metrics are impossible to sustain/realize without funding, and that funding is now a lot more precarious.
The biggest players are putting the pedal to the metal, hoping to capitalize on the turmoil to squeeze (via crowding out) weaker vendors – this is why Musk talked about bringing 10GW+ of compute online next year for SpaceX while Meta tweaked up its 2026 capex budget and hinted at another huge number in 2027.
The argument can be made that this funding issue will soon pass because underlying demand is so strong, but it’s important to note that a lot of the demand is a function of that funding (i.e. loss-making companies are fueling a big chunk of token consumption).
It can’t be overstated how important Anthropic and OpenAI are – they remain the suns around which the whole AI world rotates and if these companies can’t come public on the terms anticipated by bulls (in terms of timing and valuations), there will be negative fallout for everyone due to 1) less money available to spend on compute and 2) a lower benchmark for sector valuations.
Compute is fungible, and the capacity being built for Anthropic/OpenAI could be repurposed over time if they don’t fill it, but that process won’t be quick or painless.
Position: None