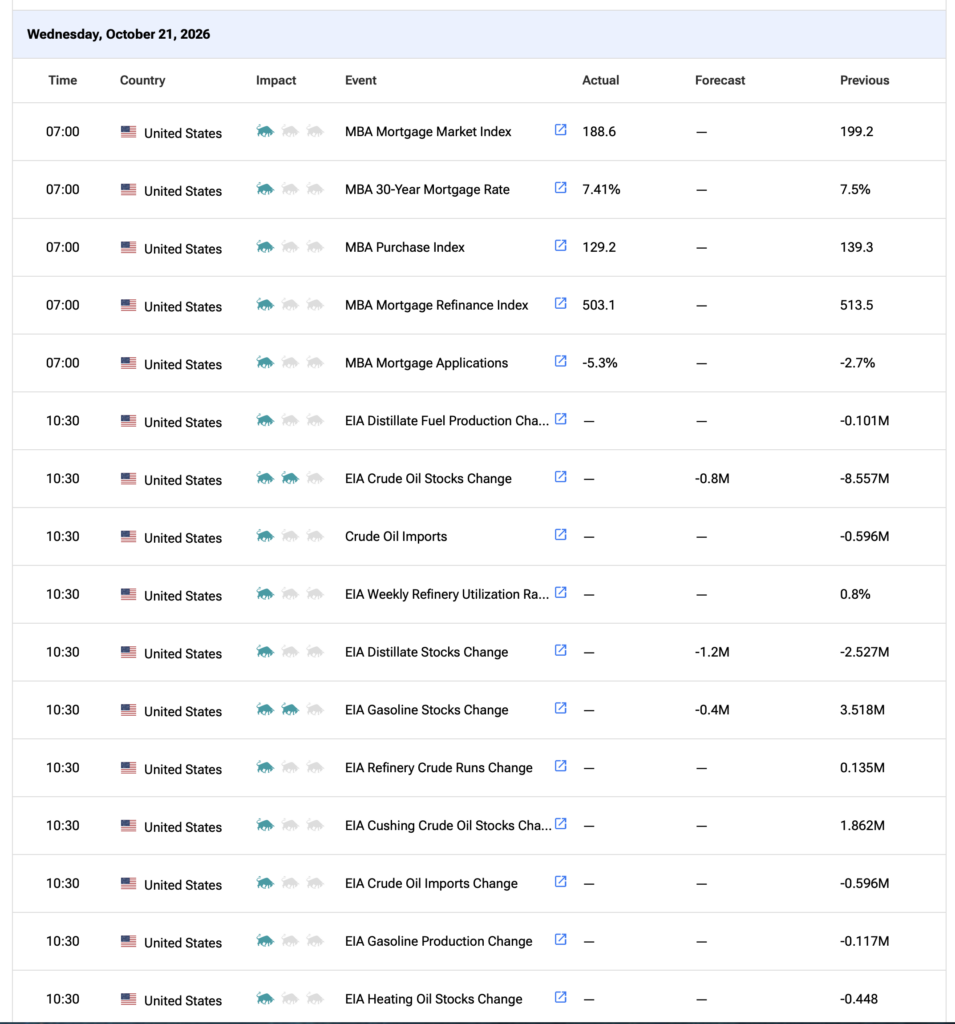
Economic Calendar Today

Source: TipRanks
Source: TipRanks
The SpaceX ($SPCX) quarter beat on revenue and EBITDA across all three segments (Intelligence/AI, Space, Connectivity). The only blemish was a miss on Starlink subscriber adds, offset by better pricing. Guidance calls for revenue of $33B to $37B by Q1 FY27. Management says it expects 2 to 3 GW of compute by year-end 2026 and plans to add 10 GW in 2027, well above prior expectations, and told JPMorgan it is not considering raising equity.
Price targets:
Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
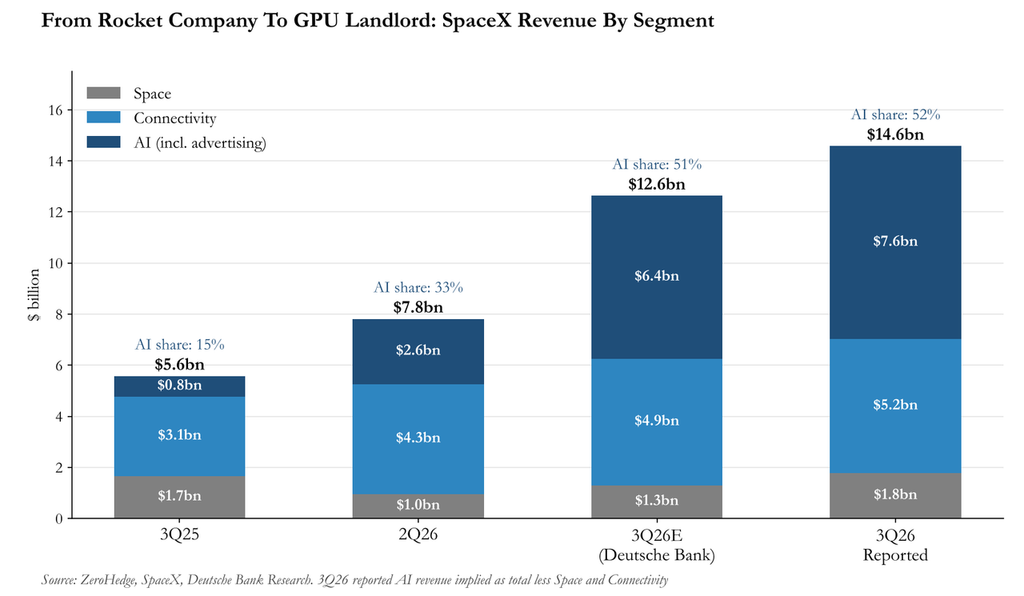
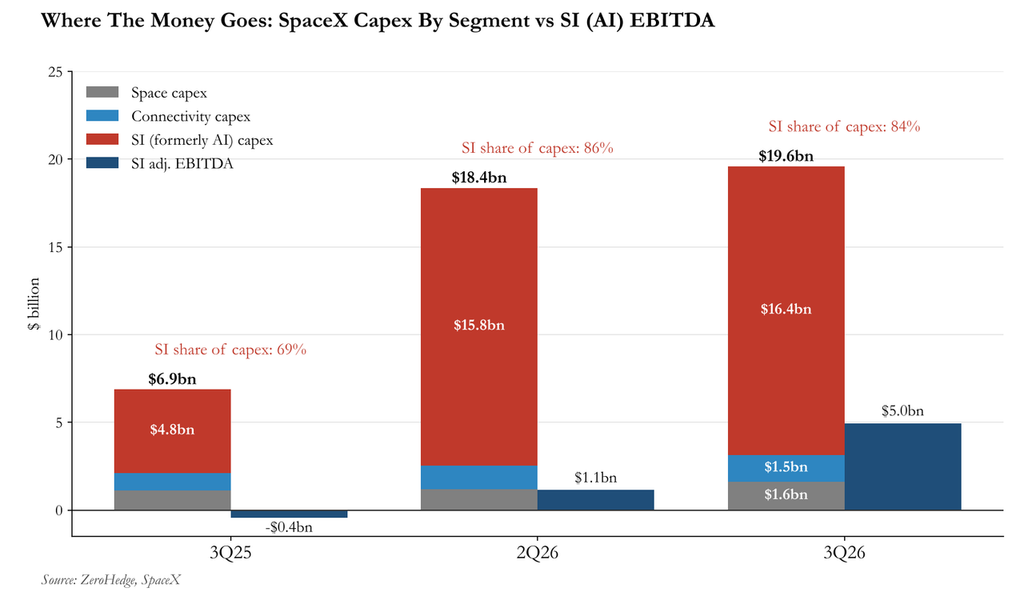
Below are two charts that speak volumes about the economics of AI.
SpaceX ($SPCX) just reported 3Q2026.
All of a sudden, AI (ergo data centers) is their biggest business. Along with that, cash and cash equivalents came in at $51.29 billion, versus an estimate of $91.2 billion. CAPEX for their AI segment was $16.4 billion versus $5 billion of EBITDA. Is this compelling?
I guess they can buy all the revenue they want; good thing the cost of financing it is so low??? Feels like double dilution is on the come here. Continued issuance to do whatever they are doing chasing WeWork landlord revenue, and dilution to potentially acquire Tesla ($TSLA), which is becoming more and more apparent.
Clearly Elon Musk wants to goose SPCX stock where he has much more of his net worth (~70%) to acquire TSLA (~25%) to hide it, on more favorable terms for SPCX (ergo himself).
This is the same trick Musk used when Tesla acquired Solar City. Hide the biz that can’t meet its promises, then to the next B.S. story.
Boy did that thing burn cash, holy heck, never seen a whiff this bad. Good thing borrowing costs are low these days. Oopsie:
In any case, at the rate AI is burning cash (and sucking down credit and equity), the 10-year Treasury will be yielding 6% in no time!
Position: None
Last quarter’s strong AI beats faded. Will it be different this time? Here’s my plan for SPCX.
Despite the protestations from the value cabal, I have been cautious on financials/banks all year:
Position: None
Fan fave Netflix ($NFLX) materially reduced forward guidance after the close of trading — and its shares are trading -$4 (or -6%) in premarket trading.
Here is the company’s release: FINAL-Q3-26-Shareholder-Letter.pdf
From my Diary yesterday afternoon and last night on Netflix:
Repeating for emphasis, I would not bottom fish in Netflix (NFLX).
I expect in line-to-better 2Q2026 results but a possible lower forward guidance as margins are pressured.
From last month:
I would continue to avoid buying (and “bottom fishing”) in Netflix (NFLX) for the reasons I have previously mentioned:
* Netflix has nearly saturated the domestic market (as well as many other developed countries). These markets are significantly more profitable than the non developed arena.
* Future Netflix sales/profit growth will come from developing country markets that provide substantially less revenue (and income) per subscriber.
* Netflix’s original content programming has been unspectacular over the last 12 months (or more) — and existing content has suffered.
In the past I have been short NFLX, but it is no longer priced as an attractive short.
Position: None
BY Doug Kass · Sep 22, 2026, 1:50 PM EDT
Position: None
BY Doug Kass · Oct 20, 2026, 4:09 PM EDT
Post Script:
Netflix, according to AI, was among the most recommended equities of the panelists on the “Show:” But viewers, in light of no timestamping or memorializing of recommendations, probably have no clue.
Though, as seen by my tweet above, I have stopped using X as a forum for my constructive criticism, I have a clue. Here is a recent recommendation of Netflix by one of the more particularly smug panelists seen on the Noon Show:
Trade Tracker: Steve Weiss buys more Netflix
We will likely never hear the name (Netflix) again from this particular panelist — or any of the others. As night follows day none of the panelists have modelled Netflix, spoken to management (and its competitors) or have performed any serious analysis.
Images and franchises are polished by panelists showing successful investment recommendations and not their conspicuous and frequent investment boners.
Instead the shows and panelists will likely all discuss SpaceX ($SPCX) today (whose shares are up by 6% after their EPS release)..
Position: None
Positon: None
But the magnitude of the selloff in precious metals doesn’t appear to be as substantial as many think based on the long-term chart of gold:
For now I am approaching $GLD as a “trading sardine” and not yet as an “investment.”
Position: None