Top-3 Takeaways After October Leads to Market Correction

As the calendar turns to November, taking a look at what the last month showed us about market conditions.
As the calendar turns to November, taking a look at what the last month showed us about market conditions.
ISM’s factory index rose to 55.5 in October, a tenth straight month of expansion.
S&P October final manufacturing PMI revised down to 54.9 from the 56.0 flash, easing from September’s 52-month high, but hiring was the strongest in 5 1/2 years while selling prices rose the most since September 2022 and delivery delays were the worst since August 2022.
A review of the ongoing technicals, oil questions and potential election results.
Let’s examine the responses to Alphabet’s and Amazon’s earnings and the other factors that led to last week’s ugliness. Also, a bright spot on the charts?
Investor’s Business Daily cut its suggested exposure to 0% to 20%. The indexes are weak, but money is moving into the stocks that were left behind.
The growth stocks of yesteryear are being ignored by traders today. The singular focus on tech has caused them to miss out on great opportunities.
The rotation out of Tech continued last week. Now a packed week headlined by Apple on Monday, Tuesday’s midterm elections, and Friday’s jobs report test a market with thin gamma and CTAs near their sell triggers.
Breaches of discipline are inevitable, so let’s get to the core of the problem and ways to fix it.
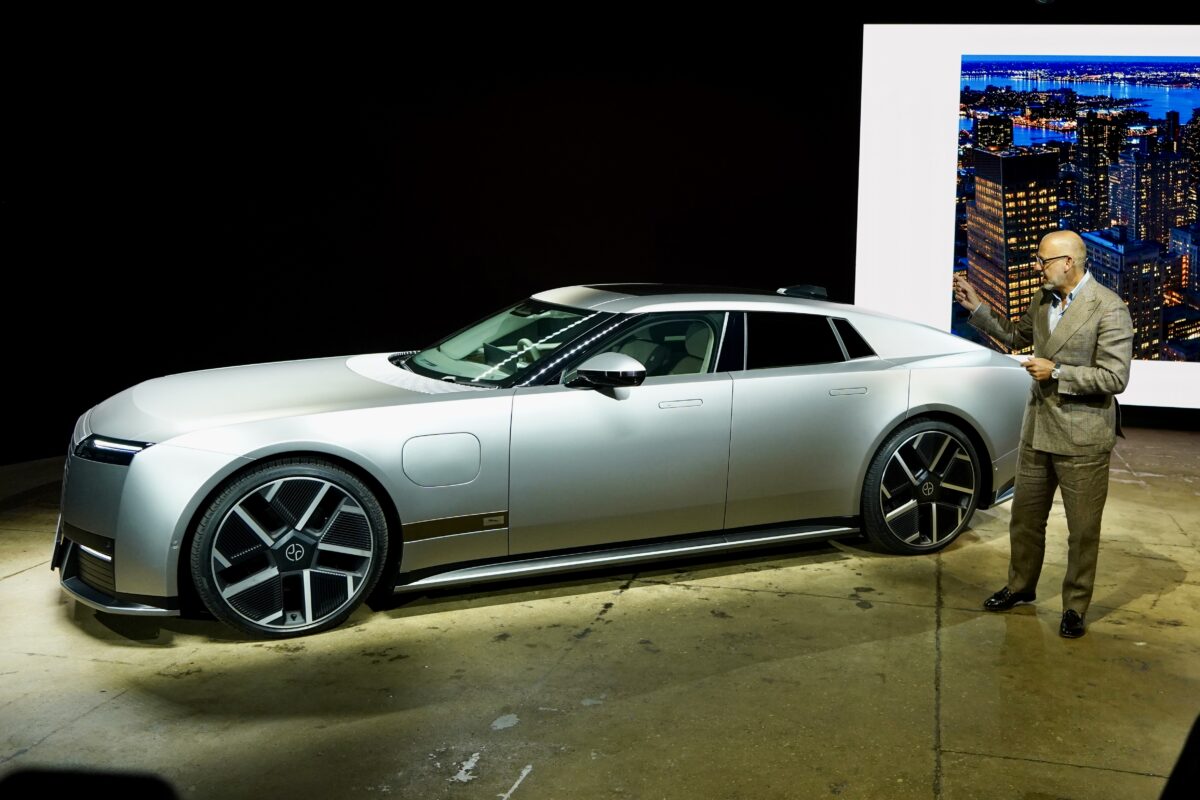
The Type 01 represents more than a product launch. It’s a test of whether luxury, differentiation, and brand identity can withstand China’s growing dominance.