Boockvar Speaks on the ‘Pas Bon’ French Bonds, Earnings

The following is from Peter Boockvar:
Pas bon, ‘not good’ in French/What Meta said, along with other earnings comments
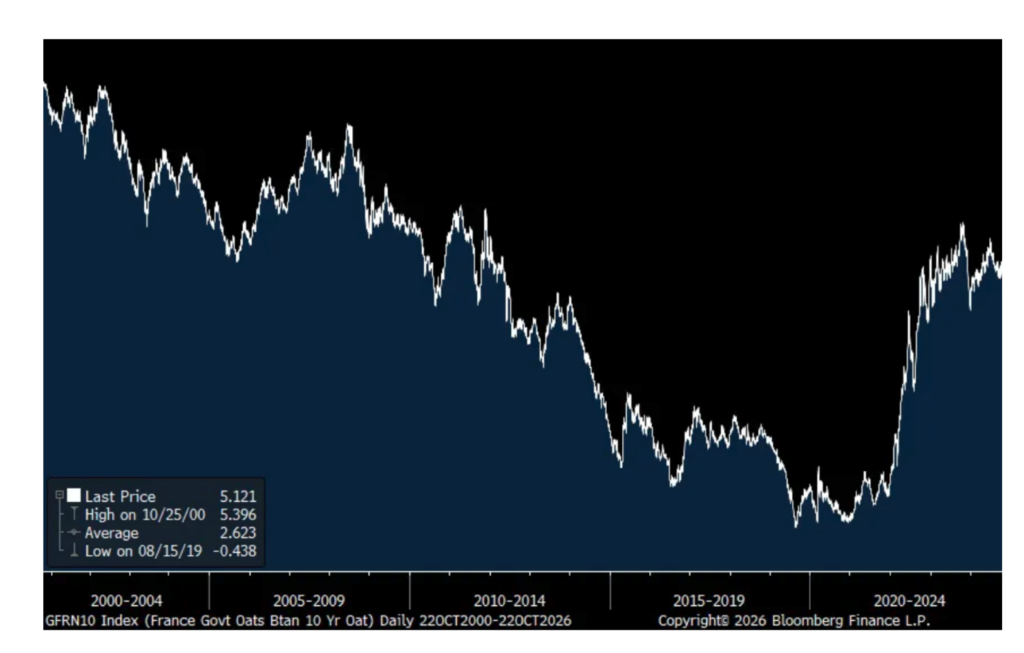
Before I get to a bunch of earnings calls, I do want to point out that French yields are jumping again with the 10 yr yield higher by 11 bps and by 32 bps this week alone. German bunds and US Treasuries are the flight to safety trade in the face of this, for now. I continue to believe that at least in the short term, yields in the US have seen a temporary peak.
French 10 yr Yield
Carrefour stock by the way got hit by 14% yesterday as they revealed the extent of the loss of business they’ve experienced in France with all the riots and theft. They said:
“Thousands of stores across France were attacked, products robbed, and for some stores, equipment was destroyed…Around 50 of our stores were hit on day one. Many were looted, and the damage is considerable.”
Also, “The direct costs are only part of the impact. Stores that were not physically damaged are also affected. Lower customer footfall in many areas, shorter opening hours because of curfews, precautionary closures, and access difficulties are disrupting trading. This is continuing in some areas at the beginning of this week.”
“Going forward, we will have to increase our operating costs, notably in areas such as security and specific logistics for damaged stores.”
Staying in France, and I don’t believe the survey period included last weekend’s violence, French business confidence in October rose 1 pt after falling by 2 last week. The manufacturing recovery led the way as we know it is global. The rest of the picture was mixed as services rose 1 pt but retail, employment and building construction confidence all fell.
To the global recovery in manufacturing, the October UK CBI industrial orders index rose 9 pts m/o/m and CBI said “There are growing signs of stabilization for manufacturers, with firms expecting a prolonged period of falling output to come to an end in the coming months and anticipating their first increase in headcount in two years.”
The caveat though, “orders are still falling and labor shortages picking up, significant challenges remain. Stubbornly high costs are also squeezing profitability, while deteriorating competitiveness and fragile business confidence continue to weigh on investment decisions.”
While Meta basically maintained its CapEx forecast by narrowing the expected range to $135b-$145b from $130b-$145b previously, it seemed like it was this comment from the CFO on the call that turned the tide for the stock and the broader S&P futures. Susan Li said of note:
“Muse’s compute intensity means that expanding its user base will require significant investment, and we expect total serving costs to rise.”
And, “Looking beyond 2026, we are still developing our budget and capacity plans for next year, but we expect to continue investing aggressively to support both our core business and emerging AI initiatives.”
Otherwise, Meta seemed to have a solid quarter with an incredible 26% revenue growth rate on top of such a large base. And “The global average price per ad increased 14% y/o/y, driven by ad performance gains and improvements in macro conditions relative to Q3 of last year.”
Zuckerberg said “we are seeing all-time highs in engagement on both Facebook and Instagram, driven by strong growth in video. Threads has now overtaken X in monthly actives and continues to grow quickly. WhatsApp is hitting all-time highs in messaging and is becoming an increasingly important platform for agents as well.”
With Muse, “In just a month and a half, more than 10 million people in the US and Canada have set up Muse personal agents. Growth continues to be strong, and we have been number one in the App Store almost every day…Beyond shopping, the most common connectors are for personal productivity and connecting Muse to your other services like email and calendar.”
The issue, back to the first point, is the huge level of spend that resulted in negative free cash flow of $2.1 billion.
On the other hand, Tesla is down because people seem disappointed that they are cutting its CapEx guide this year to $20b from $25b “as a result of managing our capital deployment efficiently and plan to fund it primarily from our cash flows from operations. Additionally, during the quarter, we secured capacity to borrow up to $30 billion to support the expected growth in CapEx.”
Spending though will still rise in the coming years “as we add more Robotaxi fleet, we expand our production capacity for Optimus, install manufacturing capacity for solar, purchase additional SI (Super Intelligence) compute infrastructure, and build a semiconductor fab.”
In the more pedestrian business of flying people around on a plane rather than a car, this was from United Airlines where we know travel remains a priority of consumer spend, notwithstanding the rising prices:
“I’ve been pleasantly surprised at the industry’s ability this year to raise yields and pass through much of the increase in fuel prices…Consumers and businesses have been accepting price increases, which we believe is a result of fares lagging the rest of inflation, along with other aspects of travel costs, for many years.”
“I think it’s important to note that while pricing has gone up a lot this year, it is still down in real terms compared to 2019. So we are bouncing still off a Covid low. And air travel remains a great value.” So I guess, we’ll be paying even higher prices in the quarters to come.
Premium cabin was strong but also “it was nice to see standard economy cabin RASMs up.” Business revenue rose 22% and contracted business revenues were up by 26%. Leisure revenue was higher by 16%, “with stronger y/o/y yield gains than business traffic.”
Of note, “Leisure load factor fell modestly by 1.3 points, which we view a small amount of elasticity given higher ticket prices, a trade we would make every day.”
With container ocean shipping prices having risen sharply, cargo revenues rose 23% y/o/y.
Higher fuel prices added $1.8b to expenses y/o/y and they “recaptured 72% of the increase” and expect that to rise to 100%.
Back to the high tech stuff, this was from Texas Instruments, little changed pre-market:
“During the quarter we saw broad demand, with revenue growth across all end markets and regions. Secular growth of semiconductor content is continuing alongside a strong cyclical recovery.”
Their three main markets are industrial, automotive and data center and “we are seeing the broadening of the demand across” these sectors. Not surprisingly, “The data center market, it’s a market that we see strong secular growth. I don’t think it’s influenced by seasonality. The demand continues to be strong and growing.”
With industrial, they are seeing particular strength in “aerospace & defense, energy infrastructure, test & measurement, the robotics sector.”
“We also saw the automotive customers waking up, if you will, with higher demand in Q3, and I think that may continue into Q4.”
Overall volume was good “but we also did have some benefit from pricing, loadings and some product and end market mix.”
On the consumer, Winnebago stock jumped 11% yesterday even though business is still tough for this higher ticket segment and said this of note on their call:
“consumer interest in the RV and boating lifestyle remains healthy with continued engagement across shows, digital channels, campgrounds, marinas and the used market. At the same time, affordability pressures, elevated financing costs and broader macroeconomic uncertainty continue to weigh on consumers and delay the conversion of that interest into new product purchases.”
“That caution is also reflected in dealer ordering, with dealers continuing to manage inventory carefully.”
Looking to the next fiscal year, “Our outlook does not assume a broad recovery in RV or marine retail demand.” They believe more in their self help on product, market share, costs and other efficiencies.
