Boockvar on September CPI and More

From Peter Boockvar:
CPI data/Mortgage apps
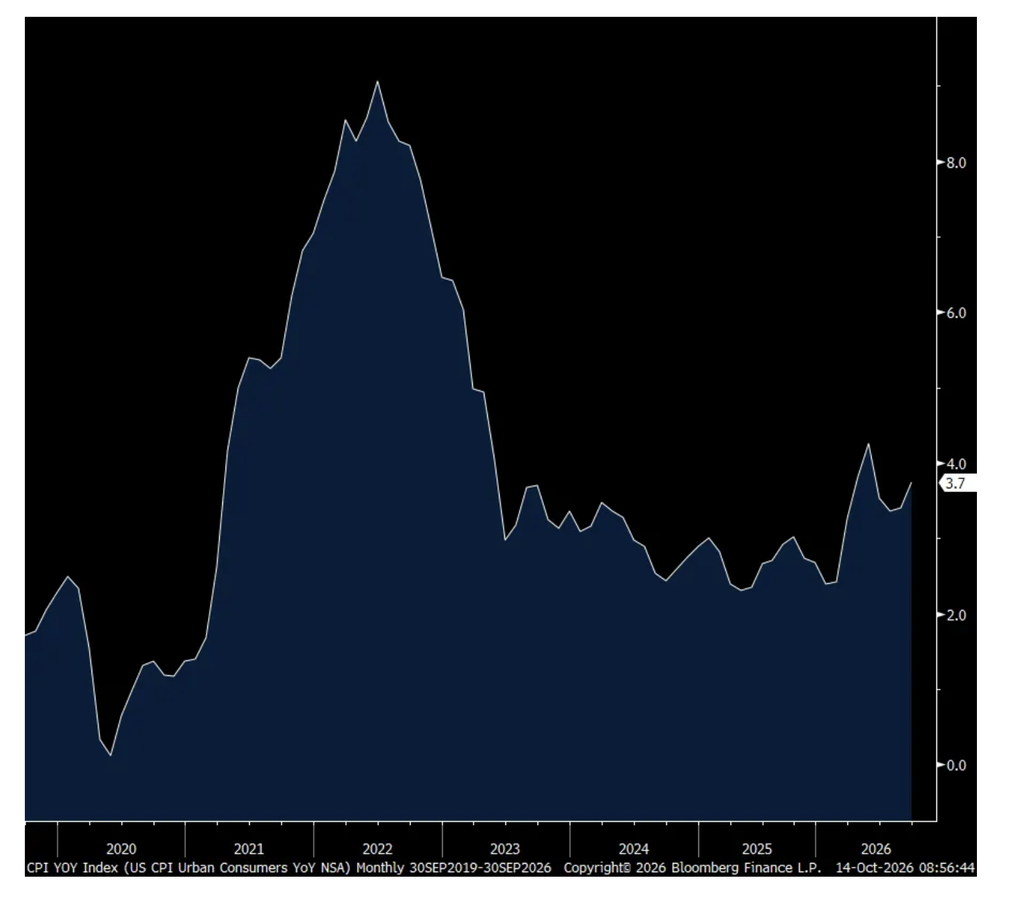
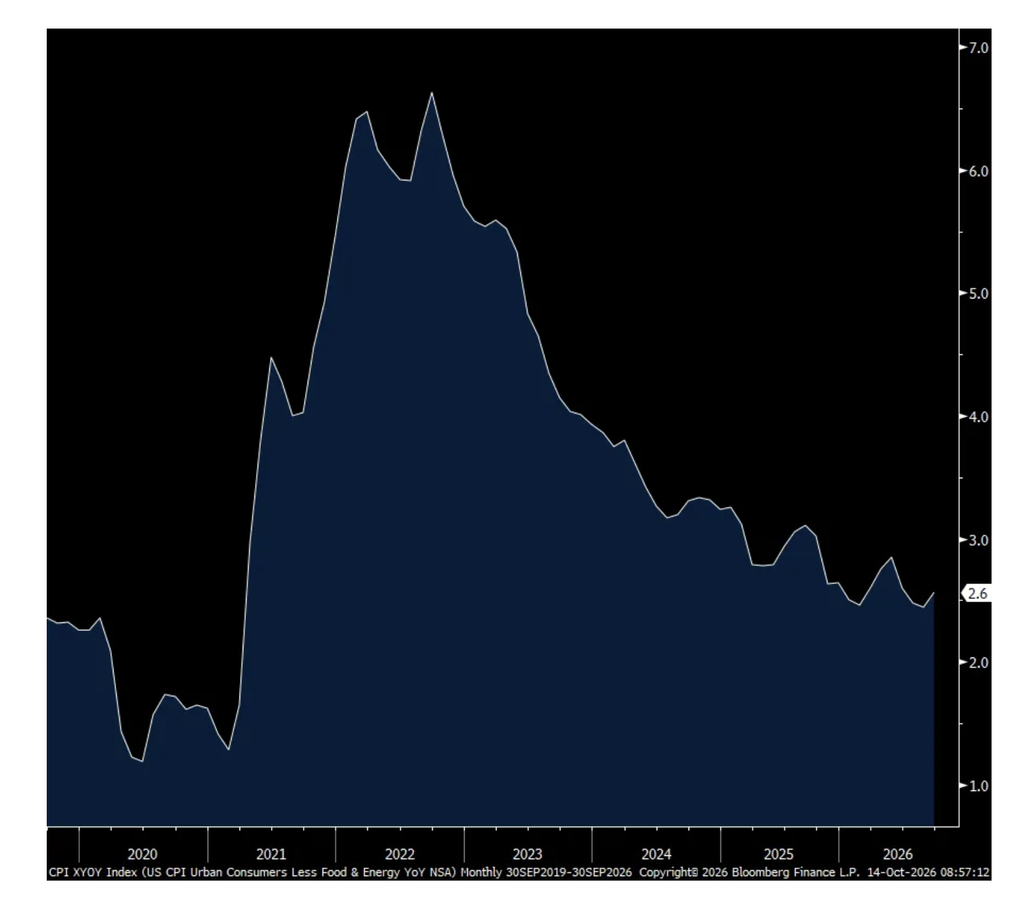
The September CPI rose .6% m/o/m headline and .3% core with the former as expected and the latter one tenth above the forecast and after .4% and .3% gains in the month before. The y/o/y gains are now 3.7% and 2.6% vs 3.4% and 2.4% respectively in August. While I DO NOT like taking out components to get to the inflation read people want, I’ll include this here because people watch, CPI ex food, energy and shelter rose .3% m/o/m for a 3rd month but spot on 2% y/o/y.
Energy commodities, driven by fuel oil and gasoline (all types), jumped 9.3% in the month and higher by 35% y/o/y. Within energy services, electricity prices in particular rose .2% m/o/m and 4.4% y/o/y.
Food prices saw no change in price m/o/m but up 2.5% y/o/y. ‘Food at home’ saw prices down .1% m/o/m and moderating to up 1.8% y/o/y. ‘Food away from home’ is still where more of the inflation is with prices rising .2% m/o/m and 3.5% y/o/y. Beef prices in particular seem to be cooling, with prices down for a 3rd month. As people have shifted to chicken though resulted in prices here up 1.3% in the month.
Services inflation ex energy was higher by .4% m/o/m and 3.1% y/o/y mostly driven by rents. OER was up by .3% m/o/m and 3.3% y/o/y. Rent of Primary Residence was up .2% m/o/m and 2.8% y/o/y. These are much closer now to reality, when looking at blended rents from the publicly traded REITs. Medical care costs rose just .1% m/o/m and 1.5% y/o/y. Nowhere near reality, the BLS said health insurance costs were down by .2% and lower by 9% y/o/y. Elsewhere of note within services, airline fares continued to jump robustly, up 1.2% m/o/m and 22.4% y/o/y. Hotel prices too were much higher, rising by 2.3% m/o/m and 4.3% y/o/y. Vehicle maintenance costs remain hot, up .7% m/o/m and 5.8% y/o/y. Car insurance prices continued to cool, up just .1% m/o/m after a string of declines and lower by 5% y/o/y.
Core goods prices rose .3% m/o/m, a pick up from recent months, though up just .7% y/o/y. Higher used car prices helped to drive the increase, up by .7% m/o/m in the month after .4% gains in the prior two months, though still down 1.5% y/o/y. For new cars, prices rose .2% m/o/m and by .6% y/o/y. Apparel prices, in the key back to school month, along with August, rose .3% m/o/m and 3.4% y/o/y and still likely seeing tariff related pass throughs (as it gets staggered out rather than all at once). On the flip side, ‘medical care commodity’ prices fell .7% m/o/m and by 3.3% y/o/y. Prices of household furnishings/supplies fell .2% m/o/m and up .2% y/o/y.
Of note too on the goods side, the skyrocketing cost of memory components led to a 1.4% m/o/m rise in price for ‘personal computers/peripheral equipment and up 9.7% y/o/y. For ‘computer software/accessories’, prices were up .4% m/o/m and 28% y/o/y.
Bottom line, I’ll argue again that 3-4% headline inflation remains the new 1-2% and the persistency of price gains continues and certainly on the business side which we’ll see with tomorrow’s PPI which is running even hotter than CPI.
The market response was swift with that one tenth core upside. The 2 yr yield is higher by a large 15 bps vs 8:29am est. The 10 yr yield has jumped by 11 bps and the 30 yr by 7 bps. The 2 yr inflation breakeven is higher by 10 bps to 2.62% and the 5 yr by 4 bps to 2.4%.
As for October rate hike odds, they’ve about doubled in response from 22% to 50% and if they don’t in October, there’s a 96% chance they do in December.
Headline CPI y/o/y
Core CPI y/o/y
Separately, with the average 30 yr mortgage rate at 7.5%, mortgage apps to buy a home fell by another 4% w/o/w and down 16% y/o/y. Refi’s fell only slightly but after dropping sharply over the past month and are down 56% y/o/y.
Position: None
