Boockvar on Looming Earnings, that Economist Mag, Transport

The following is from Peter Boockvar
Know who butters your bread/The Economist mag cover/Transportation
As we are about to get hit by a bunch of bank earnings and to be followed by the earnings flood to follow, it’s important to know what is driving most of the expected 30% increase in Q3 y/o/y earnings growth. According to LSEG (London Stock Exchange Group), about 2/3rds of that growth is coming from tech stocks, along with Meta, Alphabet and Amazon. About 1/3 of the 30% alone is coming from just two companies, Micron and Nvidia. Semis in total are expected to see earnings growth of about 150%. Energy earnings will also be a contributor with earnings expected up about 115% y/o/y but that is only about 3% of the S&P 500.
I’d say overall, outside of the quality of both revenue and earnings, the most relevant aspect for the AI trade to me will be the updated info on the CapEx plans of the 5 big hyperscalers.
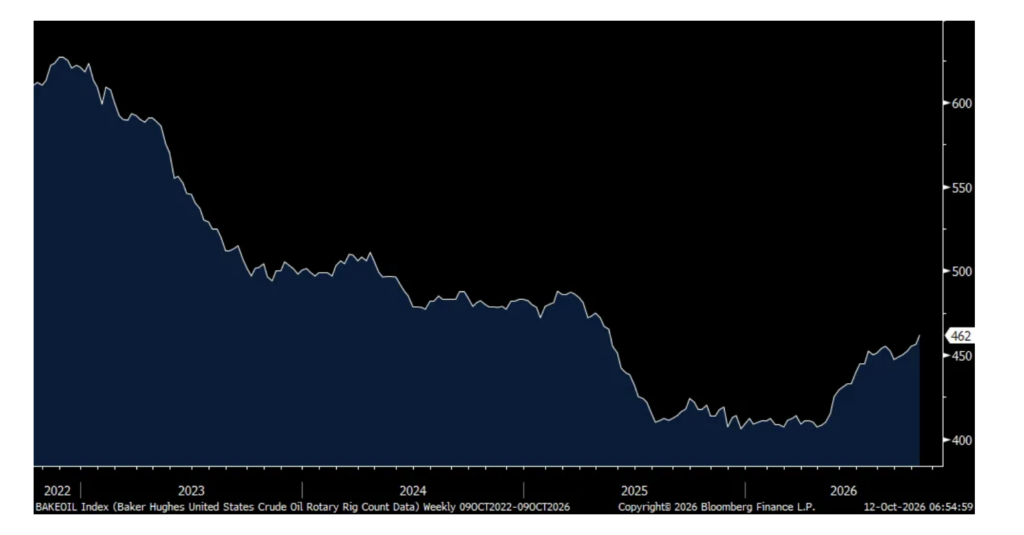
Speaking of energy earnings, I wanted to point out that the crude oil rig count in the US continues to tick higher (we’re long an oil service stock and an offshore drilling rig stock as a beneficiary, among other energy holdings) and sits at its highest since May 2025, though at 462, up 6 on the week, remains well below the over 600 it was at in 2022.
Crude Oil Rig Count
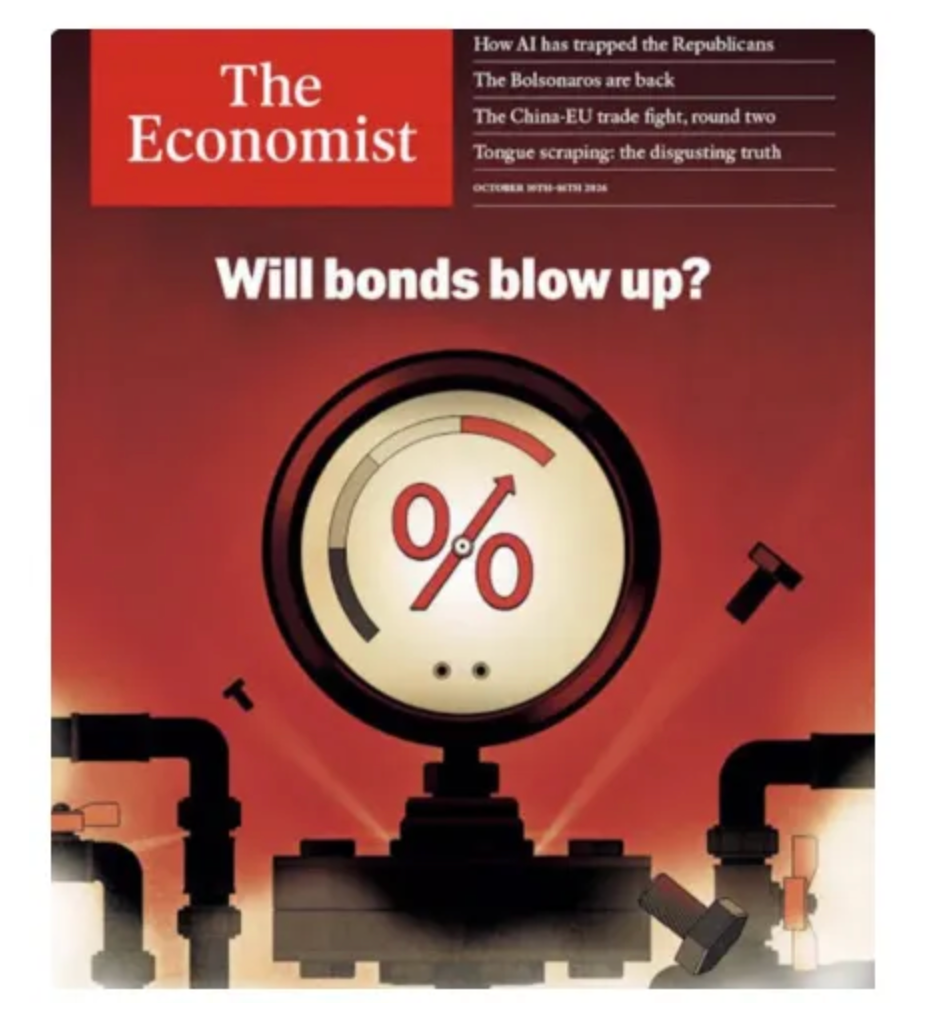
I’ve been an expressed bear here on long duration bonds for years now but in the short term I think maybe we’ve seen a temporary peak in yields. This is not because I see a change in the fundamentals that have taken us here but on the belief that sentiment has likely gotten too bearish in the short term. Also, whenever I see The Economist with a front page story, it typically pays to go the other way. H/t to my good friend David Rosenberg for this reminder:
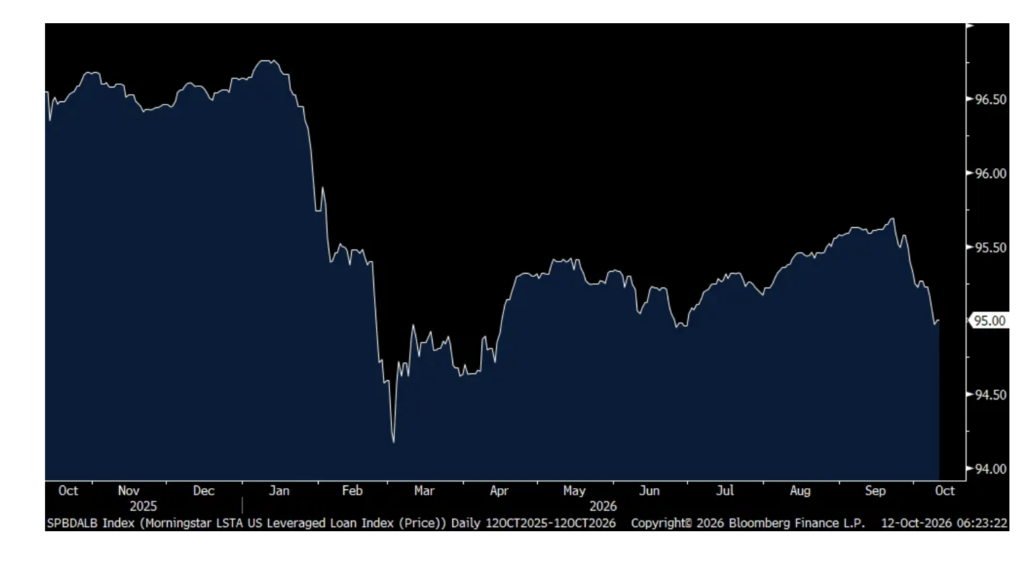
The close eye though still remains on corporate credit as a rate shock is still coming for those that have debt coming due that was priced prior to 2022 or is looking to pencil out a fresh deal. The LSTA leveraged loan index closed Friday at just off the lowest level since late June at $.95 on the dollar.
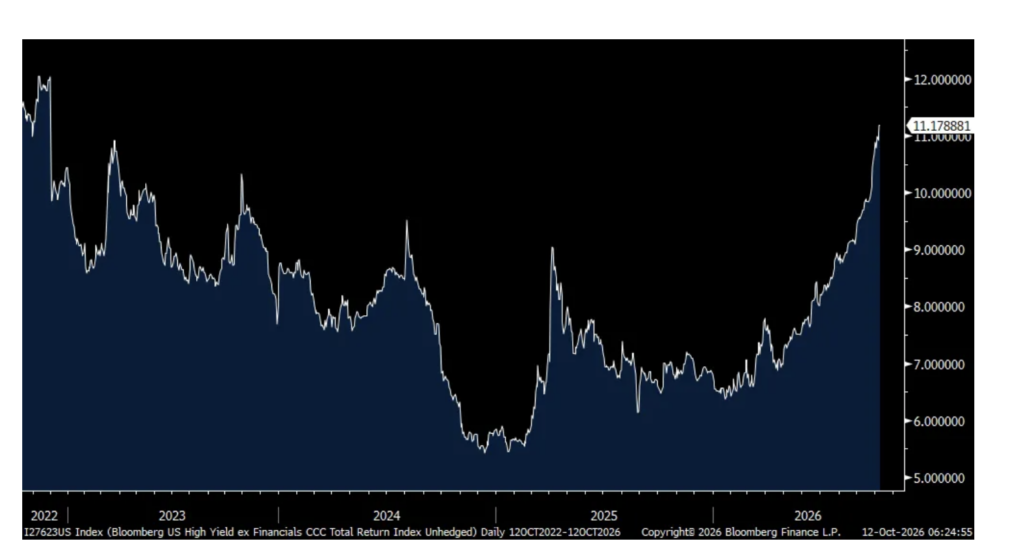
I keep talking about the CCC category and last week its spread to Treasuries rose above 1100 bps, the most since November 2022 and with a yield to worst of now 15.5%.
LSTA
CCC Credit Spread
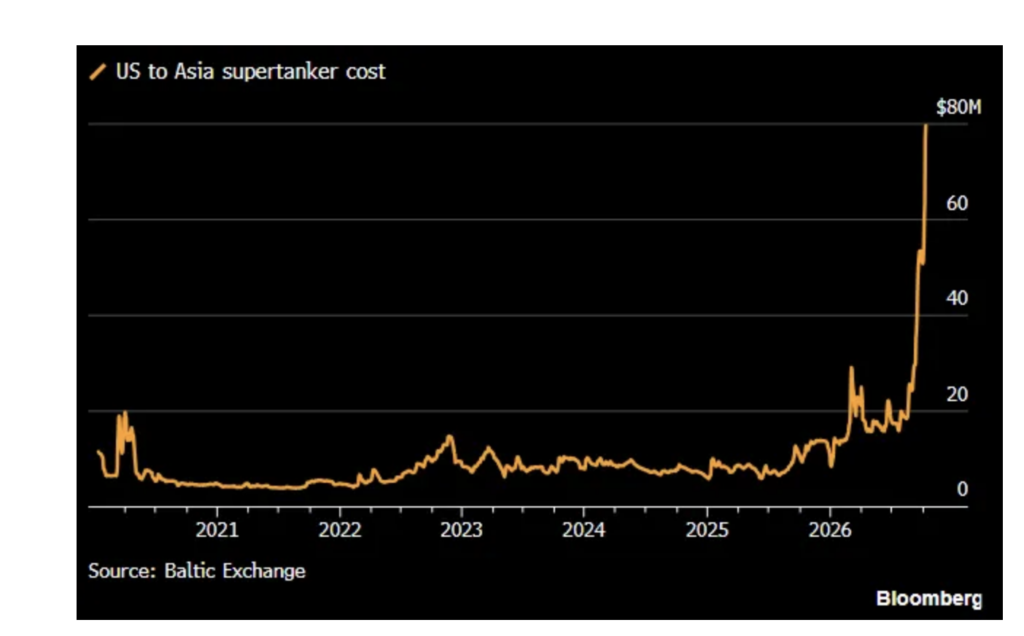
I’m going to mention again the story going on in shipping and adding the astronomical costs now of transiting a ship of crude oil. The cost of an oil tanker is now about $80 million. That compares with about $5-10 million before the war. That alone adds about $40 to the price of a barrel of oil. For further perspective, the total cost of originally buying the ship might have been only about $80 million. Quite the cash on cash return right now.
On the trucking side, I saw this article from FreightWaves Friday titled: “Trucking Rates Spike: Contract Rates at 52-Week High.” From them:
“Contract truckload rates have climbed to a 52-week high of $2.72 per mile plus fuel, up 18% year over year, as carriers and shippers reset agreements at elevated levels, according to FreightWaves SONAR data presented in an Oct. 9 market update.”
More, “The move in contract rates matters because it signals that shippers are no longer holding the line on legacy pricing. With spot rates also rising — the NTI index is up nearly 50% year over year — the gap between contract and spot is narrowing, giving carriers leverage as annual bids roll over.”
When it comes to leisure and business travel, this was from Delta’s earnings call Friday and whose stock rebounded as the day progressed and closed unchanged:
“Looking at the current environment, demand remains strong, supported by a secular shift in consumer behavior. The top 40% of households, which make up the majority of Delta’s customer base are nearly $40 trillion wealthier than they were just a few years ago and increasingly prioritizing experiences, including travel. At the same time, air travel remains one of the best values in the consumer economy with airfare still well below cumulative inflation over the last several years. That demand is evident across leisure and business travel and across all cabins.”
“Premium growth remains robust and main cabin trends are continuing to improve, reflecting our measured approach to growth and broader industry actions to reduce unprofitable capacity.”
It is this ‘wealth’ increase reason why they think the price increases they are implementing, in response to higher fuel prices and less capacity growth, will stick.
With the business customer, “The week after Labor Day was the highest corporate sales week in our history, underscoring the strength of business travel.”
Overall, “With seat growth below 2%, including a y/o/y reduction in main cabin seats, our capacity positioning supports another sequential improvement in unit revenue growth as we continue to cover higher costs.”
By the way, by owning their own refinery, they saved themselves about $700 million but still paid out $6 billion more in fuel expenses this year.
What Delta is saying is highlighting how much of upper income spend is a byproduct of the high level of the stock market, along with home prices. They are intertwined and we know the stock market is being almost solely driven by the extraordinary CapEx spend to create profitable GenAI products and services. Thus, to say again, the US economy and stock market is essentially All In on this massive CapEx binge.
