Boockvar on Hike Chances, Nike, Overseas Inflation

The following is from Peter Boockvar:
No hike in October/I believe/Overseas inflation stats
With regards to the jobs data today, I’m most focused on the breadth of job gains. Will we see more hires outside of just construction, healthcare and leisure/hospitality?
I attribute the reversal higher yesterday in Treasuries/lower in yields to the German bund rally intraday where bunds became a safety trade as French and Italian bonds were selling off. That then shifted to US Treasuries. You’re seeing it again today, German bund yields lower by 8 bps after the 8 bps drop yesterday while French and Italian yields, while flat today, remain at their lows.
The Fed is not going to hike in rates in October and add Michelle Bowman and Vice Chair Jefferson to the list of Fed voting members, John Williams was the first, telling us so. Bowman late yesterday said “I don’t currently see an urgent need for further action, and I think we need to better understand the totality of the data, but remain attentive to the risks.”
This followed Philip Jefferson who said “As we look ahead, my view is that any future adjustments in policy should be determined by carefully examining trends in the data, the evolving outlook and the balance of risks. My colleagues and I will need to come to our own judgment which may take more time.”
Since Williams spoke on Tuesday, the 2 yr yield has fallen by 15 bps. Rate hike odds have declined from 70% Monday to 24% today.
Auto sales in September totaled 15.98mm at a SAAR. That’s below the estimate of 16.3mm and compares with 16.39mm in September 2025 and vs 17.19mm in September 2019. We are thus 7 yrs past that 2019 figure and vehicle sales are still below with used car sales picking up the slack because of the affordability challenge of buying a new car.
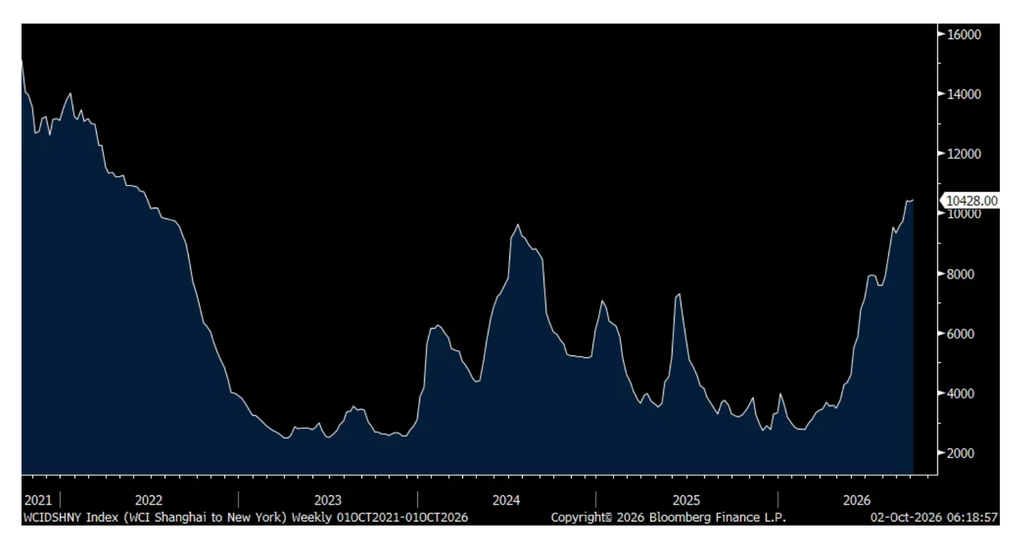
Out yesterday, container shipping prices were little changed from Shanghai to both NY and LA, though hovering around the highest since June 2022.
Shanghai to NY
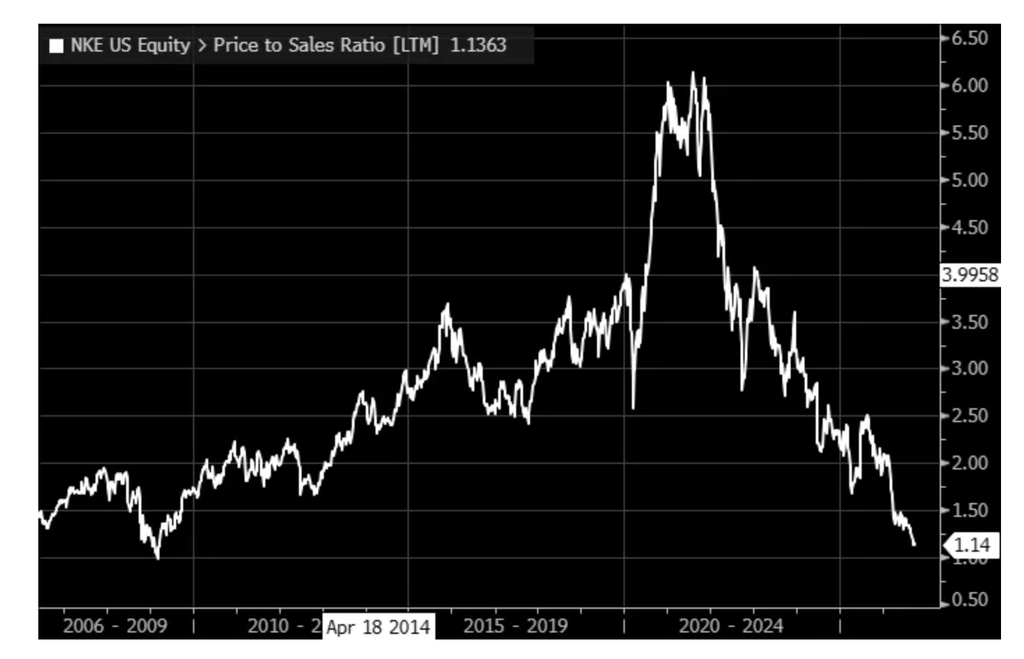
I believe in the swoosh and iconic brand that is Nike. I believe in Elliott Hill and the new CFO. I believe in the upcoming product lines, particularly the new Caitlin Clark sneaker and their ability to create excitement again with their SKUs. I believe in the shift away from mostly relying on DTC. I believe that they are still the dominant sneaker maker in the world with still a global market share of about 20%. I believe its Jordan brand and its China business can be stabilized. And while the price relative to earnings seems high, I believe it’s because they are dramatically under earning relative to the potential and the price to sales ratio is back to a level last seen in early 2009, at the absolute bottom of the US stock market back then at the depth of the GFC. I’ll take that nearly 5% dividend yield too.
Here were some things of note said by them last night:
“Overall, there’s a lack of energy in the lifestyle space right now, which is impacting traffic. Yes, the consumer is cautious, but as the leader in the industry, it’s on us to bring more creativity to sportswear. The headline decline only tells part of the story. Within sportswear, several major franchises are healthy and growing.”
“I believe strongly that we have strengthened the foundation of our business, and our direction is super clear that we’re building Nike the right way and we are building Nike for the long term. And I would characterize that our comeback is ongoing. At our size and scale, meaningful change takes time. Our turnaround is happening one sport, one sport community, one city, one country at a time, and we are reallocating resources against our biggest opportunities. So we are building for the long term.”
Price to Sales Ratio for Nike as of 10/1/26
McCormick, the spice, seasonings and condiment maker, is another battered and beaten stock we’ve recently bought and they said this of note after reporting earnings:
“Geopolitical volatility, elevated fuel costs, and persistent inflation continue to influence consumer confidence and spending. In the US, higher gas prices and the Cyclospora outbreak have added pressure and contributed to softer traffic across foodservice and grocery channels.”
“Consumers continue to look for practical ways to manage their budgets, including using what’s already in their pantry, repurposing leftovers, and seeking simple, affordable ways to add flavor at home. At the same time, flavor exploration, health and wellness, and affordable indulgence remain important priorities, supporting demand for flavorful, convenient meal solutions across retail and foodservice.”
Accenture had a big day yesterday with its stock rallying 16% after earnings. From them of note:
“Growth was broad based across markets, industries and both types of work, and we once again took significant market share.”
“Our focus on being relevant where our clients are spending helped us capture the strong level of bookings even though the overall demand environment, including discretionary spending, did not meaningfully change.”
Overseas of note, Tokyo inflation in September rose 3% y/o/y ex food and energy and that was well above the estimate of 2.5% and up from 2% in August. JGB yields are lower though, following the drop elsewhere but the pressure continues to grow on the BoJ to keep on hiking. The yen is higher.
Also of importance on the inflation front was the September Eurozone print and which was up 3.8% y/o/y, one tenth above the estimate and up from 3.2% in August. The core rate rose 2.5% as expected.
The ECB with a deposit rate of only 2.5% will be hiking again soon too.
