Boockvar on Earnings, Econ Data

The following is fro Peter Boockvar:
Just a few things of note
I’ll be out all morning so won’t be able to comment on the flood of data, though none is market moving.
At the end of the day, we know the entire AI infrastructure ecosystem is so dependent on Anthropic and OpenAI and at least we are a step closer to seeing and forecasting the financial state of them. In coming years though, it will not just be the US customers/subscribers they need to capture, it is competition for them around the world where open source/weight will be an intense challenger.
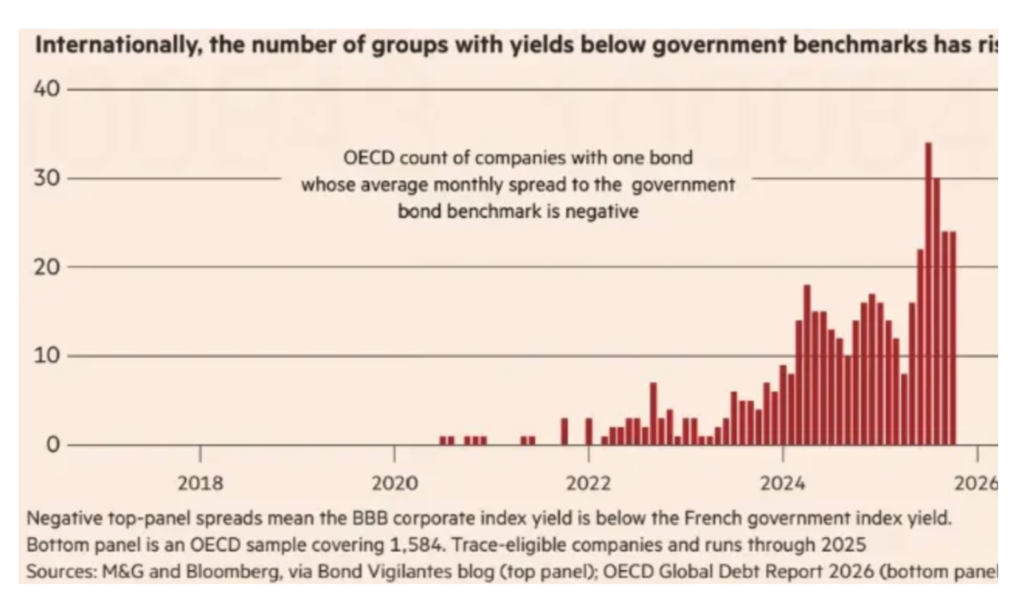
This was an interesting chart in yesterday’s FT which highlights the extent to which some companies have lower bond yields than the countries in which they are domiciled.
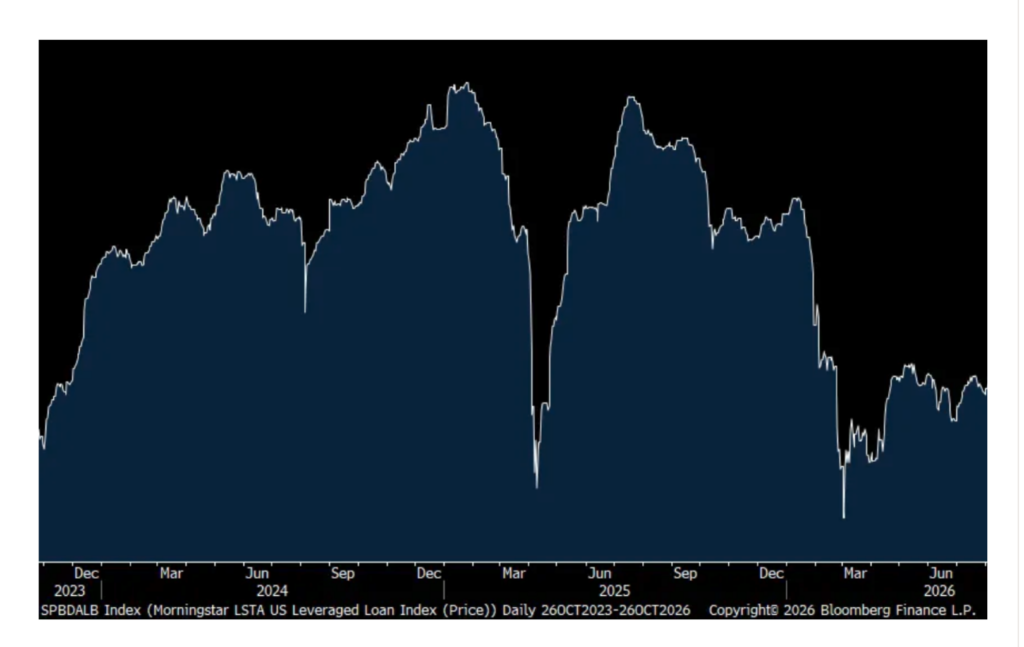
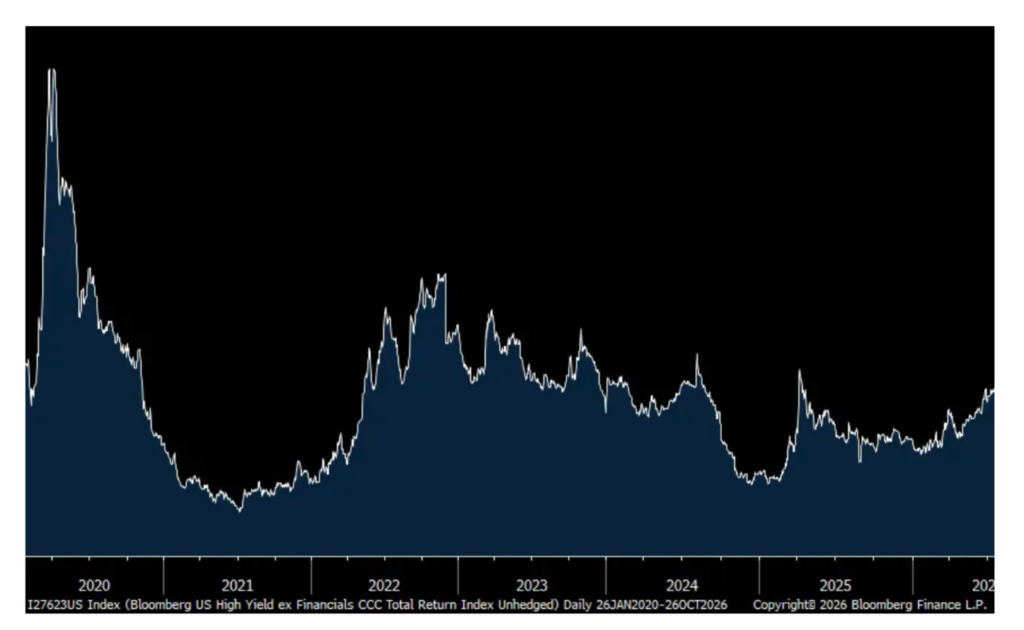
On the opposite end of the credit curve is of course the lower rated companies and capturing some of that is the LSTA leveraged loan index which closed yesterday at the lowest level since right after the Middle East conflict began at just $.9425 on the dollar. That’s below the ‘Liberation Day’ lows. The CCC credit spread is nearing 1300 bps at 1273 bps, the highest since the Covid shutdowns.
LSTA Leveraged Loan index
Bloomberg CCC Credit Spread index
What was interesting in the Verizon earnings call were the comments on the upcoming competition with SpaceX:
“Clearly, the tech and the wireless landscape is rapidly evolving, and we need to rapidly evolve along with that. I’m pushing hard on everyone so that we can shape the market and not react to it.”
“I also operate under the assumption that everything SpaceX says they will do, they will do, and that they will execute flawlessly…I think we should take it quite seriously. And from what we see and what we hear in the market because there are no secrets in the market, we know exactly what they’re going to do…It’s going to cost hundreds and hundreds of billions of dollars. I assume somewhere between $300 billion and $.5 trillion over the next, like, seven or eight years.”
From the Whirlpool earnings press release and trading down premarket:
“Excluding currency, net sales decreased 8.2% y/o/y driven by soft industry demand.”
“Announced price increase of 7% effective in Q4, supported by product innovation.”
From the Celestica press release, the original equipment manufacturer making many things going into the data centers and trading up premarket after good numbers:
“Celestica is well positioned to continue to support leading hyperscalers and frontier AI labs through the ongoing AI infrastructure supercycle. The demand environment continues to be very robust, supporting our 2027 revenue outlook, with customer demand forecasts meaningfully higher for 2028.”
In yesterday’s Dallas Fed’s manufacturing index for October which rose to 13.4 from 9.8 as the manufacturing recovery continues, here were some notable respondent comments:
Beverage and tobacco product manufacturing
· We continue to see pressure on profitability. We are profitable, but barely. The challenge is the increase in costs we are paying for our raw materials. The increase in diesel costs is the justification we are being told from our suppliers. Being able to give our employees year-end raises to keep up with inflation will be a further pressure on profitability.
Computer and electronic product manufacturing
· Higher interest rates affect our industry in a big way.
Fabricated metal product manufacturing
· Some product mix changes, but overall we’re forecasting a fairly positive picture over the next 6 months.
Food manufacturing
· Geopolitics, labor issues and recession/inflation worries.
Machinery manufacturing
· Business is strong, with many new existing projects ramping up, and we’re continually receiving new business opportunities.
· Activity is up and down; right now we are up.
· The data center bubble will burst soon, but a viable business model underlies it that will survive, just on a smaller scale. The creative destruction of the free-market system will prevail.
Nonmetallic mineral product manufacturing
· It’s difficult to find manual labor workers right now. We are hopeful the political climate will change in November and things overall will get better.
Printing and related support activities
· Data centers spending money on flimsy steel and HVAC systems does not make the economy robust. Rates should come down for those of us that have to support the system in the long term.
· We are getting to be really slow and low on work which concerns me greatly. Many of our competitors were slow this summer when we were busy with large projects we have done for many years in a row during the summer months. Now it’s our turn I guess to be slow.
Transportation equipment manufacturing
· Fuel pricing and the cost of domestic product increasing are dramatically tempering a recovery in the freight market.
· Outlook plans will depend on the midterm outcomes and the Fed’s interest rate action.
