Boockvar on Brazil, Fed, Gold and Earnings

The following is from Peter Boockvar:
Disappointing outcome/3 things to watch/Fed/Gold/Earnings/data
Very disappointing outcome with the Brazilian election and the shift away from its own socialistic experiment under Lula will not happen just yet. As we’re long a Brazilian stock ETF and some of its local currency bonds, it will not be a fun day with that.
With respect to the AI tech trade and the economic impact when sort of narrowing down the key aspects and questions to be watching/answering as we approach 2027, I put it into three buckets of focus:
1)Will the expected/hoped for amount of compute capacity get built and if not, what does that mean for the picks and shovels providers selling into the construction of the buildings and does it make those that do get built more valuable?
2)Both on the software/model side and with hardware, to what extent will the onslaught of Chinese competition erode the profits of its US competitors?
3)The history of technology typically leads to lower prices for hardware and services, and will the same eventually happen for GPU lease rates that financiers now want to turn into an asset class? Right now GPU lease rates have been rising but I question the sustainability of that over time.
Very much expected, but Meta is tapping the equity markets today for the first time since it priced its IPO in 2012. We know Google did the same earlier this year and highlights again the massive capital needs of this AI infrastructure build and the erosion of free cash flow needed to finance it.
With regards to the Fed meeting this week, I see no chance they will raise rates with the market pricing telling us the same. I do think though, the tremors in the AI trade over the past few weeks and the rising financing costs are now on the economic/market radar screen of Chair Warsh. To this, if the tremors turn more nasty in the coming few weeks/months, I don’t think they hike in December either but vice versa, if things calm, they likely will.
Gold has sold off hard the past two trading days but if there is one thing the price should like it is falling real interest rates and over the prior two trading days, the 5 yr real rate is down by 20 bps. I’m hoping gold holds this $4000 level again and the next thing I’m watching for is the soon to be released Q3 report from the World Gold Council to see the extent at which central banks are still buying.
I’m about to drown in earnings calls and here is what I got from the end of last week.
From Comfort Systems, a company being one of the data center picks and shovels because of its HVAC systems and whose stock fell 9% on Thursday and again on Friday because it’s an AI play and due to higher costs:
To a question of whether they are seeing any impact from data center moratoriums in some states in terms of changes to “project schedules” or “push-out in the pipeline in any of that states”, the CFO said “So, I would say and having talked to one of our biggest companies in the last day or two, the answer is generally no. I don’t know a project where one of these considerations has changed its trajectory. I think on a big, more macro level, I have a sense and I’ve talked with people who have given me this sense, this may push more of the work nationally into more sort of friendly jurisdictions.”
“So if you were a large hyperscaler and you were laying your bets on which states you wanted to do work in, where you place your bets, where you go do your work and make your commitments is going to be influenced by your perception of whether the Governor in that state wants people in that state to have jobs, right? I’m not saying it has no effect, but I don’t think at a micro level, we’ve seen any effect whatsoever.”
On costs, “material and equipment was about 2% higher than it had averaged in the first six months. The only other time we brought that up was during Covid because there was so much inflation in materials and equipment.”
From SLB, the oil service company we own stock in and that was up 7% Friday:
“It’s an exciting cycle for exploration. I think the combination of energy security as a heightened priority, as well as depleting reserves and the pressure of declining production are adding and fueling this investment in exploration.”
From American Express, down by 3.7% Friday but ended up closing flat on the week:
“Customer behavior looks very similar to what we’ve seen over the past year. Strong and consistent spend growth, especially in the T&E categories, balance growth in line with spend, high retention rates, and excellent credit performance.”
“Airline spending accelerated to 13%, while restaurants, our largest T&E category, saw spend growth of 9%. US consumer spending was up 9.4% this quarter, reflecting the continued strength in our premium customer base. While growth moderated slightly through Q2, it was in line with Q1, and continues to run above the levels we saw in 2024 and 2025.”
I’ll add, we know some of that T&E spend, particularly with airline, is partly price with airlines raising fares.
“Delinquency rate remained very low and stable…We feel very good about the quality of our credit performance and the stability we see in the portfolio.”
Rising marketing expenses was a focus of investors and the company explained the need for it. The CFO said “It’s been highly competitive. And our assumption is that it will remain highly competitive.”
From Tractor Supply, whose stock was flattish last week:
Comps grew just .4% but “We’re encouraged by the improving sales momentum and broader strength across our business.” They saw a .7% rise in average ticket but a .3% drop in transactions, though the latter was “cycling 2.7% growth last year, resulting in one of our strongest two year stacks of the past five years.” And “as we move into Q4, we expect continued momentum in sales trends, while recognizing that consumers remain cautious.”
More on their consumer, “Several broader trends continue to pressure the categories we serve. Elevated interest rates and reduced housing mobility are weighing on property improvements and larger projects. Pet ownership headwinds, particularly new pet acquisition, continue to affect demand in certain categories.”
“Across the farm economy, increases in commodity prices and operating costs are influencing purchasing decisions. Customers continue to spend, but remain cautious. In our most recent consumer work, more than 60% said they felt less comfortable making non-essential purchases than six months ago. Inflation, higher fuel costs, and broader uncertainty continued to weigh on household budgets and discretionary spending.”
Finally, “across our store base, rural locations returned to more positive comp growth and again outperformed the other population density groups.”
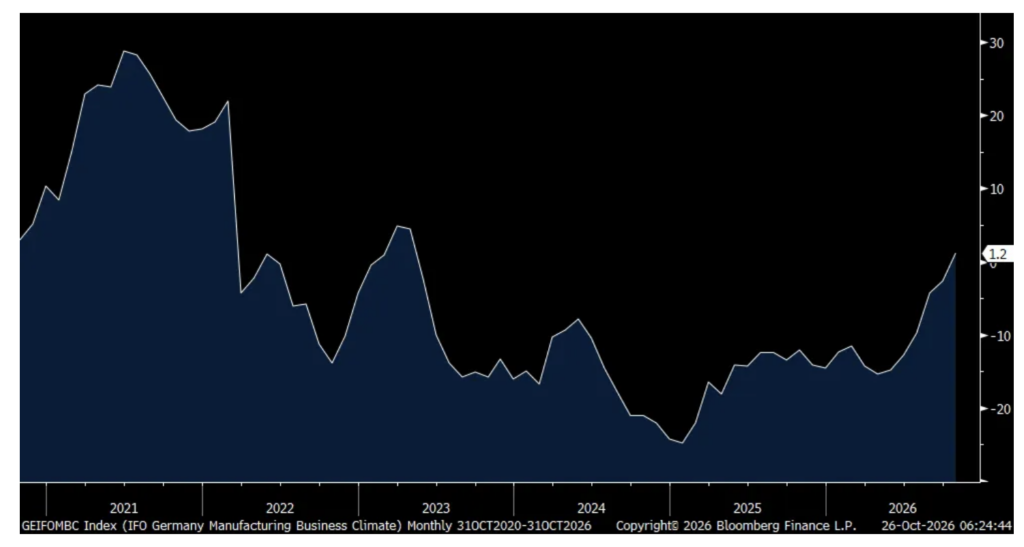
The one data point of note overseas was the October German IFO business confidence index which rose a touch to 90.2 from 89.9 but the components were mixed as all of the gain came from the Expectations line as the Current Assessment fell. The IFO said simply, “The economic recovery is continuing” and a key reason for this is the continued rebound in manufacturing with this component going positive for the first time since April 2023 “as incoming orders increased.” Services in contrast softened but “IT service providers performed particularly well.” Construction rose and trade was unchanged.
Bund yields are up slightly while the euro is flat and the DAX is up about .75%.
German IFO Manufacturing Component