Doug Kass is a world-renowned hedge fund manager with decades of experience and success navigating through some of the most turbulent periods in market history. He is known for his time-tested analytical skills and ability to look past the current noise and herd mentality.
On TheStreet Pro, Kass provides frequent market commentary and investing ideas for active investors throughout each trading day in Doug’s Daily Diary. He also serves as president of Seabreeze Partners Management Inc. Previously, he served as a senior manager at Omega Advisors, a $6 billion investment partnership. He co-authored a book with Ralph Nader and the Center for the Study of Responsive Law called “Citibank: The Ralph Nader Report” and can be found as a guest host on CNBC's "Squawk Box."
A Note from Doug: Current strategies and actionable trade ideas -- all on one dynamic platform built exclusively for active trades. From sudden sell-offs to sudden spikes, TheStreet Pro arms you with crucial analysis -- at a rapid fire, professional pace -- to help you make sound trading decisions -- every day, every hour, and every minute. Join me and my team of professional traders for unique perspectives and breakthrough investment opportunities.
With his last day today as a regular on CNBC, I have to express my huge admiration for this guy. Rick Santelli is a financial news legend that I will miss watching every day. He’s a man of passion who loves the markets and that will never change even though he won’t be reporting on it each day. I am so lucky to call him a good friend.
Oh, on to the jobs data.
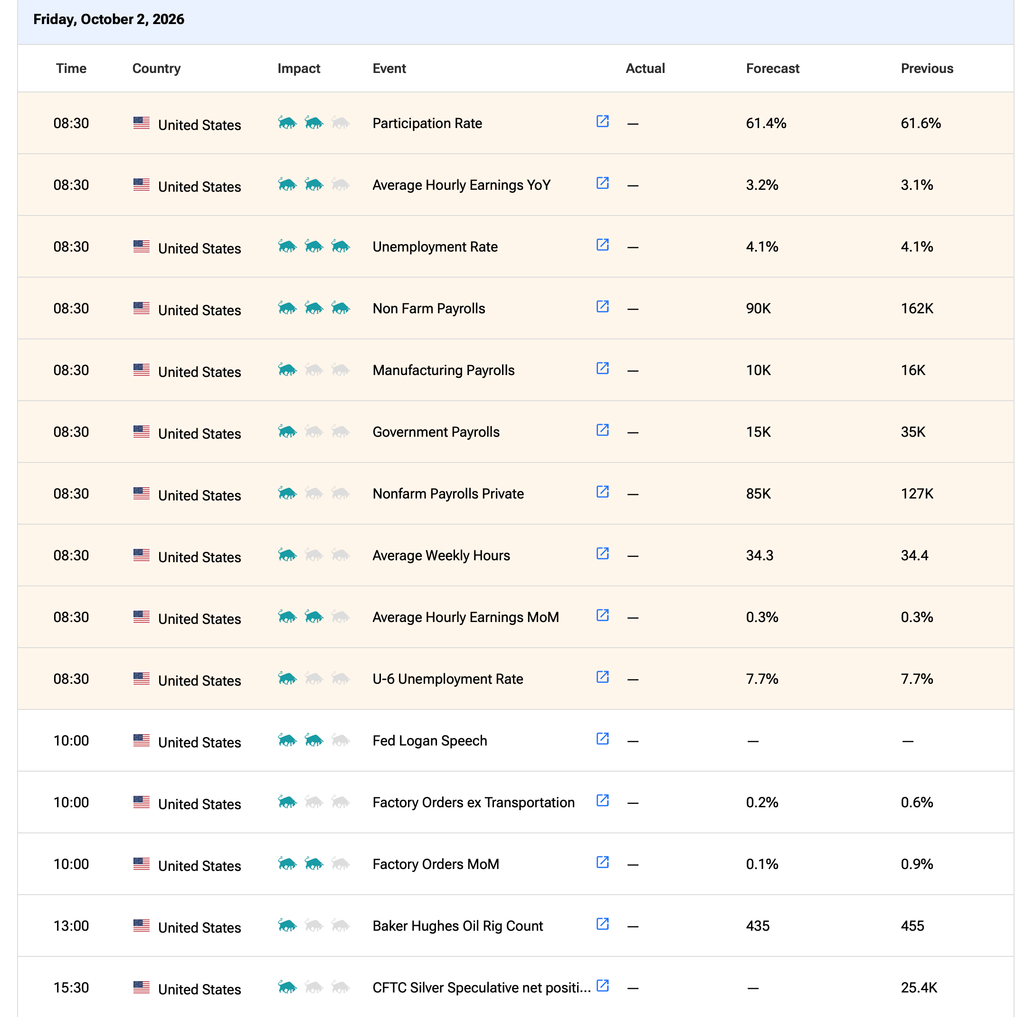
Payrolls were softer than expected, rising 29k in September and below the estimate of 90k. The prior two months were revised down by a total of 60k. Of this, private sector jobs grew by 46k vs 89k in the month before (down from the initial print of 127k) with a drop in government.
The household survey reflected strong job growth, though this is a very volatile monthly number, rising by 406k but because it didn’t keep up with the rise in the labor force of 485k, the unemployment rate ticked up to 4.2% from 4.1%.
Hours worked were unchanged at 34.4 while average hourly earnings disappointed with just a one tenth m/o/m gain and higher by 3% y/o/y. Combine the two and average weekly earnings were up 4.2%. The all in U6 rate though fell one tenth to 7.6%.
Seen in the rise in the labor force, the participation rate was up by 2 tenths to 61.8% and that matches the most since March. The key 25-54 yr old cohort saw an unchanged participation rate of 83.4%.
Of the 46k private sector net jobs created, it was led again by healthcare/social services which contributed 23k. Trade/transport/warehousing hired a net 24k followed by leisure/hospitality which added another 10k.
On the slip side, jobs were lost in information, financial services and business services.
Construction continued to be an area of job growth, with another 11k added. Manufacturing’s recovery, helped by making things going into data centers, along with inventory restocking, saw a 9k person hiring uplift.
Smoothing out the monthly volatility, the 3 month job gain average is 51k vs the 6 month average of 66k and the 12 month average of 41k. For perspective, in 2019 the monthly job gains were 165k.
Bottom line, the debate continues as to what the monthly job gains are needed in order to satisfy the increases in the labor force which we know have slowed. I’ve seen estimates everywhere from zero to north of 50k so the 3 month average is kind of in the range.
Treasury yields are seeing further relief, falling post softer than expected number. I’ll say again that we won’t get an October rate increase and not even worth guessing about December as it’s too far away.
No hike in October/I believe/Overseas inflation stats
With regards to the jobs data today, I’m most focused on the breadth of job gains. Will we see more hires outside of just construction, healthcare and leisure/hospitality?
I attribute the reversal higher yesterday in Treasuries/lower in yields to the German bund rally intraday where bunds became a safety trade as French and Italian bonds were selling off. That then shifted to US Treasuries. You’re seeing it again today, German bund yields lower by 8 bps after the 8 bps drop yesterday while French and Italian yields, while flat today, remain at their lows.
The Fed is not going to hike in rates in October and add Michelle Bowman and Vice Chair Jefferson to the list of Fed voting members, John Williams was the first, telling us so. Bowman late yesterday said “I don’t currently see an urgent need for further action, and I think we need to better understand the totality of the data, but remain attentive to the risks.”
This followed Philip Jefferson who said “As we look ahead, my view is that any future adjustments in policy should be determined by carefully examining trends in the data, the evolving outlook and the balance of risks. My colleagues and I will need to come to our own judgment which may take more time.”
Since Williams spoke on Tuesday, the 2 yr yield has fallen by 15 bps. Rate hike odds have declined from 70% Monday to 24% today.
Auto sales in September totaled 15.98mm at a SAAR. That’s below the estimate of 16.3mm and compares with 16.39mm in September 2025 and vs 17.19mm in September 2019. We are thus 7 yrs past that 2019 figure and vehicle sales are still below with used car sales picking up the slack because of the affordability challenge of buying a new car.
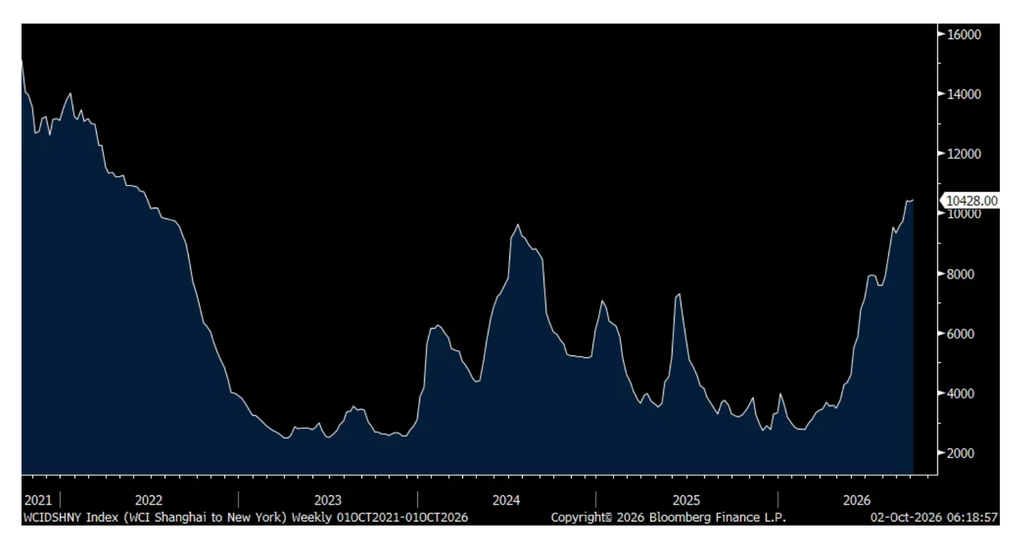
Out yesterday, container shipping prices were little changed from Shanghai to both NY and LA, though hovering around the highest since June 2022.
Shanghai to NY
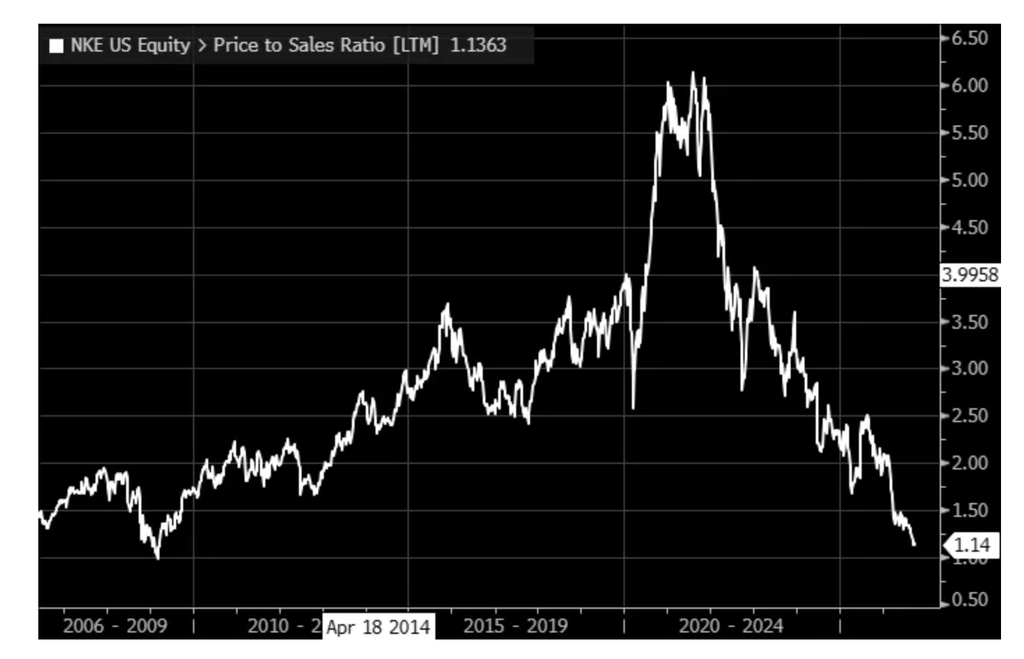
I believe in the swoosh and iconic brand that is Nike. I believe in Elliott Hill and the new CFO. I believe in the upcoming product lines, particularly the new Caitlin Clark sneaker and their ability to create excitement again with their SKUs. I believe in the shift away from mostly relying on DTC. I believe that they are still the dominant sneaker maker in the world with still a global market share of about 20%. I believe its Jordan brand and its China business can be stabilized. And while the price relative to earnings seems high, I believe it’s because they are dramatically under earning relative to the potential and the price to sales ratio is back to a level last seen in early 2009, at the absolute bottom of the US stock market back then at the depth of the GFC. I’ll take that nearly 5% dividend yield too.
Here were some things of note said by them last night:
“Overall, there’s a lack of energy in the lifestyle space right now, which is impacting traffic. Yes, the consumer is cautious, but as the leader in the industry, it’s on us to bring more creativity to sportswear. The headline decline only tells part of the story. Within sportswear, several major franchises are healthy and growing.”
“I believe strongly that we have strengthened the foundation of our business, and our direction is super clear that we’re building Nike the right way and we are building Nike for the long term. And I would characterize that our comeback is ongoing. At our size and scale, meaningful change takes time. Our turnaround is happening one sport, one sport community, one city, one country at a time, and we are reallocating resources against our biggest opportunities. So we are building for the long term.”
Price to Sales Ratio for Nike as of 10/1/26
McCormick, the spice, seasonings and condiment maker, is another battered and beaten stock we’ve recently bought and they said this of note after reporting earnings:
“Geopolitical volatility, elevated fuel costs, and persistent inflation continue to influence consumer confidence and spending. In the US, higher gas prices and the Cyclospora outbreak have added pressure and contributed to softer traffic across foodservice and grocery channels.”
“Consumers continue to look for practical ways to manage their budgets, including using what’s already in their pantry, repurposing leftovers, and seeking simple, affordable ways to add flavor at home. At the same time, flavor exploration, health and wellness, and affordable indulgence remain important priorities, supporting demand for flavorful, convenient meal solutions across retail and foodservice.”
Accenture had a big day yesterday with its stock rallying 16% after earnings. From them of note:
“Growth was broad based across markets, industries and both types of work, and we once again took significant market share.”
“Our focus on being relevant where our clients are spending helped us capture the strong level of bookings even though the overall demand environment, including discretionary spending, did not meaningfully change.”
Overseas of note, Tokyo inflation in September rose 3% y/o/y ex food and energy and that was well above the estimate of 2.5% and up from 2% in August. JGB yields are lower though, following the drop elsewhere but the pressure continues to grow on the BoJ to keep on hiking. The yen is higher.
Also of importance on the inflation front was the September Eurozone print and which was up 3.8% y/o/y, one tenth above the estimate and up from 3.2% in August. The core rate rose 2.5% as expected.
The ECB with a deposit rate of only 2.5% will be hiking again soon too.
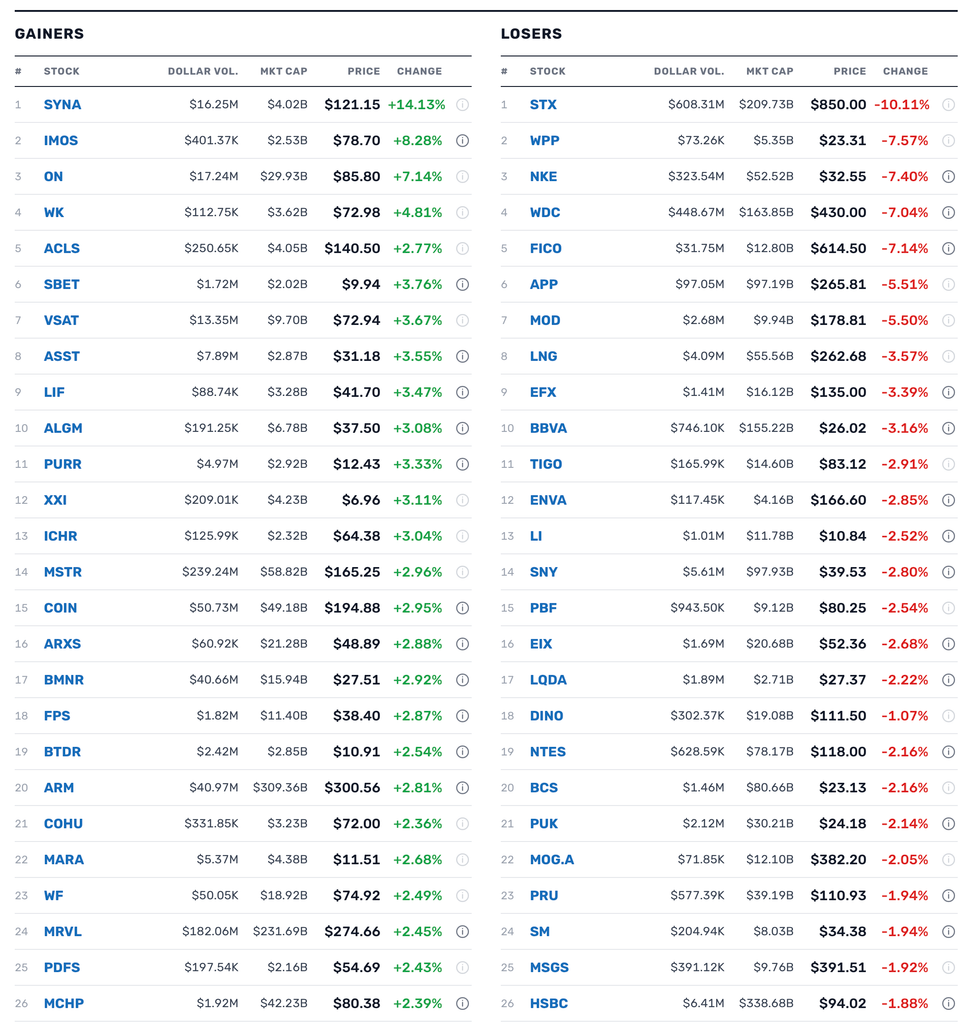
– $NXL -20.0% (gives back part of Thursday’s 76% spike following a 10-year Latin American distribution agreement)
– $STX -11.5%, WDC -7.0% (HDD makers fall after Toshiba outlined plans to double capacity and target sharply higher market share)
– $NKE -9.0% (mixed FQ1 as revenue missed and the FY sales outlook implied a surprise steep decline, alongside job cuts and a business reorganization)
– $FICO -8.5%, $EFX -3.5%, $TRU -2.5% (mortgage-credit names fall on a reported FHFA plan requiring lenders to pull data from two credit bureaus instead of three for GSE loans)
– $ASTS -3.5% (B. Riley downgrades to Neutral from Buy)
With S&P futures +66 handles and Nasdaq futures +335 handles I am starting a short scale on the Indexes:
* $SPY $770.73 * $QQQ $750.60
Look at the weak average hourly wage data – I am ever more convinced that with real wages dropping since April 2026 and the large drawdown in the savings rate, the consumer is weakening more than consensus realizes.
10:00 a.m.: Fed Bank of Dallas President Logan (Voter) gives welcome remarks before the Fifth Annual Workshop on the Macroeco-
nomic Implications of Migration co-sponsored by the Federal Reserve banks of Dallas, Atlanta and San Francisco; Banco de México; Bank of Canada; Instituto Tecnológico Autónomo de México’s economics department; and the Global Migration Center at the University of California, Davis, Dallas, TX (Text available. No livestream. No audience Q&A);
12:00 p.m.: Fed Bank of Chicago President Goolsbee (Non-Voter) Television Appearance — FOX Business.
During Q3 2026 four equities (stimulated by perceived AI growth opportunities) — $MSFT, $NVDA, $AAPL and $META — added about 300 points to the gain in the S&P index, representing more than 200% of the index’s total gain. The other 496 stocks subtracted approximately 150 points:
MSFT, NVDA, AAPL and META alone added about 300 points to the S&P in Q3, more than 200% of the index's total gain. The other 499-ish stocks together subtracted about 150 points: Citadel
Back to AI “concentration” credit risks — specifically that private equity (we remain short $BX, $APO, $OWL and $KKR) is piling into the same AI data center bet:
Before sub-prime was a crisis, investors betting against the bubble drove around to see the residential properties backing MBS. It was a lot of legwork.
Now with satellite imagery and this convenient list of assets about to enter bankruptcy protection, betting against the AI… https://t.co/ai68N6LJ4N
More on depreciation schedules and creative accounting:
Lenders say $NVDA isn’t being truthful about its chips being an appreciable asset are no longer willing to offer ABS for them to “Neoclouds” and smaller Hyperscalers like $ORCL without $NVDA putting up collateral as much as much as 25% to back the loans. Nvidia has been hoping to… https://t.co/zWKQUIseZT
Finally, continued AI skepticism from “Moon Alice” — Roger McNamee:
The thing with @moonalice.com is that 1) he's not selling anything, 2) he has more legacy/history here than most, 3) all of which means he can speak his mind w/o fear of recourse. "Markets have manias; this is a mania." And so much more… https://t.co/YnKbc5hs6A