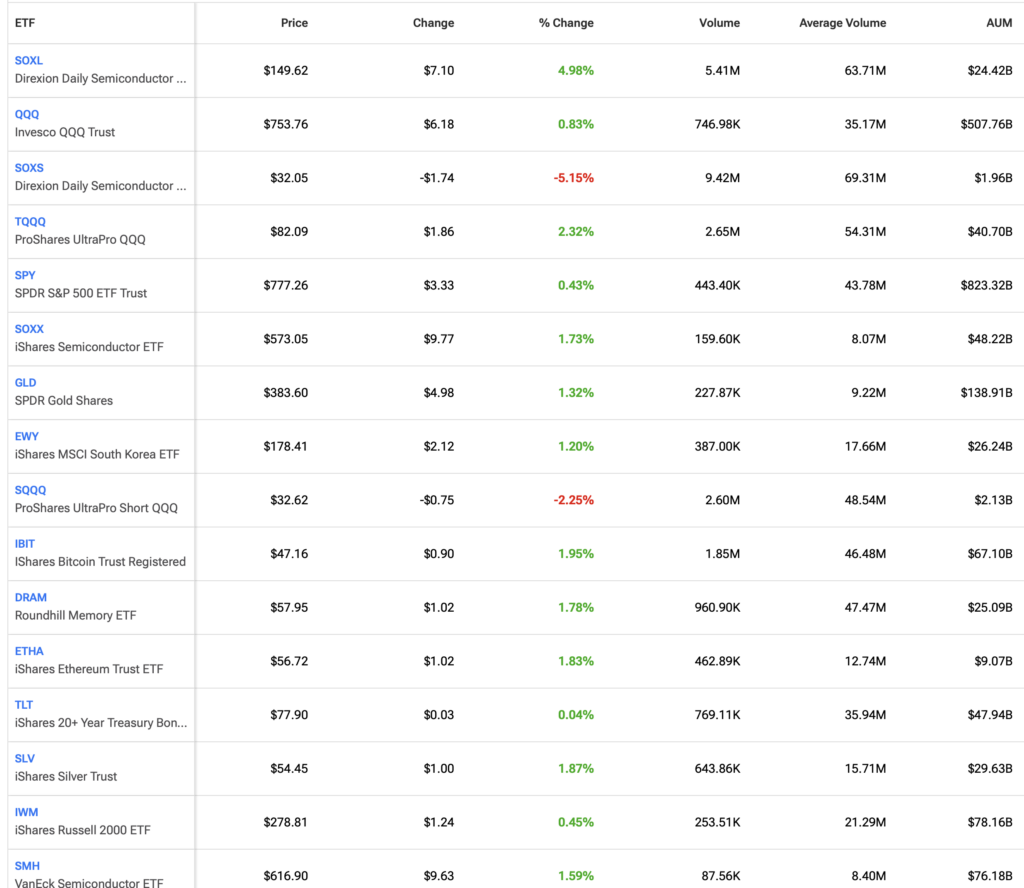
Late Morning Market Charts

Breadth
SOURCE: Interactive Brokers
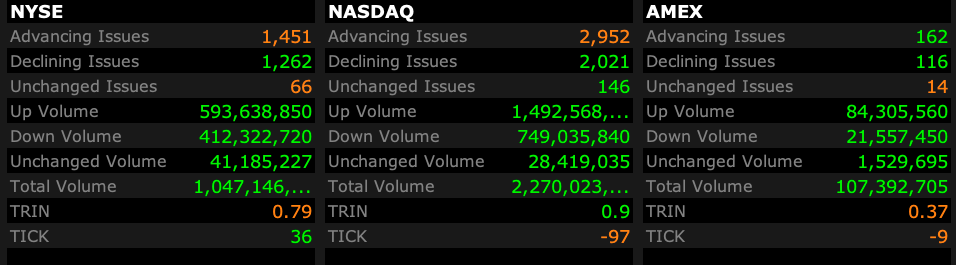
S&P500 Indexes
SOURCE: Barchart
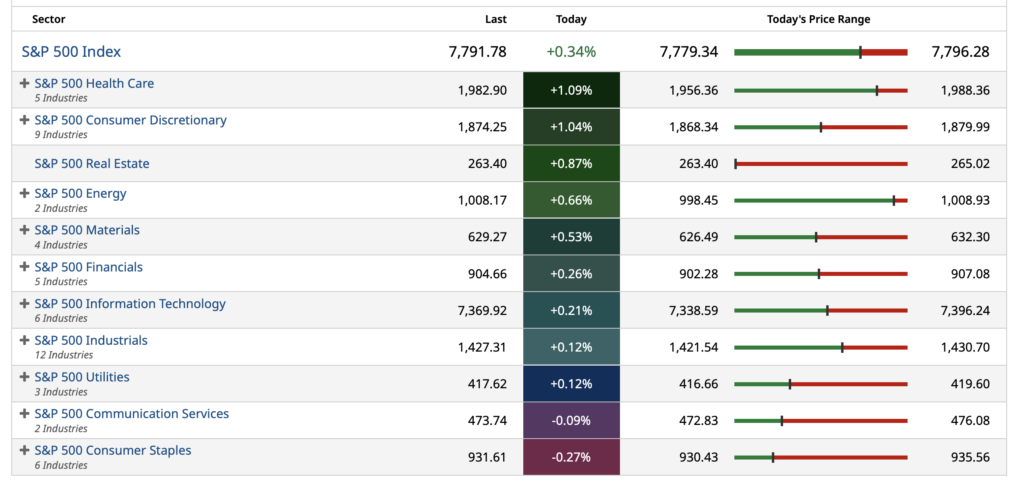
% GAINERS, DECLINERS
SOURCE: TheStreet Pro
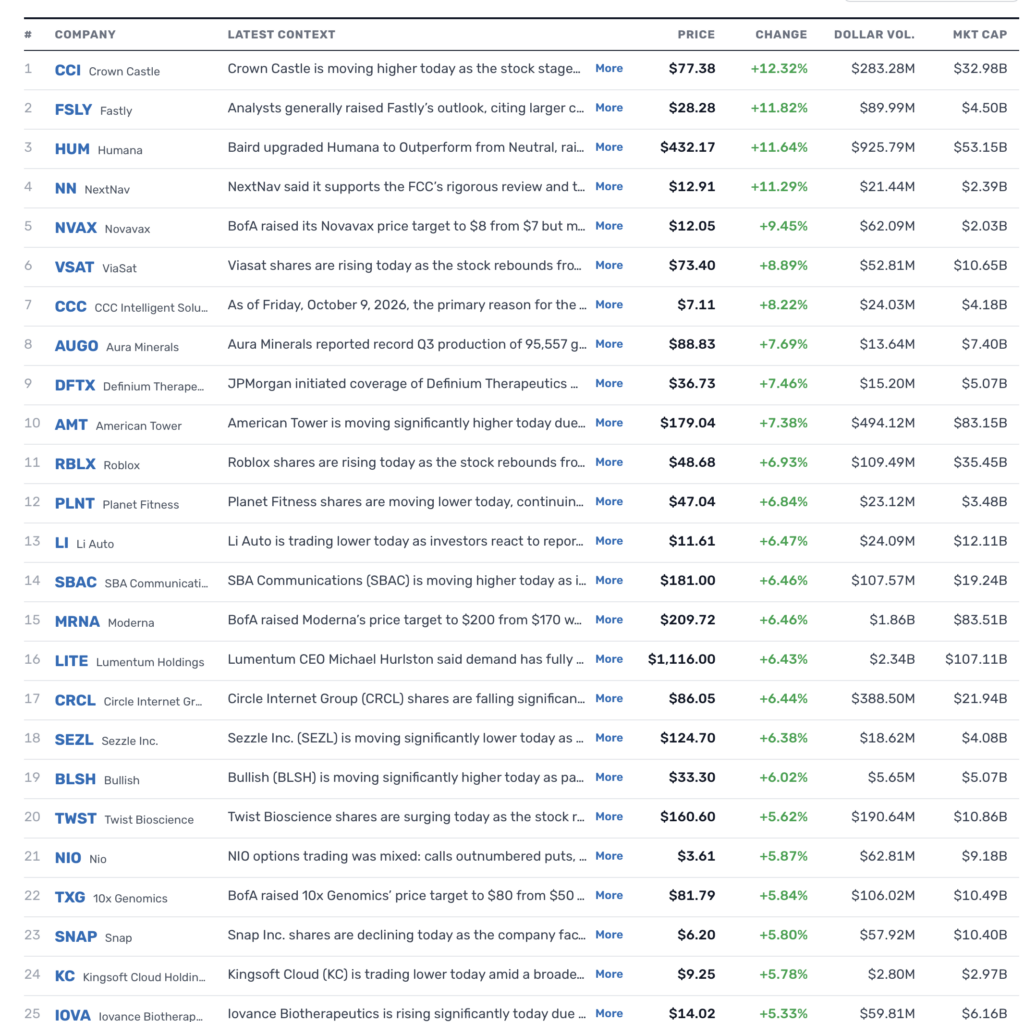
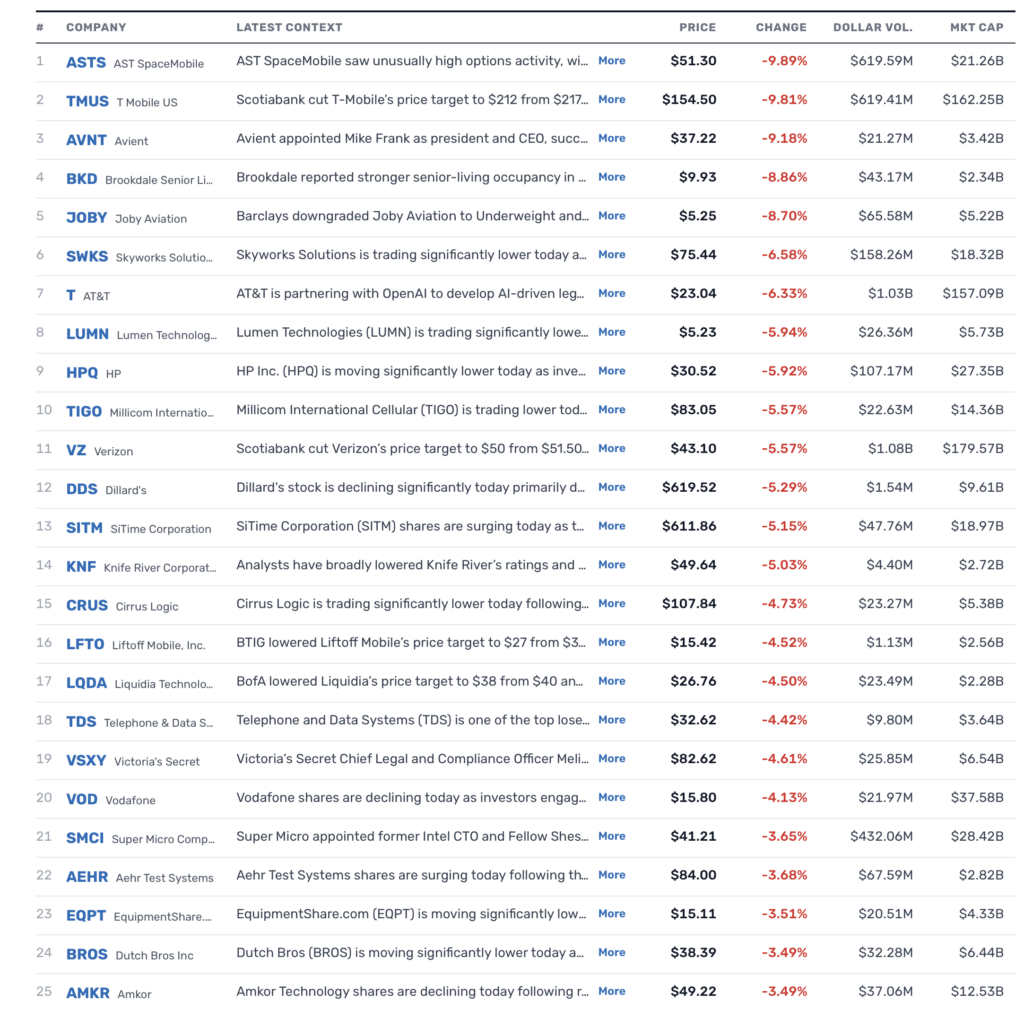
Nasdaq 100 and S&P500 Heat Maps
SOURCE TheFly
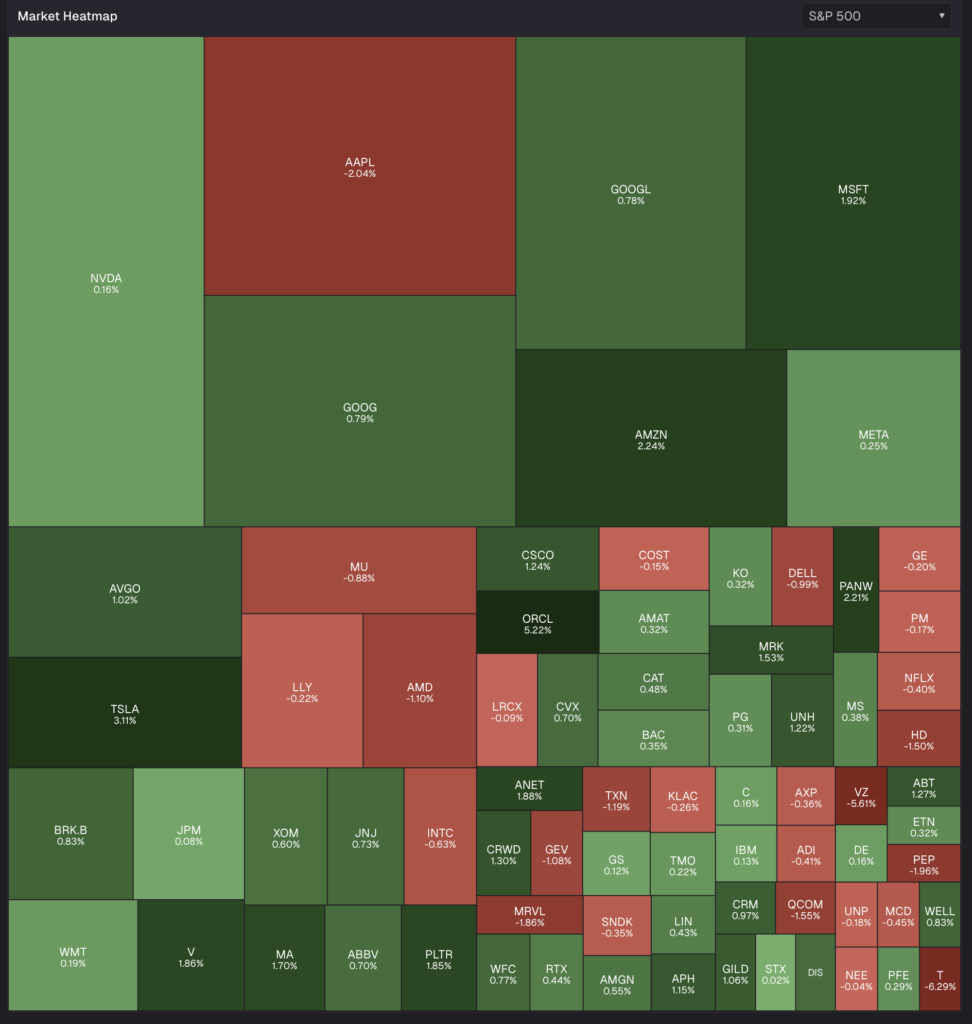
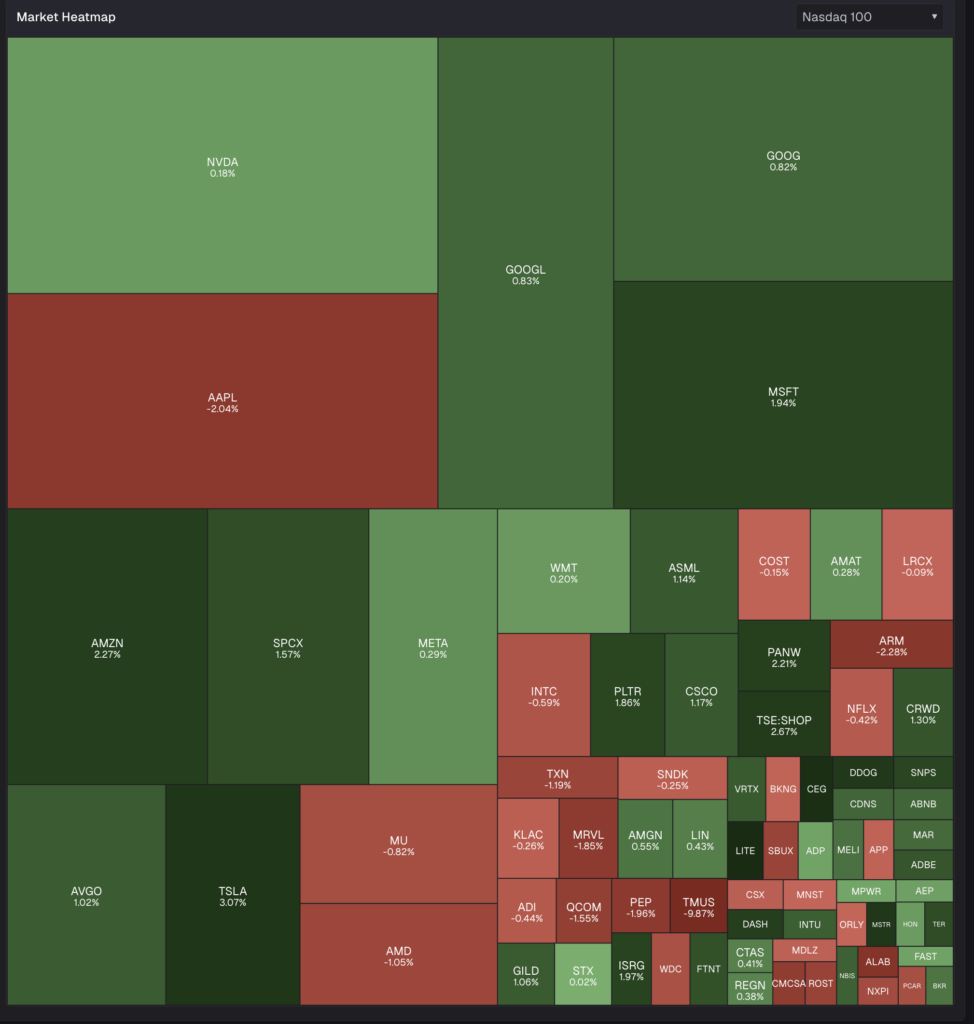
SOURCE: Interactive Brokers
SOURCE: Barchart
SOURCE: TheStreet Pro
SOURCE TheFly
For the second day in a row a reversal from much higher to flat on the day – $NVDA.
We added, as I suggested, on the +$3.50 rally earlier.
Positions: Short NVDS S
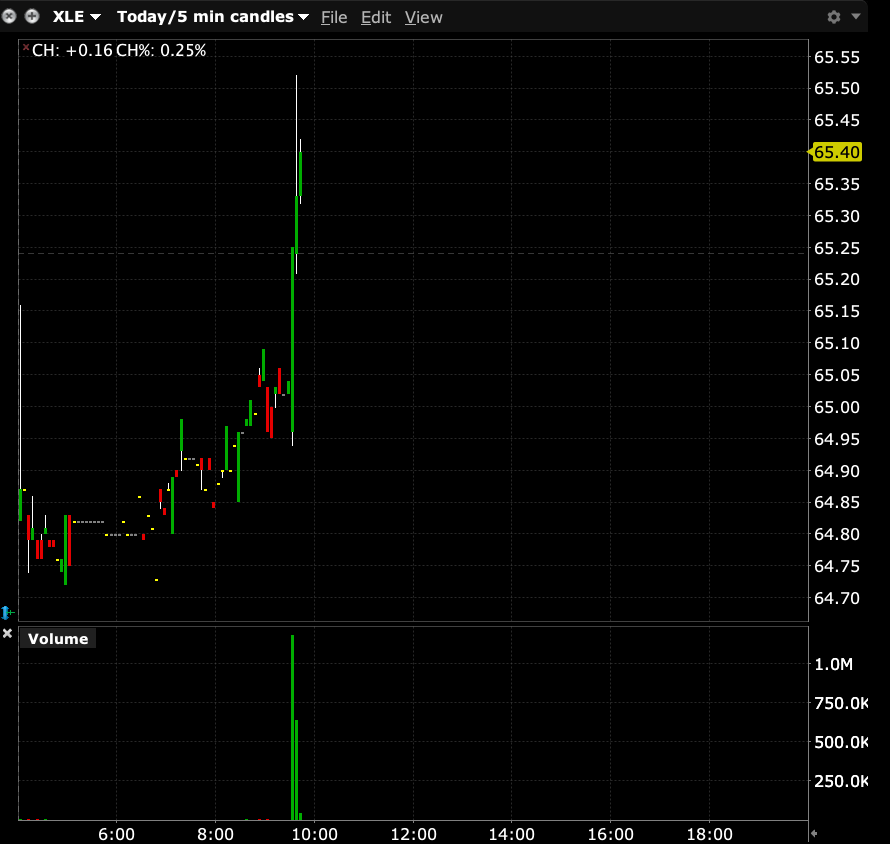
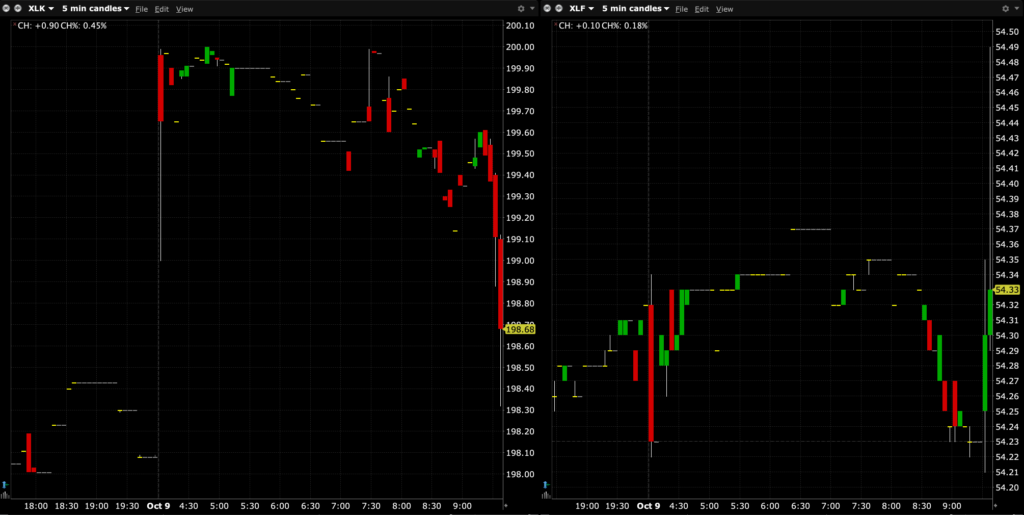
Charts from 9:40 a.m. ET
The following is from Peter Boockvar:
Whatever the methodology and/or nuance of how OpenAI calculates its revenue figure and whether it matched up with investor estimates or not, I think the most relevant big picture point is that a massive chunk of the GenAI data center buildout is literally reliant on two companies and whether all the CapEx will be money well spent will be hugely dependent on the ultimate profitability, or not, of OpenAI and Anthropic. And to add, a large piece of the future cloud backlog of Microsoft, Oracle, Amazon and Google are these two AI model makers. For the sake of the economy and the stock market, fingers crossed.
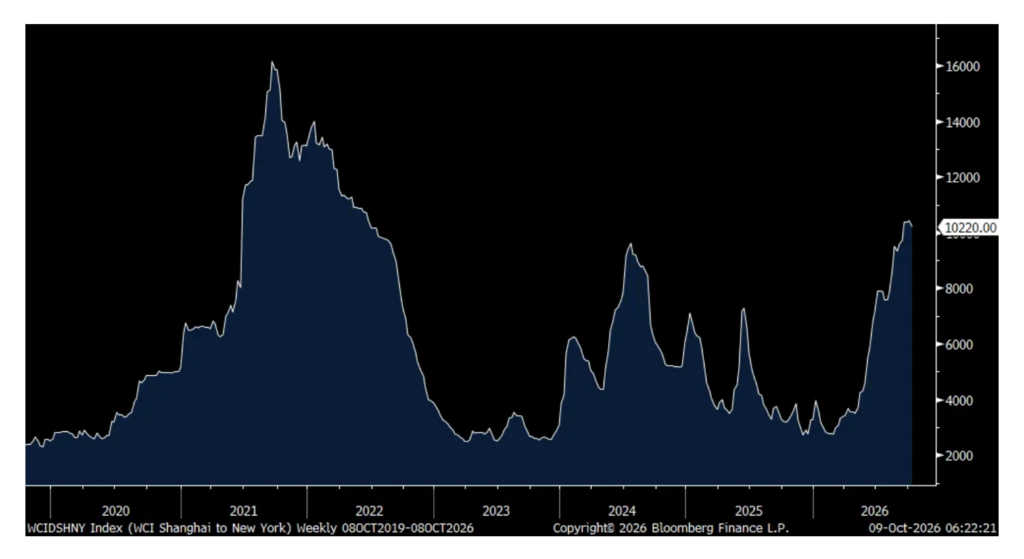
The container shipping lanes got some relief this past week with a drop in prices. The Shanghai to NY trip was lower by 2% w/o/w, though still holding above $10,000. The trip to LA was lower by 2.7% w/o/w.
WCI Shanghai to NY
The Investors Intelligence Bull/Bear spread remained above the extreme read of 40 but a bit less so. Bulls fell a touch to 56.9 from 57.7 while Bears were up a bit to 15.7 from 15.4. In the volatile and less reliable AAII survey, Bulls were up by 5.7 pts to 40.3 and that now exceeds Bears for the first time in a month and which fell by 7.5 pts to 39.
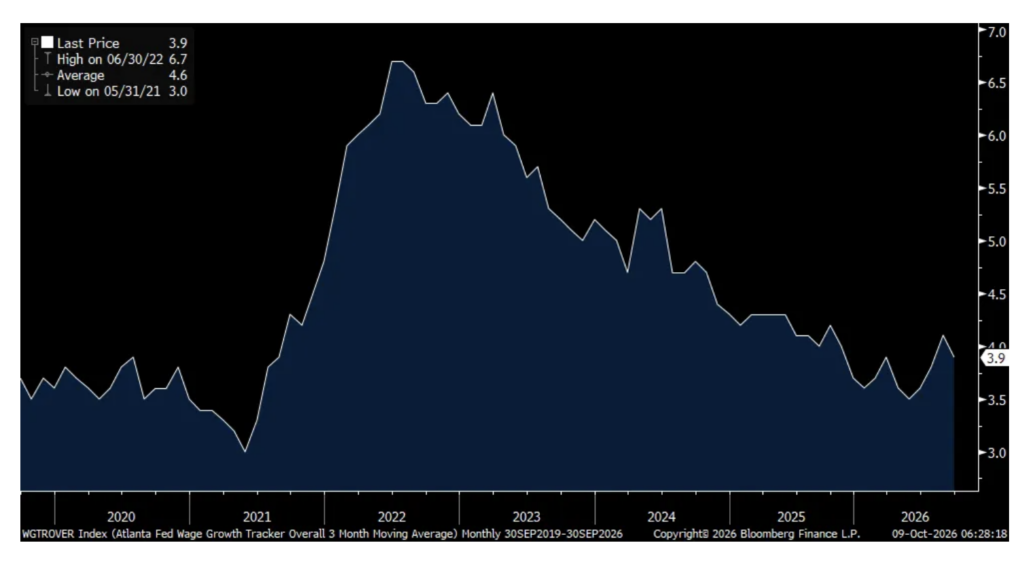
With inflation still running around 3.5%, depending on which metric you use, REAL wages are no longer growing much and that was seen with the Atlanta Wage Growth Tracker which came out yesterday for September. It was up 3.9% y/o/y and pretty much back to its pre Covid trend.
For those changing jobs, pay was up 4.7% y/o/y vs 5% in August. For those staying, it slipped to 3.4% from 3.6%.
Bottom line, part of the reason why the savings rate is at an 18 year low, not including the post Covid data noise, is due to the real wage squeeze. Along with the tremendous wealth gains for those that own assets and feel less need to save via their income relative to spending.
Atlanta Fed’s Wage Growth Tracker
Maybe price vs wage growth now matters for Apple phones. Nikkei Asia is reporting today that “Apple has told some of its suppliers to cut production of components for its newly launched iPhone 18 Pro and iPhone 18 Pro Max, after soaring memory chip costs forced price increases that have dampened consumer demand. Multiple people familiar with the matter told Nikkei Asia that the Silicon Valley-based tech giant has turned more conservative on shipments since early September, with two of them saying that component orders for this month have been slashed by at least 15% compared to what was originally requested, due to weaker-than-expected market demand.”
Apple is down pre-market in response.
This was said by Pepsi of note yesterday, a stock we own and up 3.7% yesterday after recent weakness:
“Our business in North America performed below our expectations and represents a meaningful opportunity for improvement. U.S. convenient foods organic revenue trends improved sequentially, reflecting volume share gains and U.S. salty and savory snacks volume growth. In addition, year-to-date household penetration, purchase frequency and velocity trends have improved as the innovation and affordability initiatives have resonated well with consumers.”
“In North America beverages, organic volume trends improved sequentially, with functional hydration and zero sugar offerings continuing to perform well while our performance in carbonated soft drinks trailed category performance.”
International outperformed.
With regards to how they plan from here on pricing their products, “we’re going to see a mix of net revenue management tactics that will impact some pricing, but also mix and all the decisions that we can make around that…making sure that next year’s pricing is going to be below ‘25, so we continue to be very affordable.”
Value and affordability remain key “with a consumer that is clearly challenged, and we don’t expect the consumer to suddenly become in a much better place in the next 12 months, 18 months.”
The beaten and battered consumer staples stocks remain one of my favorite sectors and we own a bunch of stocks in the space.
From Delta’s earnings release and whose stock is lower pre-market because they missed both top and bottom line estimates:
They are still optimistic, “Demand remains strong, supported by consumers’ growing preference for experiences and travel, with air travel continuing to be one of the best values in the consumer economy.”
“For the full year, we expect to generate a pre-tax profit of roughly $4.5 billion, absorbing a $6 billion increase in fuel costs.”
“Main cabin unit revenue grew 17% over prior year on seats down low single digits, marking another quarter of sequential progress…Premium revenue grew 18% y/o/y with double digit unit revenue growth driven by yield and load factor on a 6% increase in seats.”
Positions: None.
Dougie Kass
10m ago
For now I have stopped tweeting critical stuff on Fin TV.
I dont have the time and have concluded there will be no change in personnel or programming.
But the news at $DAL $APPL and other stocks this morning – support my view that few of the panelists have any investment process or rigor.
The believe “price is truth” and everything (from Best Stocks segment to individual panerist picks) are based on price and momentum and moving monkeys.
The know everything about price and nothing about value.
They are mostly asset gatherers (or selling another service).
Stated simply, I don’t play that game.
Positions: None
I added back to my $GRNY short at $28.43.
Selling on a scale higher.
I added to my $PEP long at $125.58.
Positions: Long PEP M, Short GRNY VS
We aggressively purchased $PEP in the premarket on Thursday and in early trading in the regular session.
Pepsico’s shares rose by over +$4 yesterday follwing the EPS and Sales guidedown.
Here is a summary of Goldman Sachs’ view of the company:
While investors debate whether PEP can grow earnings next year, we take a more optimistic view and expect faster topline growth on both the top and bottom lines albeit likely below the company’s l.t. growth algo. As such, we continue to see a positive risk-reward profile on the stock, especially as we think positioning and sentiment skews overly negative. Further, we think PEP’s valuation is attractive – with the stock trading at a very sharp discount (~10x) on a forward P/E basis relative to KO on a forward P/E basis – well below it’s l.t. historical average discount of ~1x – while also trading at a ~5x discount to PG (i.e., a Staples peer) despite a similar topline growth profile (to PG).
Bottom Line – We maintain our Buy rating on PEP, as we believe it remains well positioned given its strong brand portfolio and long-term growth opportunities in both
Food & Beverages, particularly given a robust innovation pipeline, its impressive revenue growth management capabilities, its owned distribution network and superior supply chain, which ensures the right (& affordable) products are available when & where needed. Overall, we believe PEP should be able to deliver sustainable average annual +MSD organic sales growth in the next decade – despite some near-term headwinds.
Piper Sandler lowered the firm’s price target on PepsiCo to $140 from $176 and keeps an Overweight rating on the shares. Despite a Q3 EPS beat, driven by strong International momentum, PEP faces growing input cost pressure and weak U.S. trends. Further brand spend increases are coming, also weighing on margins. It has a decent innovation pipeline for 2027, focused on functional benefits, like protein and hydration, but sustainable better growth is still unproven, argues Piper.
BofA analyst Peter Galbo lowered the firm’s price target on PepsiCo to $145 from $152 and keeps a Neutral rating on the shares. The company’s Q3 beat came with better than feared Pepsi Foods NA organic sales and commentary on sequential organic revenue acceleration into Q4, but a lowered fiscal year earnings outlook signals ongoing cost challenges and raises questions around the ability to grow EPS in FY27, the analyst tells investors.
Positions: Long PEP M
Positions: None.
We remain short of Nvidia ($NVDA) (with a $237.15 cost basis). The shares were $6 lower and indicated higher this morning; I plan to add to my trading short rental in NVDA.
Fred Hickey is brilliant and an old acquaintance:
Positions: Short NVDA VS
Source: TipRanks