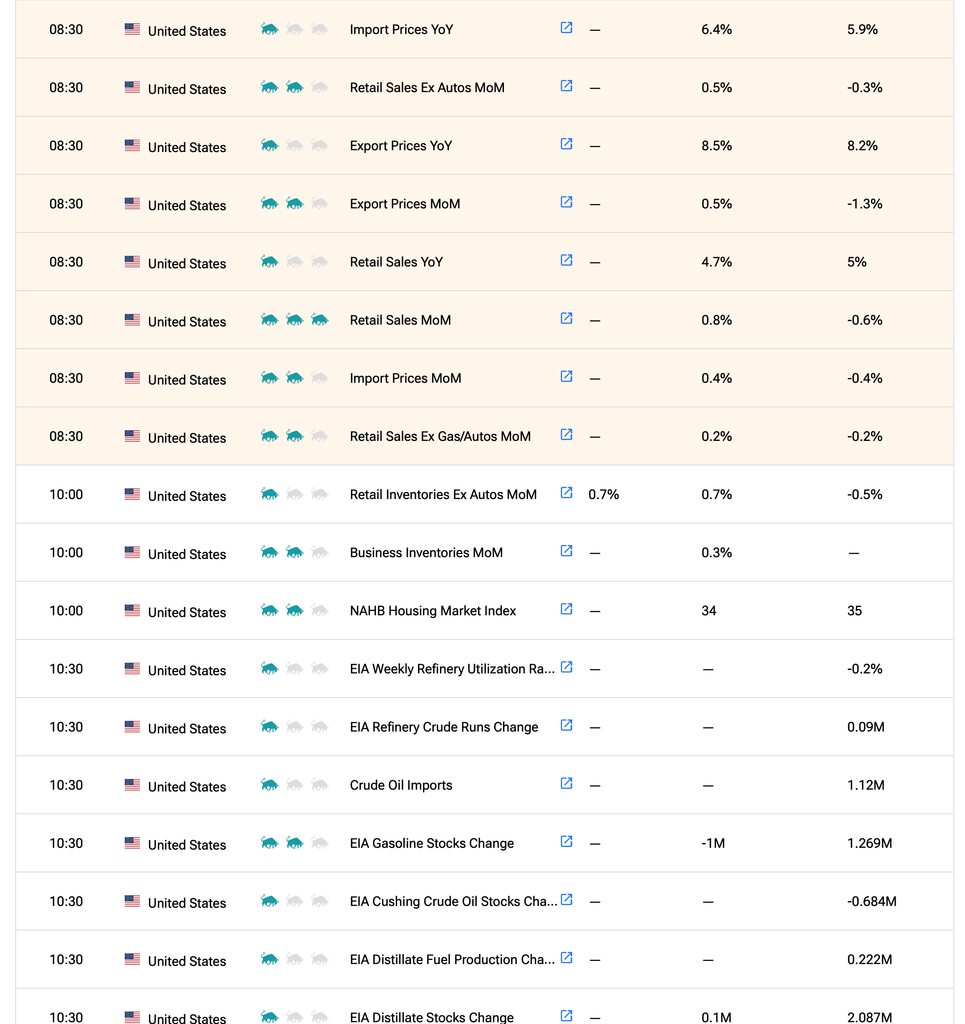
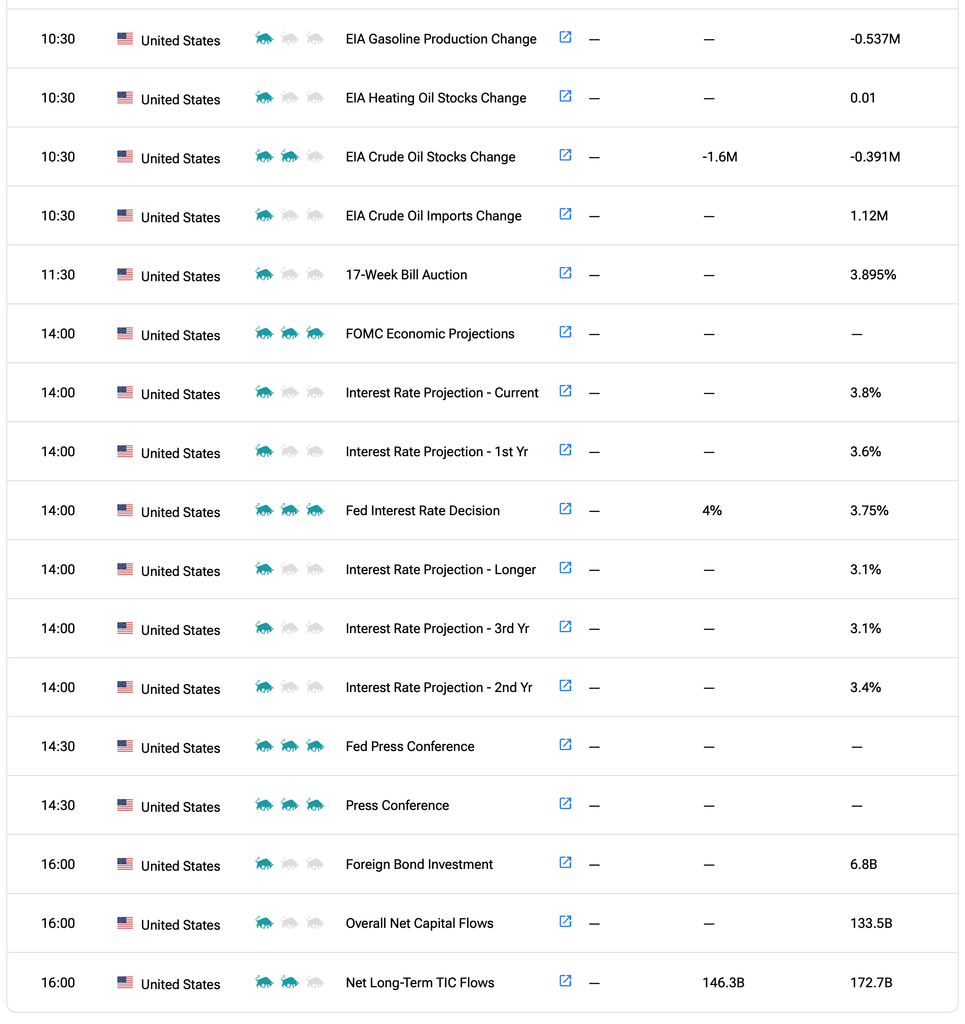
Economic Calendar

Source: Tip Ranks
Source: Tip Ranks
When are you gonna come down?
When are you going to land?
I should have stayed on the farm
I should have listened to my old man
You know you can’t hold me forever
I didn’t sign up with you
I’m not a present for your friends to open
This boy’s too young to be singing
The blues, ah, ah
So goodbye yellow brick road
Where the dogs of society howl
You can’t plant me in your penthouse
I’m going back to my plough
Back to the howling old owl in the woods
Hunting the horny back toad
Oh, I’ve finally decided my future lies
Beyond the yellow brick road
Ah, ah
– Elton John, “Goodbye Yellow Brick Road”
My baseline expectation is that the Federal Reserve will increase rates by a quarter basis point this afternoon.
I expect relatively hawkish comments from Chairman Kevin Warsh – as he reiterates his job of getting inflation down:
* Equities could initially respond positively to what is perceived to be responsible monetary policy in the face of sticky inflation. I don’t expect the rally to be sustained and I plan to short Indices on a ramp higher.
* Bonds might also respond well… with yields could decline by 5-10 basis points.
There are multiple reasons why I expect an equity rally to be short lived – which I have covered fully recently in my most recent “Market Outlook” column.
But market participants could soon realize that even a multiple rate rise will not dampen inflation (and that there are likely adverse consequences, especially as seen in the housing market). Rather, the problems of inflation are supply chain, fiscal policy and geopolitical based — not interest rate based.
And the anticipated tightening policy (of perhaps two more hikes by January, 2027) will cause more damage than good.
As noted on Tuesday, I believe we have already seen a top in the S&P and Nasdaq Indices for the year.
Goodbye Yellow Brick Road and say Goodbye to Rosy Scenario. Kass: Welcome to the ‘Rosy Scenario.’ What Could Possibly Go Wrong?
Positions: None.
Knowledge@Wharton:
Is Overreliance on AI Causing Agency Decay? – Knowledge at Wharton
Position: None
While the bullish cabal see the foundation of the next bull leg to be EPS, we are at odds with that notion…
Position: None
I am often wrong and always in doubt.
Unlike so many “tallking heads” on CNBC and so many anonymous Tweeps we get it wrong a lot. (And unlike most of them, who spend most of their time polishing their images, I take ownership of my investment boners.)
But, as noted in Where are My Index Shorts? column we have been on the “not broadening” theme since July — while the consensus was still buying $IWM and $RSP and pushing the broadening theme (without facts):
Position: None
Position: None
* Slowing economic growth and persistently high inflation = slugflation!
Position: None
* First time, long term
Gold has had quite the fall from earlier year highs.
We have been accumulating $GLD over the last few days and, as posted, we purchased a slug at $391 yesterday morning.
At 6:15 AM gold is trading +$4.20 to over $398.
I am inclined to view this position as a core holding (and not a trade) reflecting continued currency depreciation, inflation higher for longer, Washington DC’s fiscal imprudence and expanding geopolitical uncertainties
Position: Long GLD (M)
The S&P Short Range Oscillator remains in oversold territory at -4.72% vs. -4.56%.
This sentiment gauge coupled with the recent price weakness have partially been responsible for having me tactically cover my index shorts (for a profit) and resulted (in the past week or so) of selling rips and covering dips.
The deterioration in market breadth (“not broadening”) that we have been highlighting since July (in the Russell, Equal Weighted S&P and McLellan indicator) presaged the recent broader market weakness.
As noted in my recent Market Outlook column I remain bearish and intend to reestablish my index shorts subject to price and the fundamental backdrop — probably sooner than later.
Ergo, the absence of index shorts in Seabreeze’s portfolio is likely a very temporary condition!
Position: None
Closing Volume
– NYSE volume 4% above its one-month average
– NASDAQ volume 7% above its one-month average
– VIX index: up 1.05% to 17.28
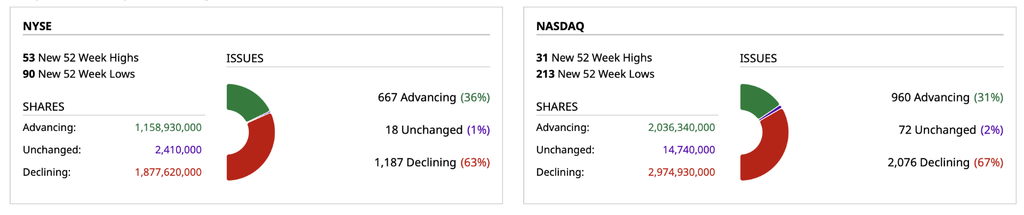
Breadth
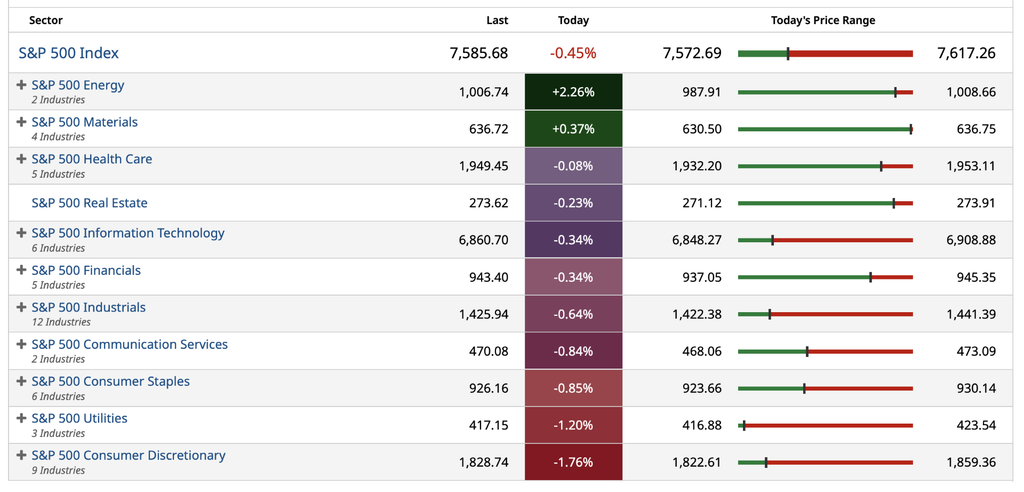
S&P 500 Sectors
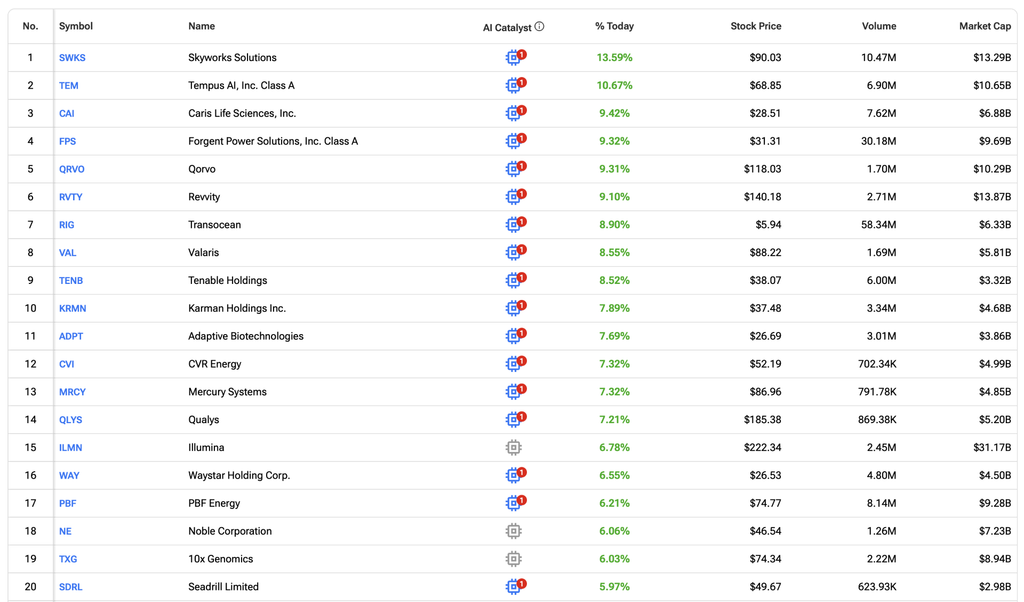
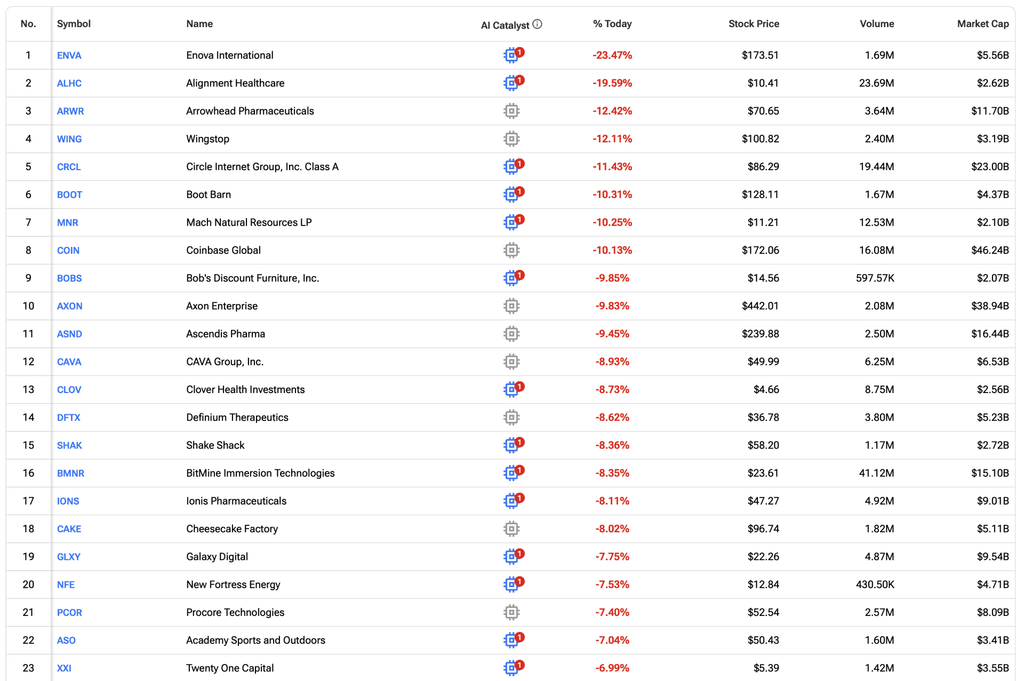
% Movers
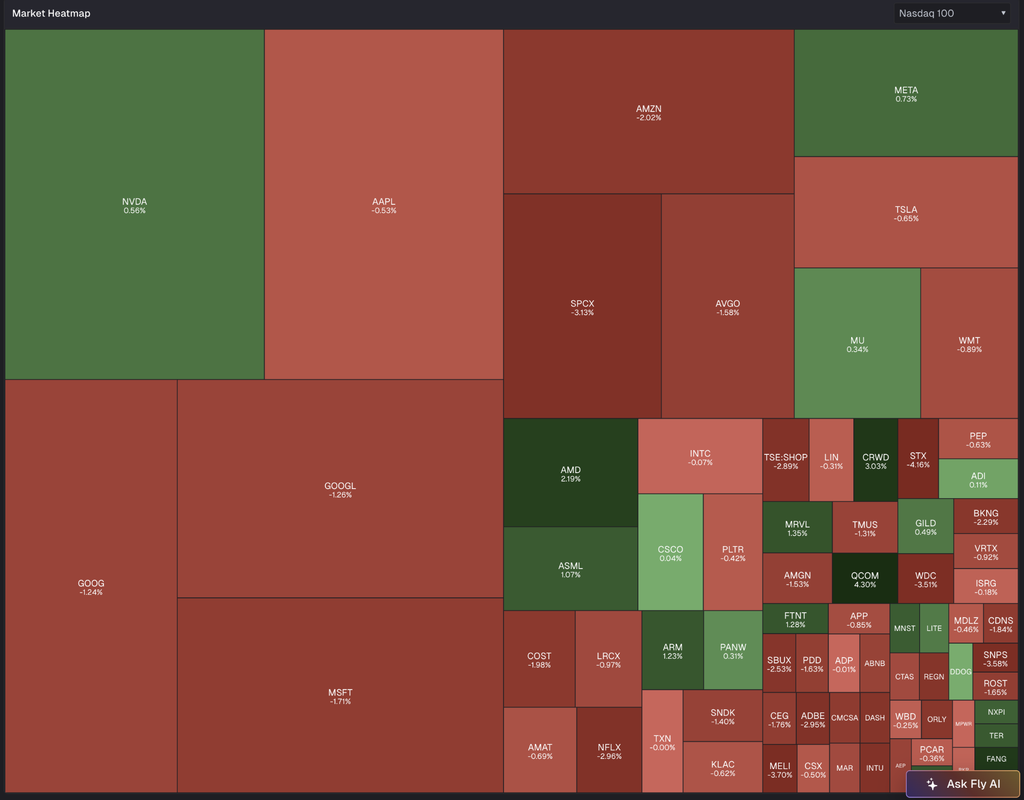
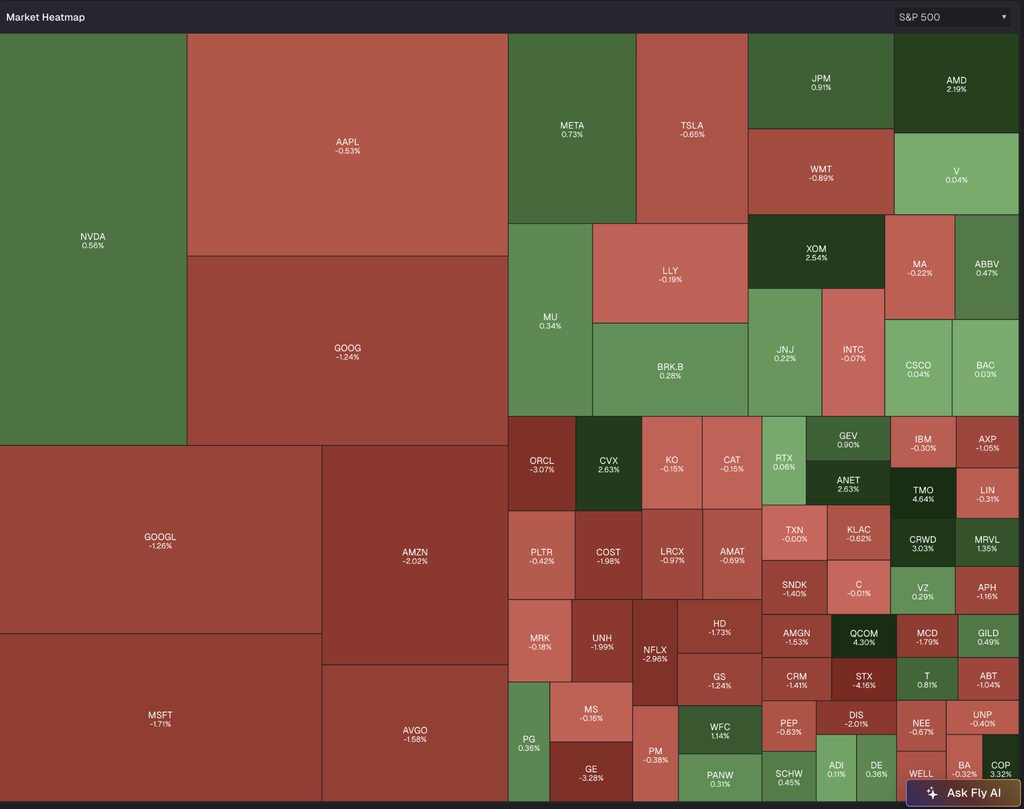
Heat Maps
Position: None