An Ugly End to a Big Week on Wall Street

Bad News
I do mind when there broke bitter tidings,
Woone day, on their ears,
An’ their souls wer a-smote wi’ a stroke
As the lightning do vall on the woak,
An’ the things that wer bright all around em
Seem’d dim drough their tears.
– William Barnes (1862) written in his native Dorset dialect (western England)
The Ugly Stick
Remember a couple of days ago when I pointed out in this column that the Nasdaq Composite had bumped up against its 50-day simple moving average and 21-day exponential moving average? I showed concern, not a warning (I was still net-long), but concern that with those two lines running together that the level could develop into an area of significant resistance.
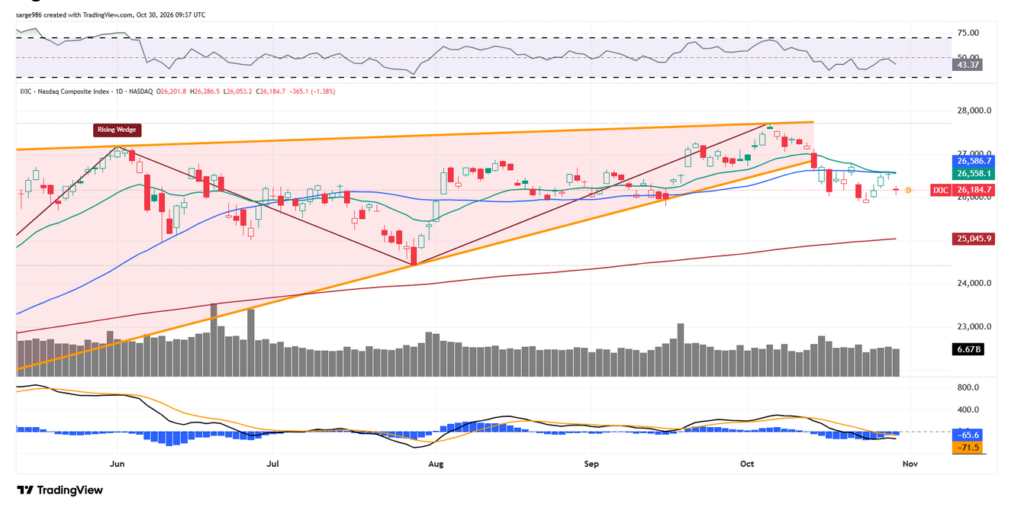
No need to wonder about that anymore. It’s Friday morning. Fri-yay? Well, we may need a weekend after this one. Our old friend, the “Ugly Stick” is out and about. The stick has been looking for victims through the overnight session and has found more than a few.
Where do we even begin? First Intel ($INTC), a Sarge name, beats the Wall Street on both the top- and bottom-lines and then provides some of the weakest guidance I can remember. Without warning. You would think that management might have said something earlier? Nope. Data center revenue was up 78% year over year for the third quarter. That’s super.
But the company should have told us as soon as it knew that the current quarter was off to an awful start and demand for PCs was way off. We can give CEO Lip-Bu-Tan a pass on the mid-October fire at Fab 28 in Israel, but the far-below expectations demand for PCs? Maybe it’s just sour grapes on my part, but we should have been made aware.
Then Amazon ($AMZN), another Sarge name, went to the tape. Earnings miss. Revenue miss. Guidance miss. Stock joins Alphabet ($GOOGL), thankfully not a Sarge name, in the penalty box. There was good news within the Amazon release. Growth at AWS did beat the Wall Street, but was not enough to overcome what happened across the rest of the firm’s businesses. Same story for the Google Cloud, I suppose. Despite my pleadings that the two firms are not very similar.
Want More?
Oh, there’s more bad news, if you have the appetite. Crude oil prices are higher overnight as traders more or less price in a more than telegraphed attack this week coming by U.S. forces on the regime in Iran. The positive takeaway there is the flight to safety that is pushing Treasury
prices higher and yields (interest rates) lower. We’ll take that as I suspect that my bond portfolio is going to have to try to rescue my equity book on Friday.
There’s still more. As reported by a number of news outlets, Binance has apparently suspended all transactions and withdrawals after the world’s largest cryptocurrency exchange fell victim to hackers. According to several of these reports, hackers had compromised a Binance engineer’s laptop computer. There also may be several other points of breach. Bottom-line? Somebody stole a rough $6.3 billion in funds/crypto, easily the largest heist of its kind since the advent of cryptocurrencies as an asset class.
Founder Changpeng Zhao claimed that user funds were safe, but the company did suspend all deposits and withdrawals as its team conducts security checks, freezes funds and works with law enforcement to identify the bad actors. The Wall Street Journal is reporting that cybersecurity research firms TRM Labs and Pangolin Intelligence believe that the heist may have been conducted by North Korea’s TraderTraitor hacking group. This group has been behind many of the largest crypto hacks in recent memory. Bitcoin and Ethereum are both trading lower overnight.
Fun With Numbers…
On Thursday, the U.S. Bureau of Labor Statistics posted an above consensus (as we spoke about here ahead of the event) 3.4% (q/q, SAAR) gross domestic product growth rate for Q3 2026. The third-quarter of 2026 was the hottest quarter for economic growth for the U.S. since Q2 2024. Huzzah! Party on, dudes! Not exactly.
Economic activity for the quarter was driven by two significant forces. Gross Private Domestic Investment contributed growth of 3.27% toward that 3.4% (which is obviously a net total). This force was supported to a great degree by investment in AI-related equipment and inventories. Non-residential investment accounted for 1.78% of the 3.27%. Residential investment actually subtracted 0.12%.
The consumer was active. Personal consumption expenditures contributed 2.52% to the headline 3.4% pace. This was the strongest quarter for the U.S. consumer since Q4 2024. Seems odd, right? Was inflation a factor? Shouldn’t be. These numbers are adjusted for inflation. That said, the World Cup was a net contributor, which brought a huge boost in foreign tourism. The pace of consumer spending was said to have slowed after that soccer tournament had ended.
What else had a significant impact? Federal spending contributed 0.91% to the headline. The largest drag on GDP came from the balance or should I say, imbalance of trade. Net imports/exports put a -3.32% hickey on the headline pace of 3.4%. So, a strong quarter? Guess so … if one sells what the further development of AI requires. Or soccer jerseys.
Defensive Is Best Offensive
Anyone else notice that on Thursday, the four defensive sectors led the 11 S&P sector SPDR ETF performance tables for the day? Then came the five cyclicals. Then came tech ($XLK) and communication services ($XLC). It’s as if “they” knew that both Intel and Amazon were going to spit the bit. As I go to print this morning, INTC is down 26% while AMZN is down “just” 7%.
OK. Helmets and flak jackets, gang. Chinstraps buckled. Three sources of water. Clean socks in the ruck. Gas mask on the hip. Meet you on the parade deck in fifteen minutes. Squad leaders take charge. Don’t make me come get you.
Economics (All Times Eastern)
08:30 – Employment Cost Index (Q3): Expecting 0.8% q/q, Last 0.9% q/q.
09:45 – Chicago PMI (Oct): Expecting 56.1, Last 58.8.
1:00 – Baker Hughes Total Rig Count (Weekly): Last 603.
1:00 – Baker Hughes Oil Rig Count (Weekly): Last 460.
The Fed (All Times Eastern)
12:00 – Speaker: San Francisco Fed Pres. Mary Daly.
12:30 – Speaker: St. Louis Fed Pres. Alberto Musalem.
Today’s Earnings Highlights (Consensus EPS Expectations)
Before the Open: CVX (4.87), XOM (4.12), ABBV (3.73)
At the time of publication, Guilfoyle was long INTC, AMZN equity.
