Retail Sales Good/Import Prices Bad

The following is from Peter Boockvar:
In nominal terms, August retail sales were stronger than expected with the core rate of spend (ex autos, building materials, food and gasoline) rising 1.4% m/o/m, well better than the estimate of up .5% and follows a .4% drop in July.
Auto sales rose .6% m/o/m and by 1.7% y/o/y while the sales of building materials fell for a 2nd month, by .2%. After two months of declines, food/beverage sales rose .4% and sales at restaurants/bars were strong, rising by 1.2% m/o/m.
Elsewhere, online retail sales led the way and jumped 2.6% m/o/m and up 10.4% y/o/y. Sales gains of note were also seen in furniture, electronics (notwithstanding what MMM said), clothing, sporting goods, general merchandise which includes department stores, health/personal care, and misc which includes dollar stores, convenience stores, pet stores, etc…
Bottom line, retail sales were good, with some contribution from volume and the balance due to price.
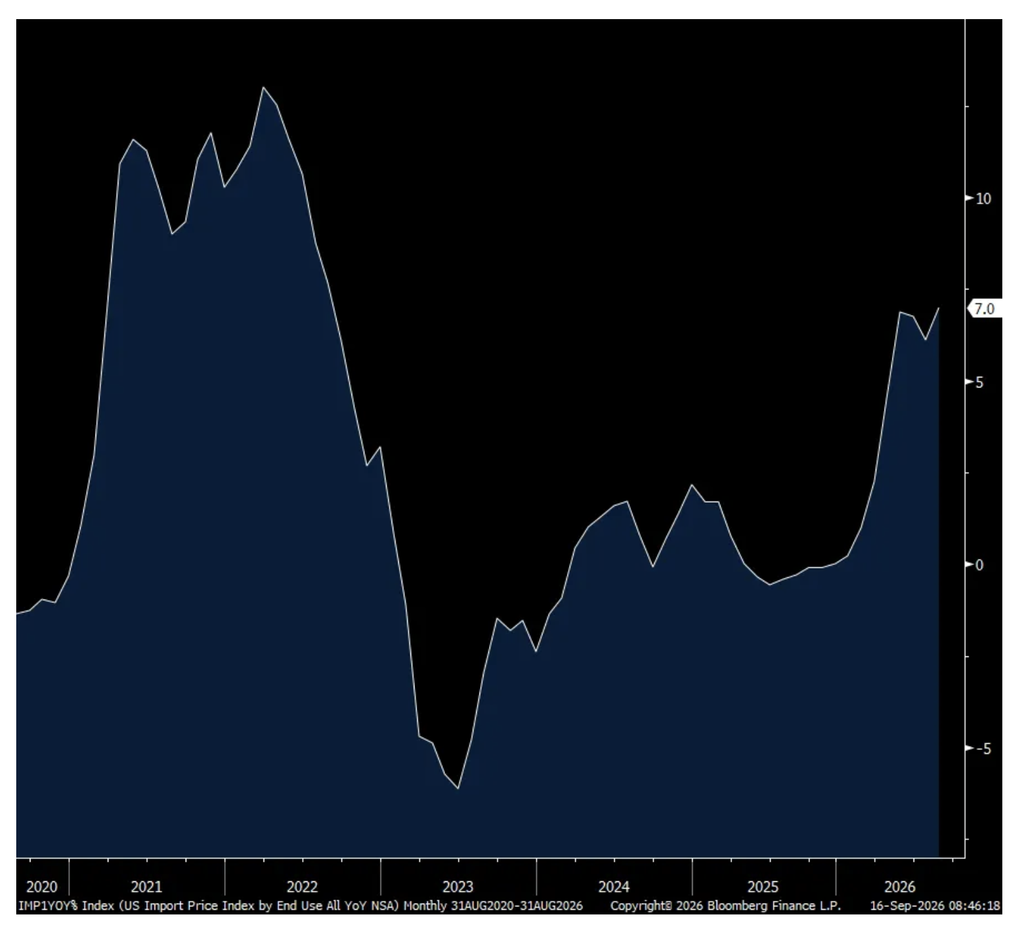
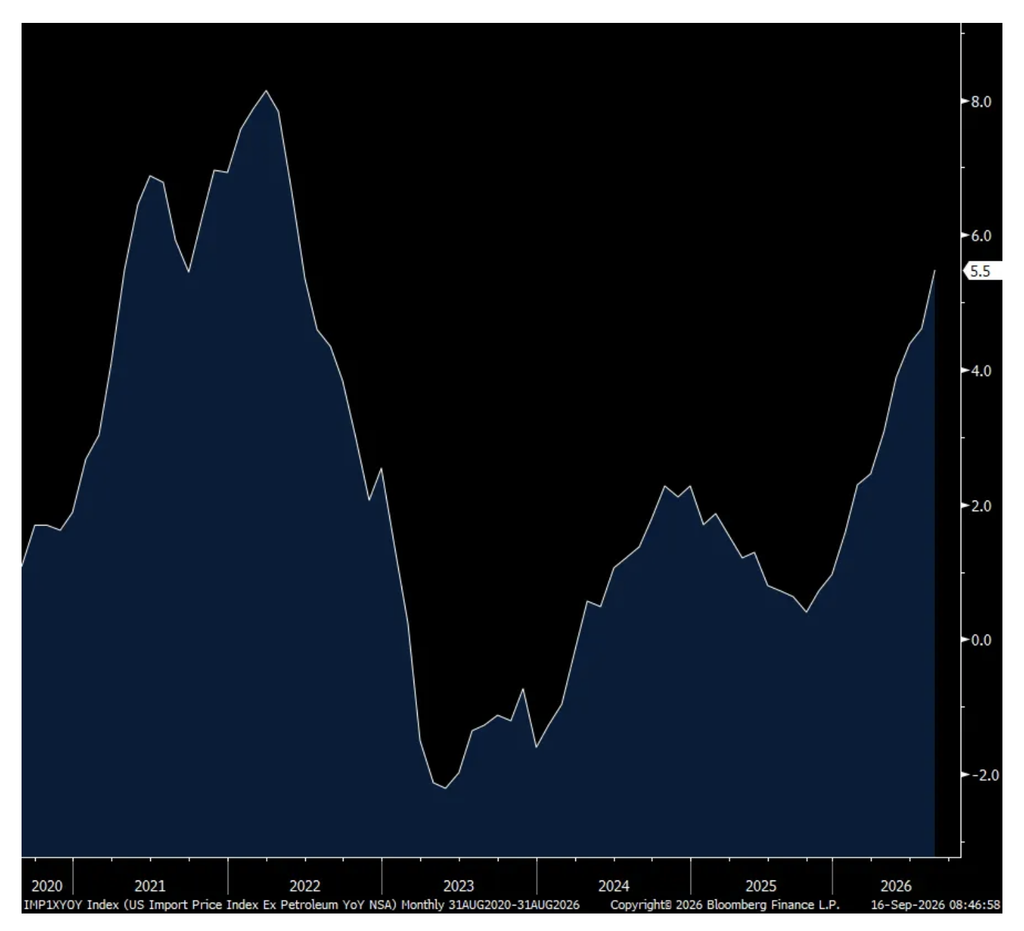
Inflation continues to rise with respect to import prices. They rose .7% m/o/m in August, two tenths more than expected and after a .3% drop in July. They are higher by 7% y/o/y. Ex petro saw prices jump by .8% m/o/m and 5.5% y/o/y. Taking out both fuel and food saw prices up by .8% m/o/m and 5.6% y/o/y.
The culprits in the rise in import prices outside of food and energy are from industrial supplies, up 2% m/o/m, capital goods up .9% and consumer goods ex autos higher by .5%. Auto import prices were flat.
Bottom line, I’m confident we have an inflation problem throughout the supply chain. I’m not confident that the Fed can do anything about it.
Import Prices y/o/y
Import Prices ex petro y/o/y
Position: None
