Collecting Your Questions for Our Next Set of Office Hours

Be sure to mark your question with #officehours in the Portfolio Forum
Be sure to mark your question with #officehours in the Portfolio Forum
Just opened a small position in $GOOG at $280. There is good support near $271, so I see it as a high-reward, low-risk opportunity. Now that the stock has dropped 13% today and nearly 30% since May, GOOG is reasonably valued.
We also added to our initial position in $META, and now have a cost basis of about $630 in that stock. This plan was laid out in a previous article.
Writing up GOOG and META with charts and explanations now, article to follow tomorrow morning.
We can see several reasons for a deal, but the real question is how much is Marvell willing to pay up?
Housekeeping item.
I have covered my $GRNY short at $27.38.
I plan to re-short on a rally.
Position: None
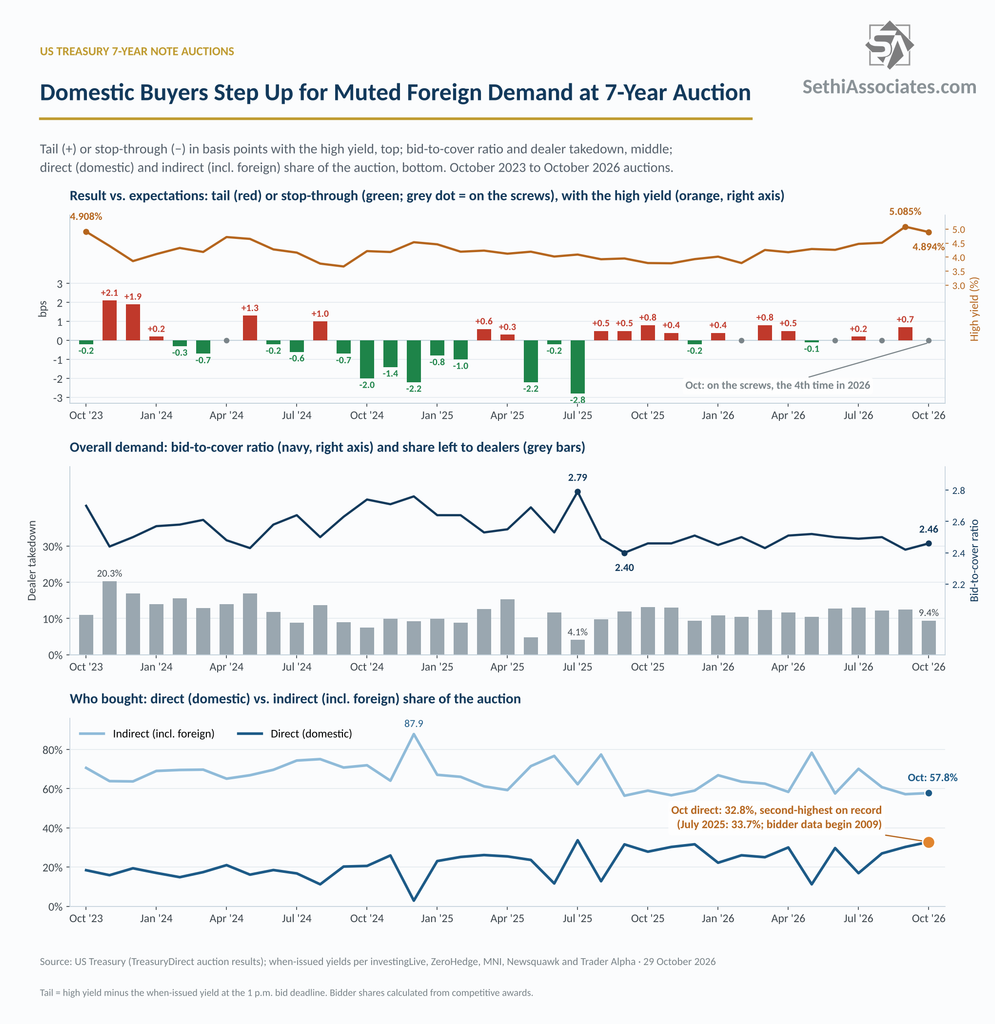
The last of this week’s three coupon (more than one year in maturity) Treasury auctions came today in $44 billion of 7-year notes, and it continued the week’s theme of domestic buyers picking up the slack from softer foreign demand.
At Monday’s 2-year, indirect bidders (which include foreign buyers) fell to the lowest since November 2021 as direct (domestic) bidders took a record share. Indirect demand recovered somewhat in Tuesday’s 5-year but was still below the six-month average, and today’s 7-year was a similar story but direct bidders took the second-largest share on record keeping the end result in line with expectations and leaving dealers with less than at either of the previous two auctions (9.4%, versus 13.0% at the 2-year and 10.6% at the 5-year)
The sale cleared at 4.894%, down from 5.085% in September (the highest on record for this maturity). It came in “on the screws” (right in line with expectations) against a when-issued of 4.894%, much better than the +0.7 basis point tail in September (the biggest since March), and versus a six-month average tail of +0.2 basis points. Interestingly, it was the fourth 7-year auction to price on the screws in 2026.
Looking at the rest of the metrics:
-Overall demand (bid/cover) rose to 2.46 from 2.42 in September, but stayed below the six-month average of 2.49.
-Indirect bidders (which include foreign buyers) edged up to 57.8% from 57.2% in September (the lowest since November 2025), but remained well below the six-month average of 63.7%.
-Direct (domestic) bidders jumped to 32.8%, the highest since July 2025 and the second-highest in Treasury data back to 2009 (after July 2025’s 33.7%), from 30.3% in September and well above the six-month average of 24.2%.
-That left dealers with 9.4%, the lowest since December 2025, down from 12.5% in September and below the six-month average of 12.1% (the record low was 4.1% in July 2025).
So at all three auctions this week, indirect bidders took a below-average share (45.7%, 60.0% and 57.8%), which was offset at least in part by direct bidders taking more (41.3%, 29.4% and 32.8%).
Break in!
It has been reported that a tanker has been struck in the Strait. This likely explains the market’s drop to intraday lows.
Position: None
Investor response is very different to earnings announcements from Samsung Electronics and SK Hynix. Here’s why, and what investors should really be watching.
Position: None
Position: None
September core PCE rises the most since February while real incomes fall.