More Bullish Tech Headlines

In addition to the well-received SpaceX ($SPCX) headlines detailed last night (SpaceX Climbs as Musk Floats Tesla Merger), some other stories are boosting Tech shares this morning:

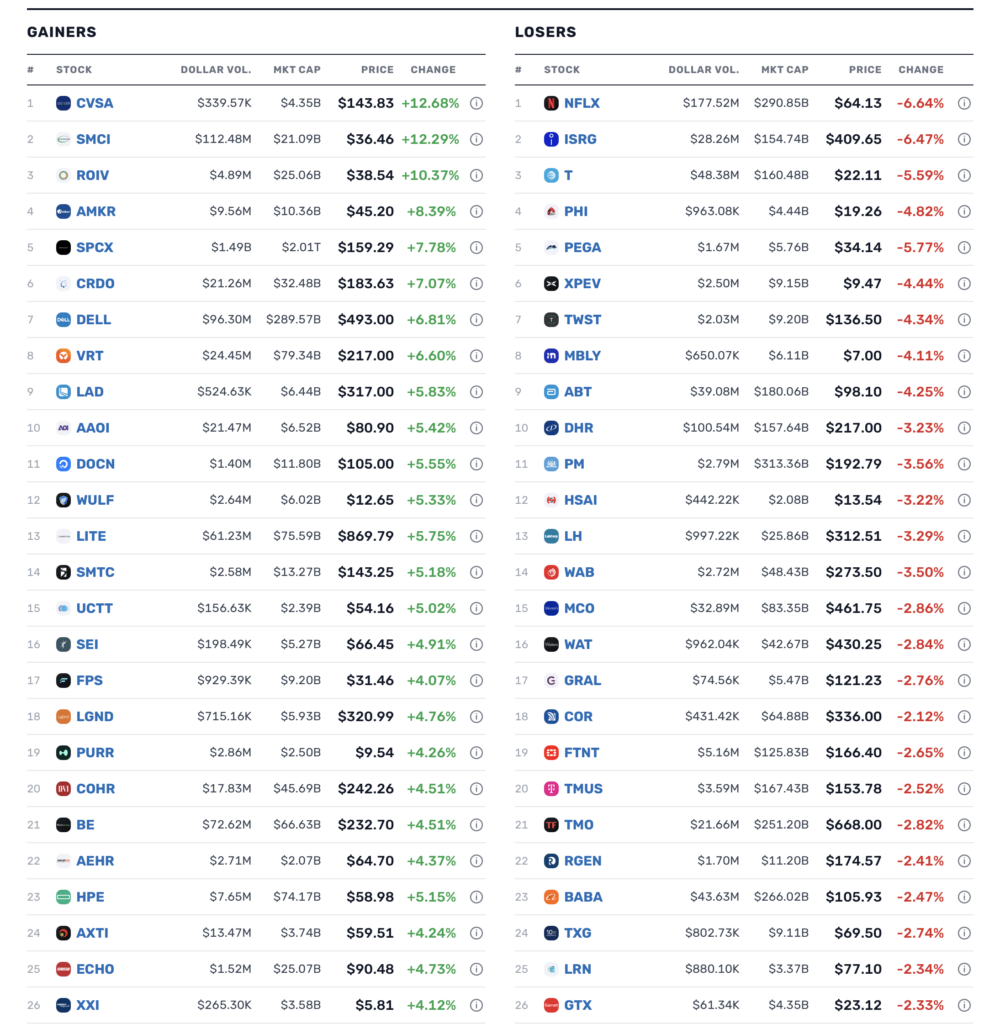
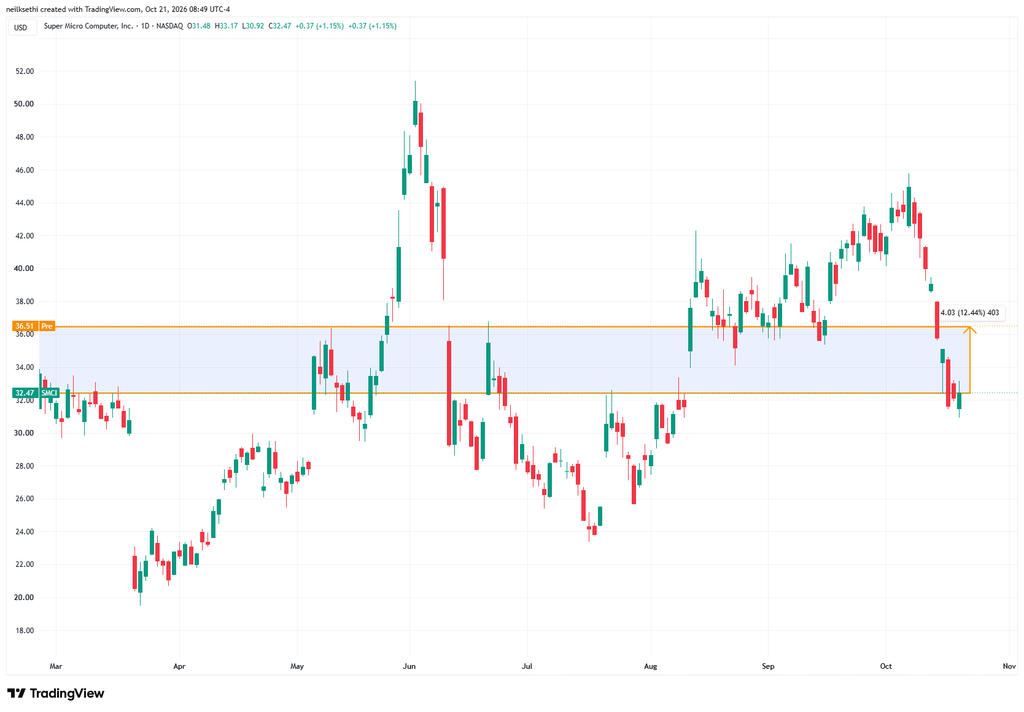
Shares of server maker Super Micro Computer ($SMCI) are up over 12% premarket after the firm released preliminary quarterly numbers for the period ending September 30, saying it expects revenue of $18.5 billion to $19.5 billion for the quarter. That compares with its earlier forecast of $14.5 billion to $15.5 billion and an average analyst estimate of about $15 billion. The company also raised its gross margin forecast to 12% to 12.5%, from 10.4% to 10.8%
In addition, the Wall Street Journal is reporting that Anthropic’s draft prospectus signals coming spending on computer and power of as much as $750 billion in coming years, with $111 billion on contracts with Alphabet’s Google Cloud ($GOOGL), $110 billion with Amazon Web Services ($AMZN) and $31 billion with Microsoft ($MSFT) “regardless of actual usage.”

Anthropic also agreed to spend up to $86 billion renting Nvidia ($NVDA) chips from smaller AI cloud providers Nscale and Lambda.

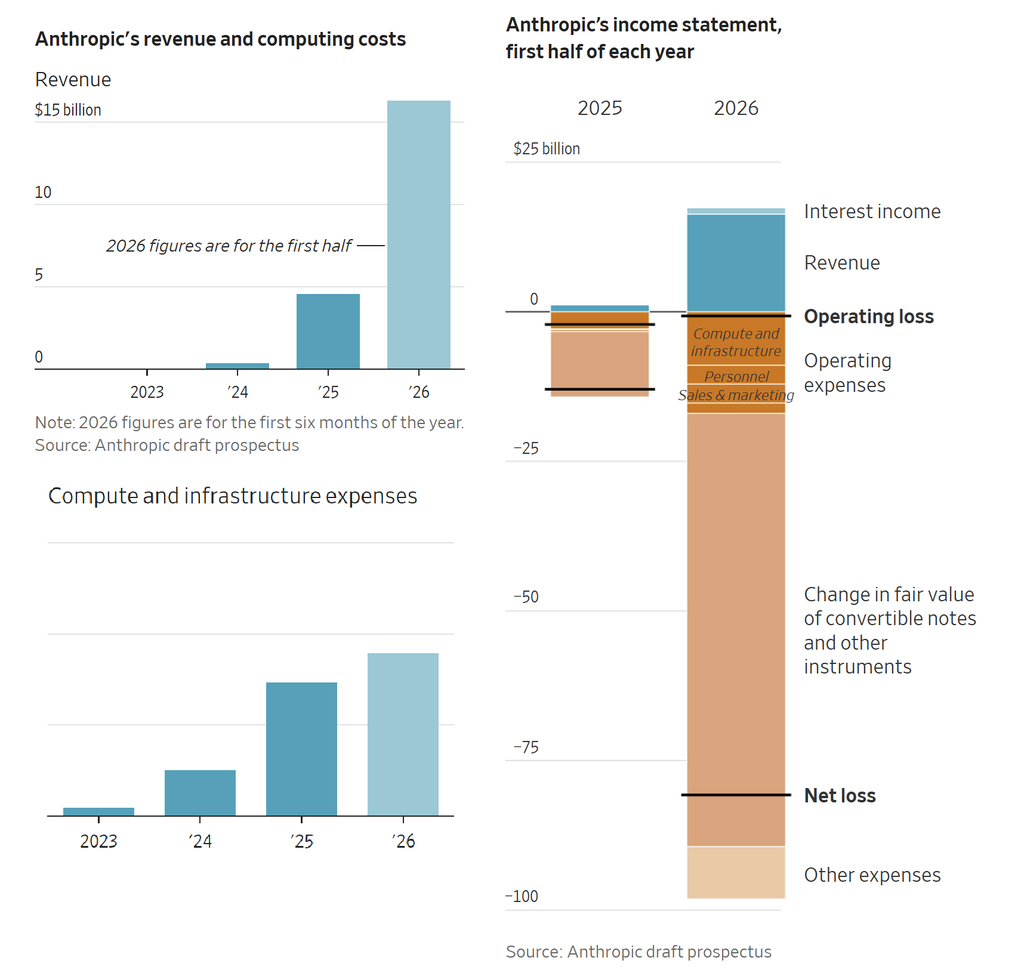
And sales are growing at a blistering pace. The Journal reported revenues had grown to $16.3 billion in the six months ended June 30, up from $1.1 billion in the year-earlier period. That outpaced the nearly $9 billion on computing capacity and infrastructure, up from $2.3 billion.

Still it recorded a net loss of $80.7 billion, the vast majority ($72 billion) “tied to changes in the value of convertible notes and other instruments the company issued to raise funding.”
And finally, several Asian countries with large tech exposure (South Korea, Japan, Taiwan, etc.) are reporting strong export numbers led by semiconductor and other Tech shipments.

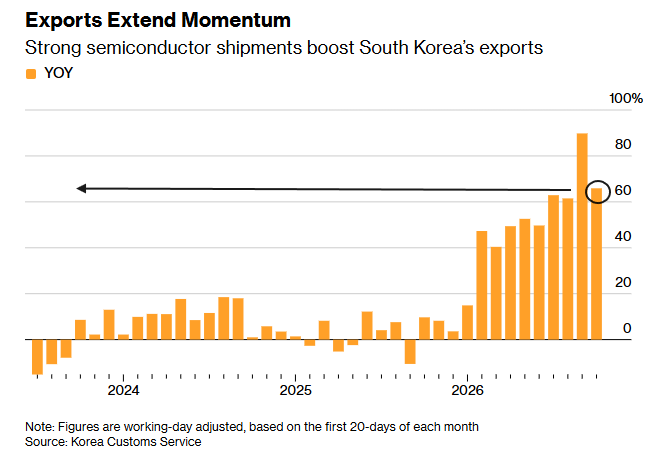
  • Bloomberg reports that South Korea’s exports the first 20 days of October, adjusted for working-day differences, rose 65.9% from a year earlier. While down from the 89.8% increase during the same period in September, it is otherwise a record. Semiconductors surged 222.5% from a year, while products increased 68.3%, and automobile exports almost 41%.
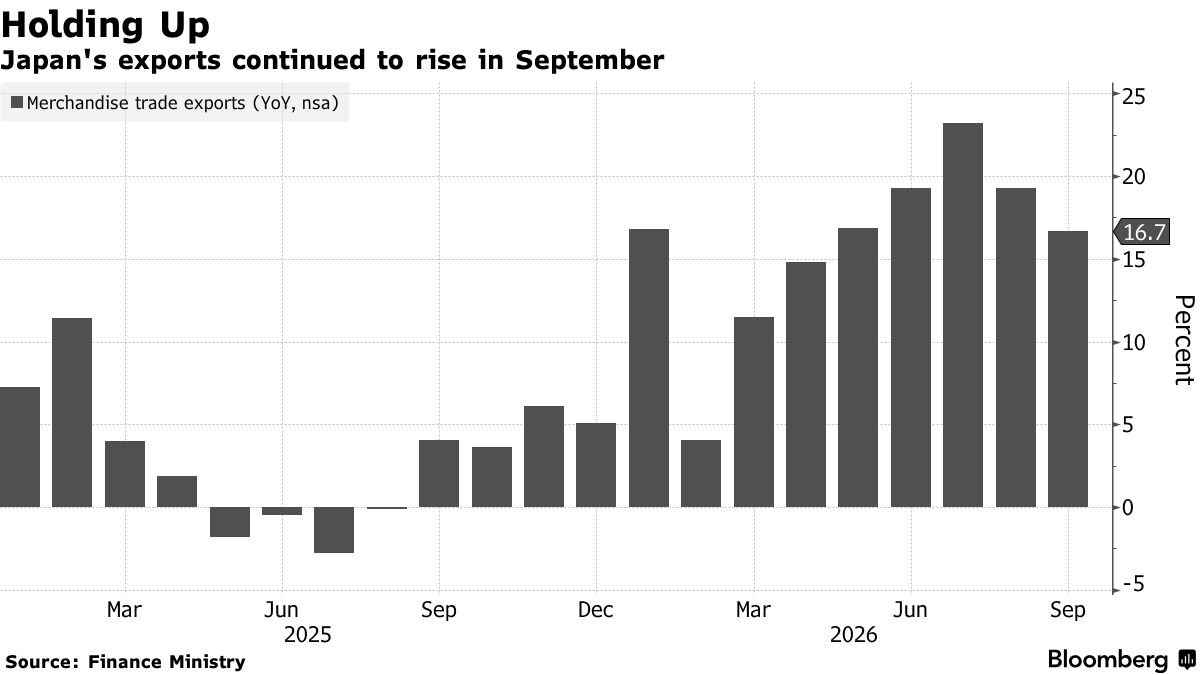
  • Also from Bloomberg, Japan’s September export growth rose 16.7% from a year earlier. While it missed expectations for a 21.2% increase, shipments of semiconductors and chip-making equipment surged 49.4% and 43.9% respectively (autos were +15.1%). Shipments to the US gained 22.9%. Those to China and the European Union advanced 8.6% and 10.5%, respectively.
  • Reuters reports that Taiwan’s export orders jumped 62.4% in September to a record $114.21 billion “credited to strong demand for AI, high-performance computing and cloud services applications.” The Ministry of Economic Affairs forecast October as rising between 62% and 67%. “Taiwan’s orders ​in September for telecoms products were up 87.3% from ​a ⁠year earlier, while those for electronic products jumped 71.0%.”

Netflix Down, SpaceX Up: Upside/Downside Movers in the A.M.

Upside

– $SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)

– $SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)

– $CRDO +7.2%, $VRT +6.7%, $DELL +6.9%, $LITE +5.6%, $HPE +5.0%, $COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)

– $WDC +4.0%, $SKHY +3.7%, $SNDK +3.7%, $STX +3.6%, $MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)

– $APLD +4.0% (Texas AI data-center agreement and bullish analyst action)

– $INTC +2.3%, AMD +2.1%, $NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)

– $TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)

Downside

– $TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)

– $NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)

– $ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)

– $T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)

– $DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)

– $TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)

– $ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)

SpaceX (SPCX): Post-Q3 Target Raises, October 21

The SpaceX ($SPCX) quarter beat on revenue and EBITDA across all three segments (Intelligence/AI, Space, Connectivity). The only blemish was a miss on Starlink subscriber adds, offset by better pricing. Guidance calls for revenue of $33B to $37B by Q1 FY27. Management says it expects 2 to 3 GW of compute by year-end 2026 and plans to add 10 GW in 2027, well above prior expectations, and told JPMorgan it is not considering raising equity.

Price targets:

  • JPMorgan: $500 from $240 (Overweight). Biggest move. Says the forward driver is superintelligence, not the segment beats.
  • Cantor Fitzgerald: $345 from $246 (Overweight). Sees $500B to $1T in year-end 2027 ARR, self-funded compute expansion, and chip supply constraints giving SpaceX pricing power.
  • Barclays: $300 from $254 (Overweight). Model update on the beat.
  • Morgan Stanley: $300 reiterated (Overweight). Says the story is only now getting interesting.
  • Citi: $240 from $200 (Buy). Also opened a 90-day upside catalyst watch, pointing to Q4 beat-and-raise continuation and Starship Flight 15 as a major reusability catalyst.
  • UBS: $230 from $210 (Buy). New compute deals ramping in Q4, Starship catch milestones, Grok improvements.
  • TD Cowen: $224 from $200 (Buy). Estimates up on the beat.
  • Susquehanna: $176 from $173 (Neutral). The lone holdout. Flags execution risk on the compute buildout and dependence on Starship commercialization.

More Tales From Nvidia: And Lessons of AI Burn From SpaceX (Issue #263!) 

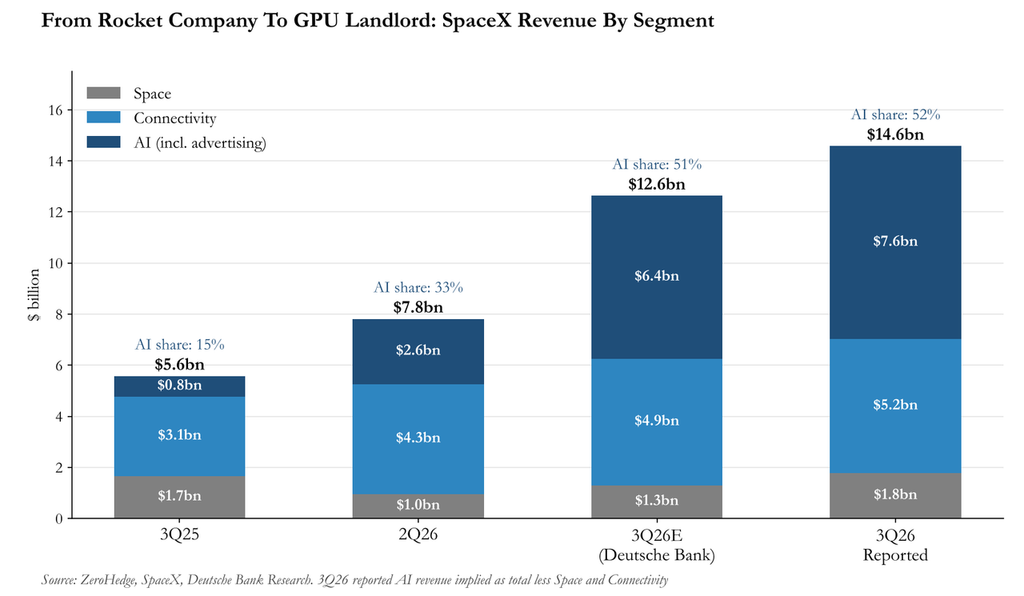
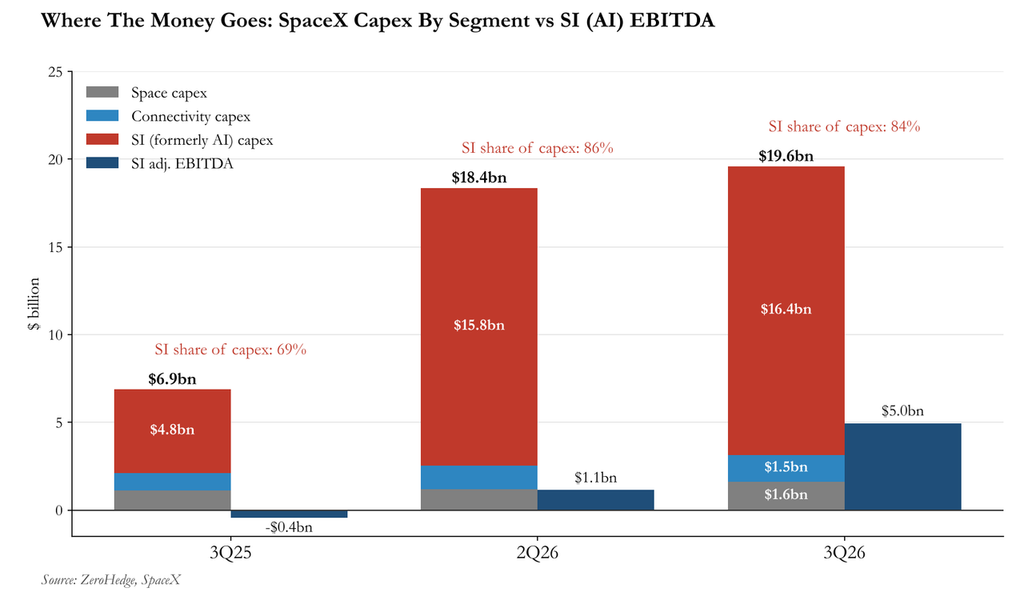
Below are two charts that speak volumes about the economics of AI. 

SpaceX ($SPCX) just reported 3Q2026. 

All of a sudden, AI (ergo data centers) is their biggest business. Along with that, cash and cash equivalents came in at $51.29 billion, versus an estimate of $91.2 billion. CAPEX for their AI segment was $16.4 billion versus $5 billion of EBITDA. Is this compelling?

I guess they can buy all the revenue they want; good thing the cost of financing it is so low??? Feels like double dilution is on the come here. Continued issuance to do whatever they are doing chasing WeWork landlord revenue, and dilution to potentially acquire Tesla ($TSLA), which is becoming more and more apparent. 

Clearly Elon Musk wants to goose SPCX stock where he has much more of his net worth (~70%) to acquire TSLA (~25%) to hide it, on more favorable terms for SPCX (ergo himself).

This is the same trick Musk used when Tesla acquired Solar City. Hide the biz that can’t meet its promises, then to the next B.S. story.

Boy did that thing burn cash, holy heck, never seen a whiff this bad. Good thing borrowing costs are low these days. Oopsie:

In any case, at the rate AI is burning cash (and sucking down credit and equity), the 10-year Treasury will be yielding 6% in no time!

Position: None