SPY Move

I added to my $SPY short at $768.29.
Positions: Short SPY S
Positions: None.
After AI infrastructure funding deals and learnings from Celestica and Cadence Design, we’re making several moves.
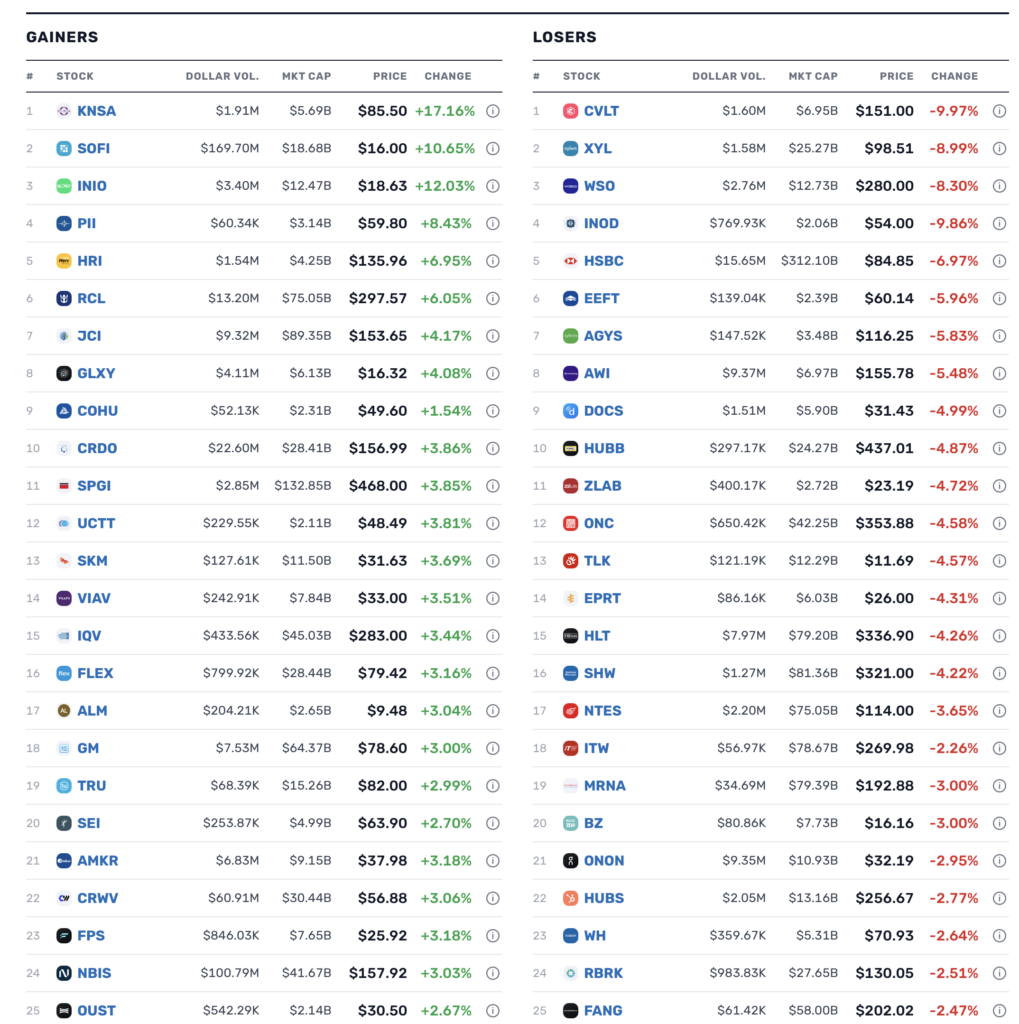
– $MFIC +23% (ARCC agrees to acquire it for $10.88 per share in cash and stock, valuing the transaction at about $2.6B)
– $INIO +14% (record Q3 results and FY26 revenue and EBITDA outlooks were raised)
– $CLS +12% (Q3 beat, FY26 outlook raised and initial 2027 guidance called for 90% revenue growth on accelerating AI-infrastructure demand)
– $SOFI +11% (record Q3 revenue and EBITDA, strong member growth and a raised FY26 outlook)
– $FER +9.9% (no clear fresh catalyst identified; unusually large, liquid move ahead of 9M results after the U.S. close)
– $RCL +5.3% (Q3 beat, bookings remained strong and the full-year profit outlook was raised)
– $CRDO +4.3%, $SKHY +3.2%, $COHR +2.7%, $AMKR +3.6%, $LITE +2.6%, $AVGO +2.9% (AI-chip and optical-connectivity names rise as the CLS outlook reinforces accelerating hyperscaler demand)
– $JCI +4.3% (Q4 beat and the FY27 profit outlook topped expectations)
– $SPGI +3.8% (FY26 outlook raised and a strategic review of Capital IQ businesses was launched)
– $NBIS +3.7%, BE +3.3%, CRWV +3.6%, VRT +2.2% (AI-infrastructure names gain after CLS said customer demand forecasts continue strengthening into 2027 and 2028)
– $NCLH +2.2%, CCL +2.7% (cruise peers rise after RCL beat expectations and raised its full-year profit outlook)
– $CDNS +1.8% (Q3 beat, FY outlook raised, backlog reached a record $8.2B and a $2.5B buyback was added)
– UPS +1.8% (Q3 beat and FY26 revenue and profit forecasts were raised as shipment mix and cost reductions improved)
– $XYL -8.5% (Q3 update disappointed, with investors focusing on softer revenue expectations)
– $WSO -8.3% (Q3 profit missed expectations)
– $HSBC -6.7% (Q3 revenue and pretax profit missed expectations, outweighing a new $1B buyback)
– $HLT -4.4% (Q3 earnings beat, but revenue missed and the raised RevPAR outlook was not enough for elevated expectations)
– $SHW -3.8% (Q3 results and outlook disappointed as housing-linked demand remained soft)
– $ONON -3.3% (no clear fresh catalyst identified; unusually large, high-volume premarket decline)
– $MAR -2.0% (hotel peer slips in sympathy with HLT after its revenue miss)
Earnings from Boeing and Welltower, prepping for Paccar’s results plus other headlines moving the market this morning.
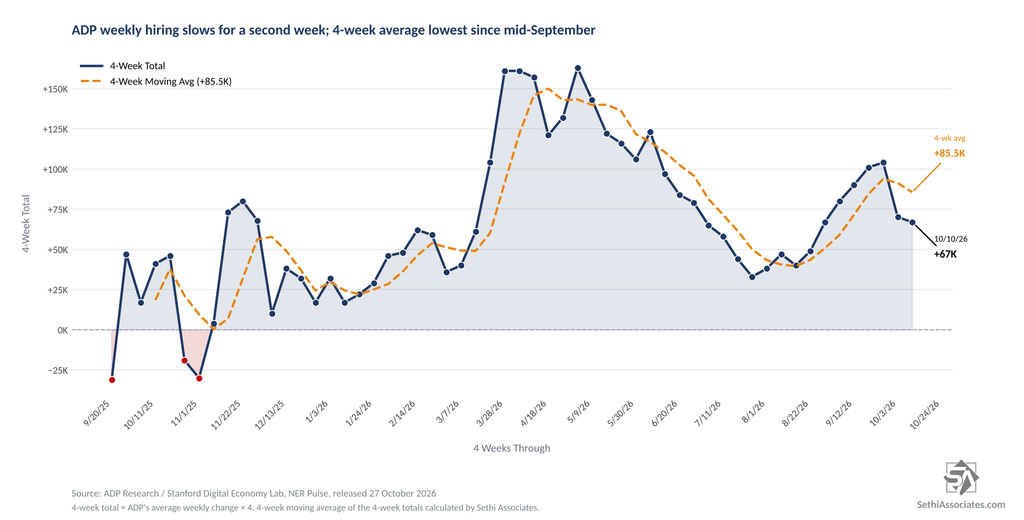
According to ADP’s NER Pulse, private employers added 67,000 jobs, or 16,750 a week, in the four weeks ending October 10, a second week of slowing and the fewest since the period ending August 29. It also revised the prior week down to 70,000 from 74,000.
The four-week moving average of those totals also fell for a second week, to 85,500, the lowest since the period ending September 19. That’s down from a peak of 93,750 in the four weeks ending September 26.
The pace remains healthy, though. At roughly 72,600 a month, it’s above most recent estimates of breakeven job growth, the pace needed to hold the unemployment rate steady. The Federal Reserve Board puts that at “less than 10,000 new jobs per month in 2026,” and the St. Louis Fed estimates a range of 15,000 to 87,000.
ADP’s next report will be its monthly report November 4th.
Source: TipRanks