Warsh, Bessent and the Battle for Long-Term Treasury Yields

Let’s discuss what’s pressuring yields, steps that can be taken, and the beneficiaries so far.
Let’s discuss what’s pressuring yields, steps that can be taken, and the beneficiaries so far.
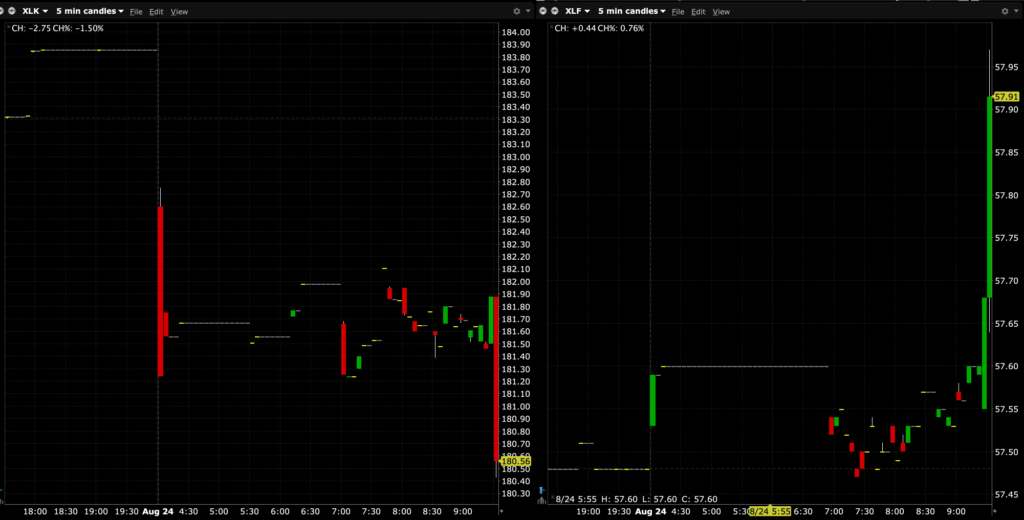
Chart from 9:35 a.m. ET
Positions: None.
From my pal “Meet” Bret Jensen:
Bret Jensen
3m ago
The price of the AI infrastructure buildout will continue to climb but will not result in additional compute capacity. Just higher costs.
Some of Nvidia Corp.’s biggest customers have been told that the prices of servers containing its artificial intelligence chips are going up more than 15% in many cases with memory chip costs soaring. The price hikes will go into effect on systems shipped early next year and will impact systems including those with the flagship Vera Rubin and Grace Blackwell chips
1
Reply
Share
Positions: none
The following is from Peter Boockvar:
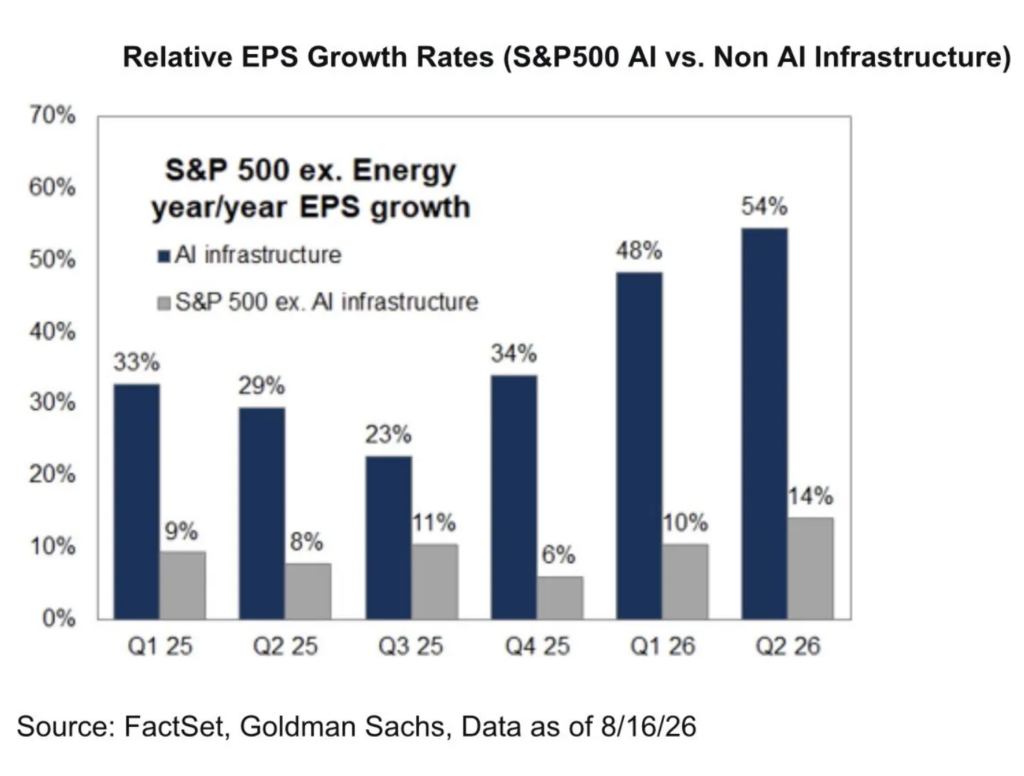
My friend Cameron Dawson at NewEdge Wealth had a great chart over the weekend breaking down the earnings growth contribution from AI infrastructure vs everything else. I will add, that ex AI infrastructure includes financials where the big money center banks are benefiting from robust capital markets, which includes AI financing and also energy stocks that of course was helped by higher crude and product prices.
I bring this up to highlight again how much economic growth, earnings, margins and stock prices depends on this GenAI data center construction.
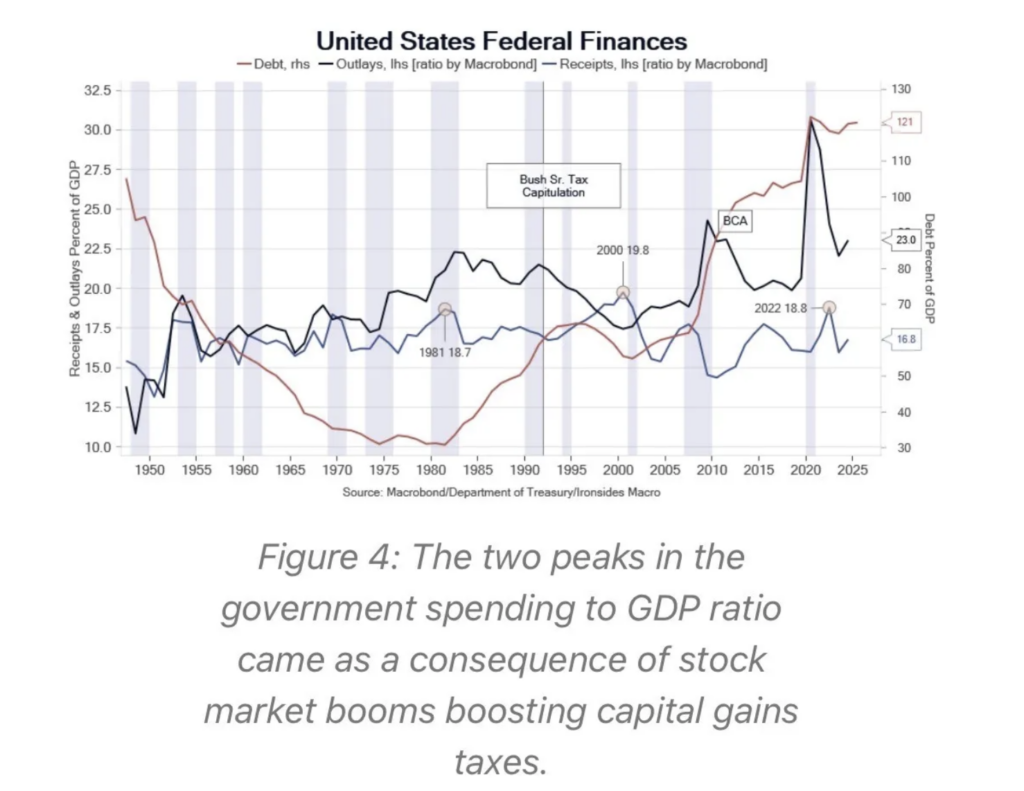
Another chart I saw over the weekend that resonated and something discussed here in the past was from my friend Barry Knapp at Ironsides Macro as we all debate the hedge fund like move by Scott Bessent who essentially shorted long dated US Treasuries because he didn’t like the rise in rates, whether due to excessive supply, both corporate and Treasury, or something else, like JGB yields or inflation, I’ll add. With respect to the deficit side, it’s not politics to say that we cannot tax our way out of this; it is the math instead as the biggest problem is our spending largesse. That is seen in this chart.
The long term average with respect to tax revenue as a % of GDP is about 17% whether tax rates were up or down and that is where we stand about now. Spending as a % of GDP has a long term average of about 20% vs 23% today. Again, it’s the math.
With respect to the Japanese, the BoJ and the JGB market, I saw a Reuters headline last night that said “BoJ considering quicker pace of rate hikes.” Markets aren’t responding to it just yet as let’s get the September hike under our belt first.
I’ll argue again that the Treasury attempt to cap long rates by issuing more short-term paper as the financing tool will tether US government interest rate expense ever closer to what the Federal Reserve does with the fed funds rate. I don’t think this is something Kevin Warsh will talk about in his speech Friday but it is a new element he’s going to have to deal with. Also, his plan to let markets work more in terms of pricing the cost of capital has now been met with another non-market actor.
While we shouldn’t expect ‘forward guidance’ on policy, he can at least lay out a framework around what will shape his view on the direction of rates based on inflation, growth, etc…Or, maybe we’ll just have to wait for the results of the task forces to get an idea of that.
There was just one earnings call of note on Friday, ahead of a bunch more retail related releases this week and it was from BJ’s Wholesale Club and whose stock rose 5.6%. From them:
Merchandise comps rose 3.1% and was “driven by a healthy balance of traffic and ticket.”
“Our perishables, grocery and sundries division delivered solid comp growth of 2.8% in the quarter, led by grocery.”
With general merchandise, “Consumer electronics continue to lead the way and home was a strong contributor.”
“Gas prices remained elevated during the quarter, and our members continued to seek us out for the value we offer at the pump…Gas prices are about as visible as it gets for consumers. There’s a price on every street corner, and our members know that we offer great value.”
“Taking a step back to assess the consumer environment, the K-shaped economy persists, though we did see some sequential improvement during the quarter. We drove comp growth across all income cohorts, which is encouraging, and our value proposition continues to resonate broadly. That said, the vast majority of our growth continues to be driven by our higher income members, which is consistent with what we’ve seen for some time now.” I bolded to highlight.
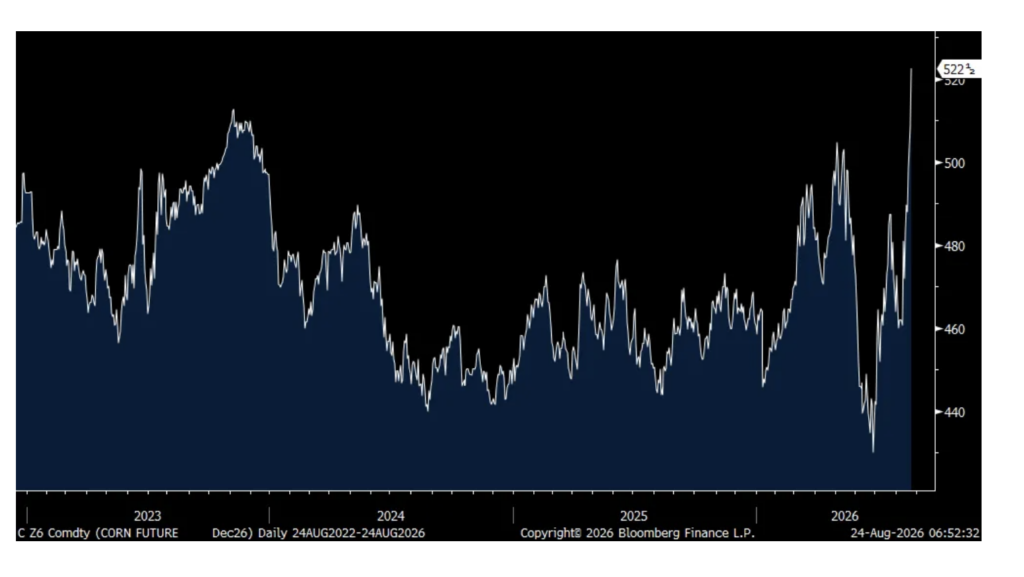
Last week I mentioned the rise in ag prices and our positive stance on this part of the commodity sector believing it was going to join the overall commodity bull market. If you didn’t see, corn today is breaking out to multi year highs, up another 2.7% today. A combination of worries about supply shipments out of the Black Sea and the possibility that the US harvest may not yield as many bushels as expected when seen in a few months.
The Bloomberg Agriculture Index is just about $.20 from the highest level since very late December 2023.
Corn front month
Bloomberg Commodity Index
Despite these planned sales, we’re not making a statement about the stocks involved.
I lost much of my Trulieve ($TRLV) long on expiration and thru assignments last week and on Friday.
I plan to reload $9-$10.
Position: TRLV VS
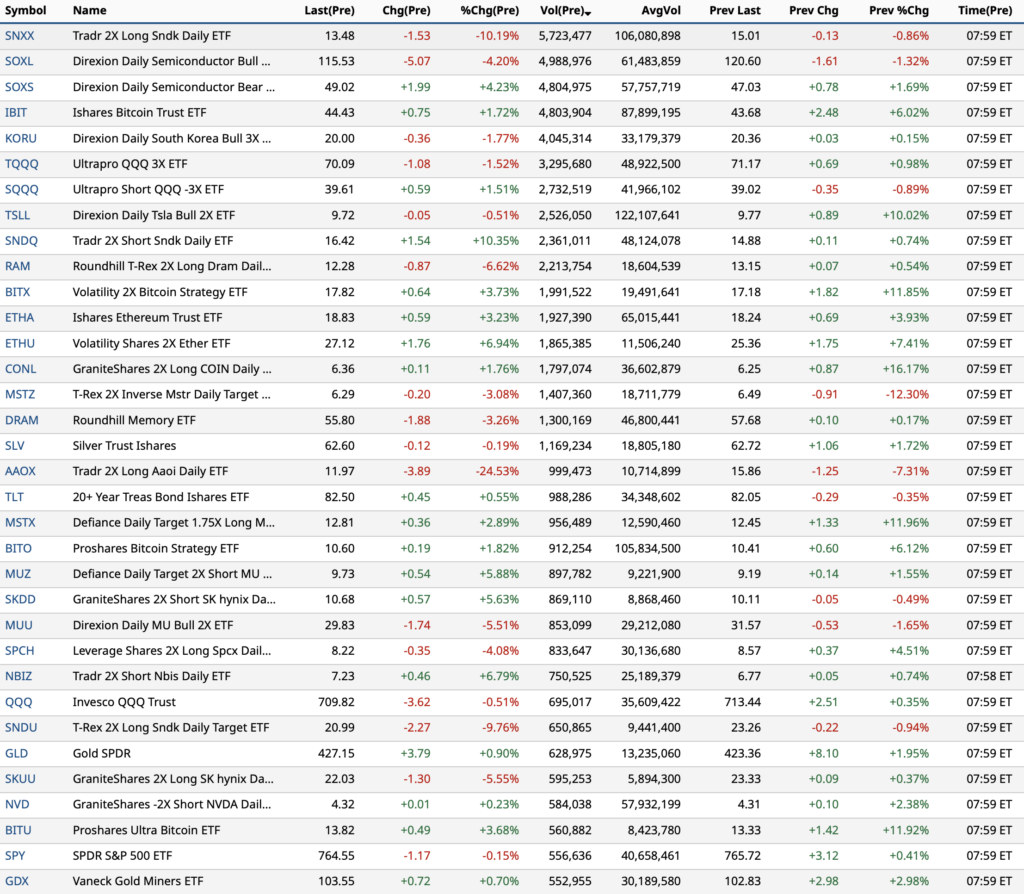
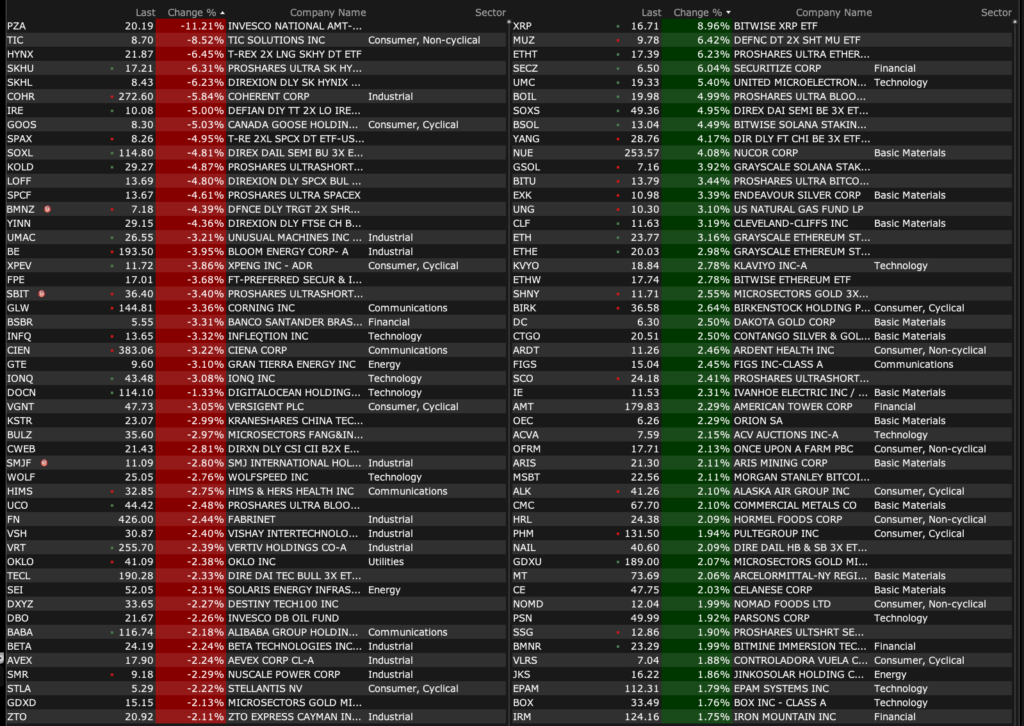
-XPON +76% (acquires Eastern Louisiana oil and gas exploration opportunity for $3.4M)
-NSSC +21% (earnings, color)
-RUM +7.0% (affiliate enters ~$13.7B, 6-yr GPU services agreement with US cloud customer; grants warrant for up to 50.8M shares at $0.01/shr)
-SPRB +5.1% (plans Q4 BLA submission for TA-ERT in Sanfilippo Syndrome Type B)
-PDD +4.4% (earnings, color)
-ZJK +3.3% (secures large-volume AI infrastructure component purchase orders)
-MSTR +2.4% (establishes USD Cash pool; Sells 18.26M MSTR shares for $2.0B net via ATM)
-WULF +2.3% (Kentucky PSC approves agreement for up to 482 MW at Justified Data Campus)
-ALGT +2.0% (Raymond James Raised ALGT to Strong Buy from Outperform, price target: $116)
-RGNX -22% (FDA places clinical hold on RGX-121 for MPS II; BLA resubmission not expected near term)
-AAOI -13% (files to sell up to $600M common stock shares)
-XPEV -6.1% (earnings, guidance)
-AZTA -6.0% (appoints Dr. Martin Madaus interim President and CEO; affirms FY26 guidance)
-GOOS -4.2% (Wells Fargo Cuts GOOS.CA to Underweight from Equal Weight, price target: C$10)
-MRVL -3.2% (trading lower ahead of earnings this week)
-BABA -2.2% (prices HK$80B placement of 710M shares at HK$112.70/shr)
Positions: None.
Positions: None.


