Cannabis Tweet of the Day (Part Deux)

Position: None
Position: None
From Peter Boockvar
Chris Waller gives some forward guidance
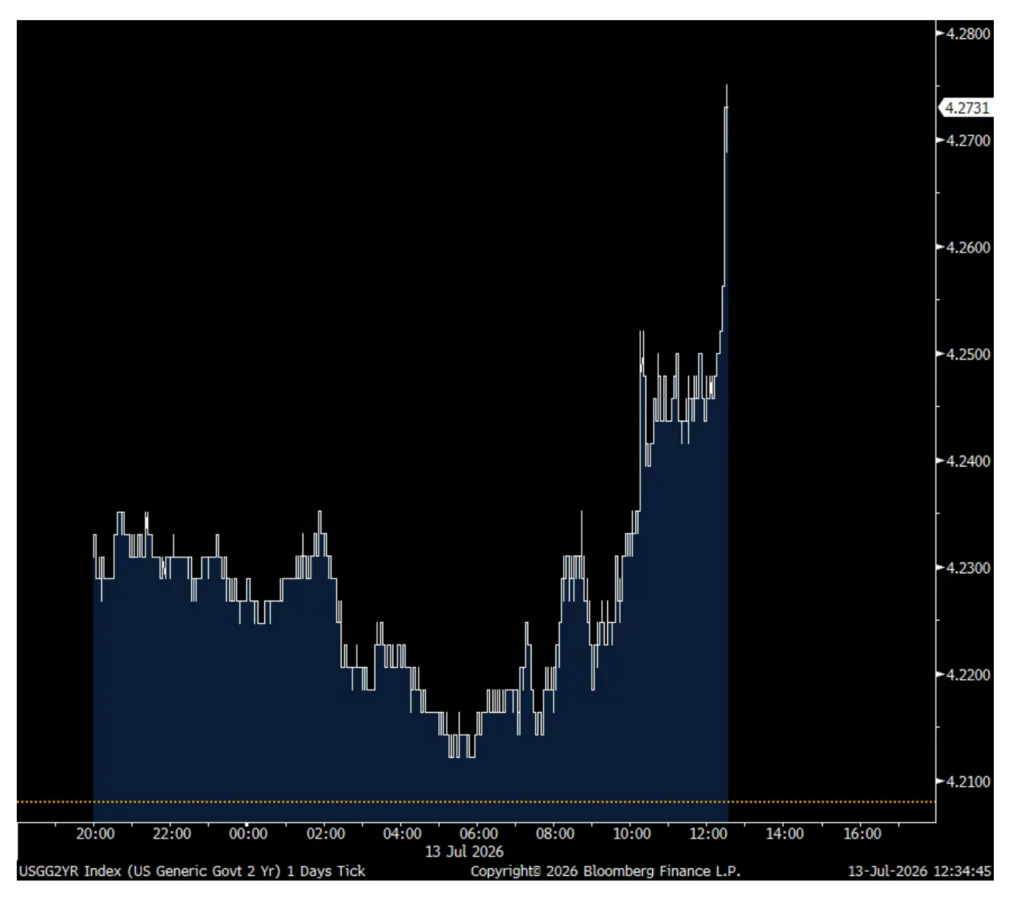
Fed Governor Chris Waller is still ok with forward guidance. In a prepared speech just released he said “If we get another hot reading on core inflation this week, then the FOMC will need to consider tightening monetary policy in the near term.” The next meeting is in 2 weeks and is that ‘near term’? Sounds like it. As of this writing, the fed funds futures is now pricing in a 50% chance of a hike in a few weeks.
Treasury yields are at the highs of the day and see below the 2 yr yield response in particular intraday.
2 yr intraday
* Soros voiced the concept of concentration to Druckenmiller
* Buffett and Munger said it to Berkshire Hathaway investors
* Mae West told it to men
“Too much of a good thing can be wonderful.”
– Mae West
I am now at my largest gross long exposure in cannabis as a percentage of the portfolio than at any time in the last decade.
“(I wonder what kind of a woman you are)….Too bad I can’t give out samples.”
Position: Long MSOS (VL) individual companies
No question the strong stock market has helped, but so has something else!
SanDisk ($SNDK) is part of my high-beta, high-tech short basket.
At $1,714, the shares are now -$640 from their high of $2,354 achieved only three weeks ago.
Position: Short SNDK (VS)
Small business bankruptcy filings are spiking, more cracks are forming in the housing market … and eventually something’s gotta give.
Plus, June inflation data and Taiwan Semi’s outlook for H2 2026.
* Risks now dwarfs rewards…
Stated simply, my ursine market view continues to be influenced by:
• The lack of fiscal discipline in Washington, D.C., which has resulted in ever increasing annual deficits and a burgeoning national debt load.
• Improvisational fiscal and foreign policy could lead to adverse economic and market outcomes.
• The domestic economy and 2026-07 S&P earnings growth are heavily reliant on AI capital spending.
• We are skeptical whether the AI spend will translate into adequate returns on capital.
• Persistently high inflation.
• The likelihood that interest rates will be higher for longer.
• In today’s uneven K-shaped economy, many consumers are spent up and not pent up.
• An equity risk premium which has now morphed into an equity risk discount.
• Extended valuations in the 95%-tile (Cape Shiller Ratio, Buffett Indicator and other traditional metrics).
• We are in a Bull Market in Complacency with institutional cash allocations near record lows and the buy the dip mentality (too) firmly entrenched.
• Market structure risks are expanding materially. With the popularity of leveraged ETFs and ODTE options (zero days till expiration on indexes and, now even on INDIVIDUAL stocks) the markets have become gamified. Investor timeframes have been reduced as they behave more as gamblers in a casino than long term investors.
Positions: None.
Advanced Micro Devices is turning heads on Wall Street with earnings on the horizon.