Deckers Down, Nokia Up: Upside, Downside Movers in the Morning

Upside

– $CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)

– $NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)

– $LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)

– $BAH +1.9% (Q2 profit beat offset a slight revenue miss)

– $TECK +1.7% (copper-linked stocks rise as copper prices advance)

Downside

– $FLG -8.3% (Q3 profit and revenue missed expectations)

– $DECK -8.2% (quarterly sales missed and the FY sales outlook was cut, while the higher EPS guide relied partly on tariff refunds)

– $INFY -8.2% (FY revenue-growth guidance was cut to 1%-2% despite strong large-deal wins)

– $ALV -5.2% (Q3 profit and sales missed as cost headwinds weighed on results)

– $CRDO -4.6% (AI-infrastructure hardware weakness continues amid concerns over the pace and returns of sector spending)

– $TMUS -4.5%, T -4.4%, VZ -3.9% (wireless carriers fall after a report that SpaceX is pursuing a nationwide cellular-infrastructure program)

– $BE -3.9% (record results and raised guidance were not enough after a major AI-power rally)

– $MRNA -3.7% (extends losses following leaked cancer-vaccine data that disappointed investors)

– $FIX -3.1% (earnings beat, but the CFO retirement and elevated expectations drive a sell-the-news reaction)

– $ACN -2.7%, $CTSH -2.0% (IT-services names fall after Infosys cut its FY growth outlook)

– $WDC -1.9%, STX -1.4% (storage names retreat despite WDC’s beat-and-raise report as elevated expectations trigger profit-taking)

A Look at Thursday

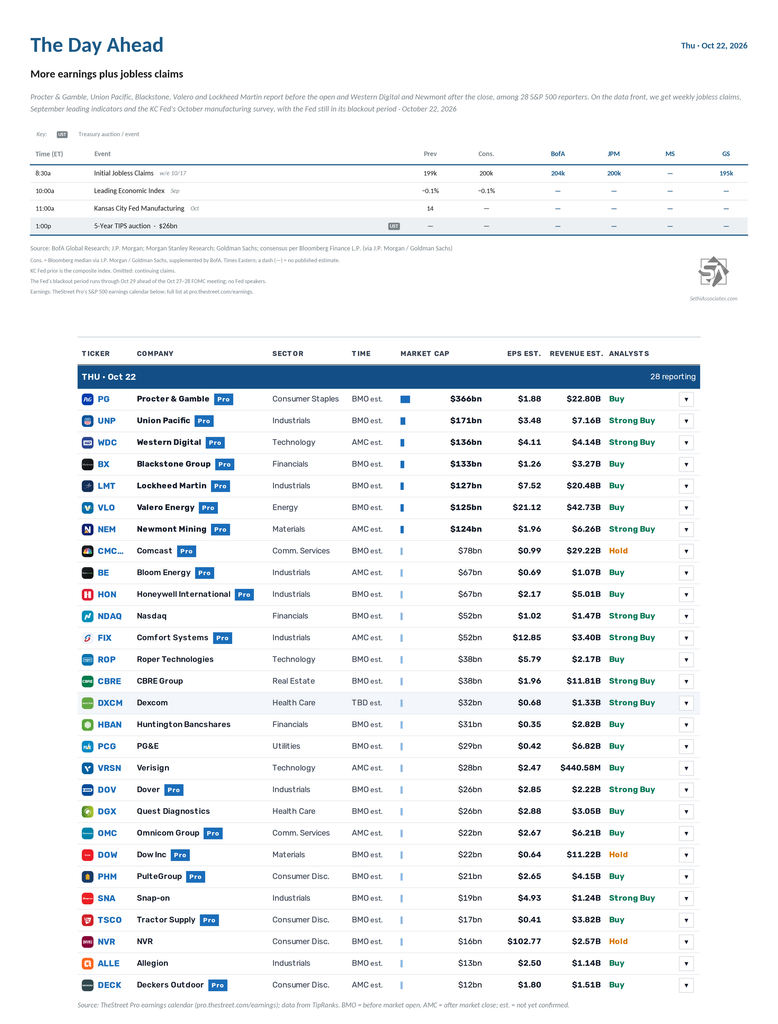
US economic data remains light with weekly jobless claims, September leading and coincident indicators and the Kansas City Fed’s October manufacturing survey.

The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.

Non-Bill (>1yr in maturity) US Treasury auctions continue with a $26bn 5-year TIPS auction.

Q3 earnings season continues with 27 S&P 500 components: Procter & Gamble ($PG), Union Pacific ($UNP), Western Digital ($WDC), Blackstone ($BX), Valero Energy ($VLO), Lockheed Martin ($LMT), Newmont ($NEM), Comcast ($CMCSA), Norfolk Southern ($NSC), Bloom Energy ($BE), Honeywell ($HON), Nasdaq ($NDAQ), Comfort Systems USA ($FIX), CBRE Group ($CBRE), PG&E ($PCG), Roper Technologies ($ROP), Huntington Bancshares ($HBAN), VeriSign ($VRSN), Quest Diagnostics ($DGX), Dover ($DOV), PulteGroup ($PHM), Dow ($DOW), Snap-on ($SNA), Tractor Supply ($TSCO), NVR ($NVR), Allegion ($ALLE) and Deckers Outdoor ($DECK).

Ex-US highlights are France October business confidence, EU27 September new car registrations, Eurozone October consumer confidence, Canada September industrial product price index, and a policy decision in South Korea.

Netflix Down, SpaceX Up: Upside/Downside Movers in the A.M.

Upside

– $SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)

– $SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)

– $CRDO +7.2%, $VRT +6.7%, $DELL +6.9%, $LITE +5.6%, $HPE +5.0%, $COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)

– $WDC +4.0%, $SKHY +3.7%, $SNDK +3.7%, $STX +3.6%, $MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)

– $APLD +4.0% (Texas AI data-center agreement and bullish analyst action)

– $INTC +2.3%, AMD +2.1%, $NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)

– $TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)

Downside

– $TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)

– $NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)

– $ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)

– $T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)

– $DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)

– $TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)

– $ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)

Tech Bounces Back but Rising Yields Pressure Non-Tech

The megacap growth sectors went from worst (Friday) to first (Monday) as chipmakers snapped an eight-session losing streak, but rising Treasury yields left seven sectors, the Dow Jones Industrial Average, and the equal-weight S&P 500 lower.

Tech Selloff Deepens as Market Rotation Continues

Another selloff in AI names broadened to encompass most of Tech, sending the Nasdaq-100 to its worst week since April 2025. Five sectors though would finish the week up 2% or more, as 30-year Treasury yields fell the most since April 2025.