Tracking Over 45 Portfolio Signals That Speak to Our Investment Strategies

Let’s scan through the headlines for the stories of the week that speak to our Pro Portfolio holdings.
Let’s scan through the headlines for the stories of the week that speak to our Pro Portfolio holdings.
This time, investors didn’t rotate, they ran for the safety of cash.
– $SEZL +30% (Q3 revenue and transaction volume surged, FY guidance was raised for the fourth time and preliminary 2027 EPS guidance was introduced)
– $ARQ +26% (record Q3 revenue, sharp margin expansion and the low end of FY EBITDA guidance was raised)
– $APP +22% (Q3 profit beat and revenue came in $100 million above the top of the company’s forecast)
– $RUN +21% (Q3 beat as direct installations returned to growth and storage attachment reached a record)
– $WRBY +21% (raised the low end of FY sales guidance and confirmed November 12 preorders for its first Intelligent Eyewear collection)
– $ADMA +20% (ASCENIV sales rose 31%, gross margin expanded sharply and the adjusted earnings outlook was raised)
– $U +20% (strongest quarter on record, with Vector revenue up 126% and the first GAAP profit since its IPO)
– $TPR +14% (Q1 beat with strong Coach growth and FY revenue, margin and EPS guidance raised)
– $EPAM +12% (Q3 beat alongside a $1.5 billion buyback expansion and planned $500 million accelerated repurchase)
– $TM +8.8% (first-half profit strengthened and the full-year operating-income and net-income forecasts were raised)
– $SONY +6.0% (Q2 profit surged on gaming and film strength, prompting higher full-year sales, profit and dividend forecasts)
– $BABA +5.3%, $TCOM +4.3%, $NTES +3.9%, $PDD +3.7%, $JD +4.2% (China ADRs rise with an overnight rebound in Hong Kong technology shares)
– $GFI +4.4% (gold producer gains as bullion prices rally)
– $CELH +2.7% (record Q3 revenue rose 17% as the expanded beverage portfolio sustained growth)
– $UBER +2.4% (Amazon Prime members can now order Uber Eats with free delivery on qualifying purchases)
– $MNTN -46% (slashed FY revenue and EBITDA guidance after sales-team execution problems and named a new CEO)
– $BZFD -34% (Q3 revenue plunged 44%, adjusted EBITDA turned negative and the FY outlook was deferred)
– $VCYT -32% (lowered near-term Decipher Prostate expectations, narrowed FY guidance below consensus and forecast only mid-single-digit 2027 revenue growth)
– $ANVS -29% (proposed a dilutive stock-and-warrant offering while disclosing limited cash, going-concern risk and expanded authorized shares)
– $AKBA -25% (Q3 revenue fell sharply as Auryxia sales were hit by generic competition and pricing pressure)
– $HIMX -25% (guided Q4 revenue down 22% to 26% sequentially on abrupt automotive-display order corrections)
– $GIL -23% (Q3 missed expectations, FY sales and EPS guidance was cut sharply and 2026–2028 objectives were withdrawn)
– $WMS -13% (organic stormwater sales declined, demand softened and the FY revenue outlook was reduced)
– $QCOM -11% (smartphone-chip sales missed expectations on sluggish demand and declining Apple-related revenue)
– $FICO -10% (withheld FY27 guidance amid mortgage-pricing uncertainty and was downgraded by RBC despite a quarterly beat)
– $SNAP -10% (Q3 revenue missed expectations)
– $MELI -9.2% (earnings missed and logistics investment compressed operating margin despite strong revenue growth)
– $AMCR -8.1% (profit missed and the six-month EPS outlook was cut as energy and distribution costs outpaced pricing recovery)
– $ASX -7.6%, $SNDK -5.8%, $SKHY -6.2%, $STX -4.5% (Asian and memory-chip names extend the semiconductor selloff as election results intensify concerns over slower data-center construction)
– $ARM -7.4% (quarter beat, but current-quarter guidance failed to clear elevated expectations and shares joined the broader chip selloff)
– $HUBS -6.5% (Q3 beat, but Q4 profit guidance came in below expectations)
– $BDX -5.4% (Q4 beat, but low-single-digit FY27 revenue growth and modest EPS growth guidance disappointed)
Qualcomm’s handset slump, oil questions, and other headlines moving the market this morning.
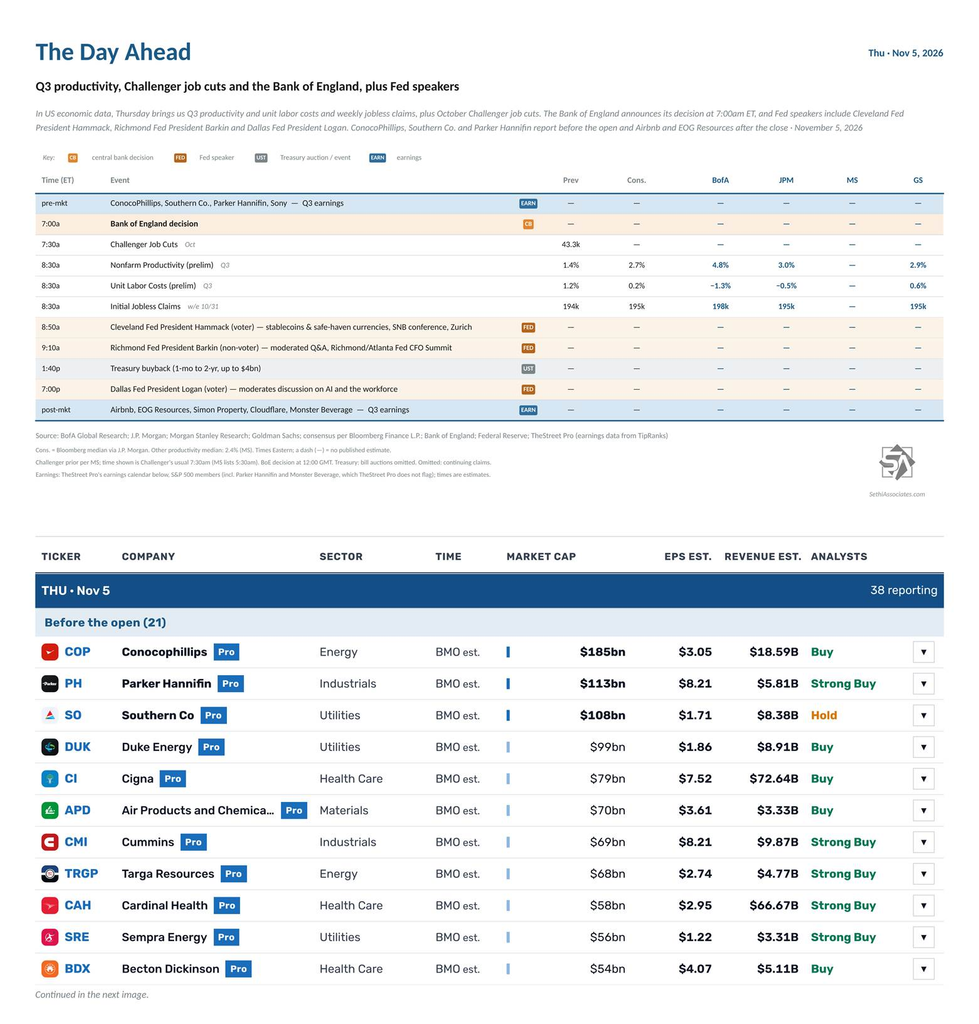
In U.S. economic data, Thursday brings us Q3 productivity and unit labor costs, plus October Challenger job cuts/hires. We’ll also get the weekly unemployment claims.
Cleveland Fed President Hammack (voter) speaks on stablecoins and safe-haven currencies in Zurich at 8:50am ET, Richmond Fed President Barkin (non-voter) participates in a moderated Q&A at 9:10am ET, and Dallas Fed President Logan (voter) moderates a discussion on AI and the workforce at 7pm ET.
The Bank of England announces its decision at 7am ET.
There are no non-Bill (>1yr in maturity) U.S. Treasury auctions, but Treasury holds a buyback of up to $4 billion of 1-month to 2-year securities at 1:40pm ET.
Also, a White House committee is scheduled to hold a closed hearing on allegations against Fed Governor Lisa Cook and whether there’s cause for her removal, per Bloomberg (via @C_Barraud).
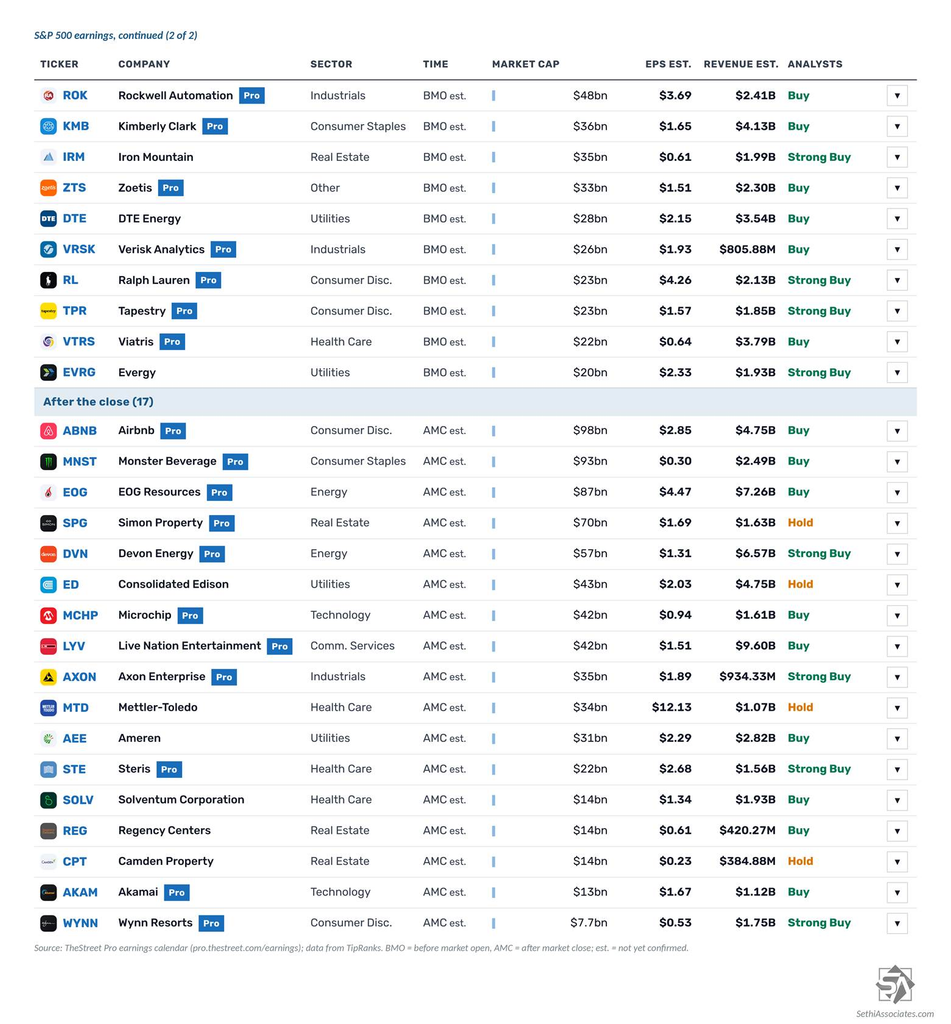
38 S&P 500 components report, three of them with market caps over $100bn:
Before the open: ConocoPhillips ($COP), Parker Hannifin ($PH), Southern Co. ($SO), Duke Energy ($DUK), Cigna ($CI), Air Products ($APD), Cummins ($CMI), Targa Resources ($TRGP), Cardinal Health ($CAH), Sempra ($SRE), Becton Dickinson ($BDX), Rockwell Automation ($ROK), Kimberly-Clark ($KMB), Iron Mountain ($IRM), Zoetis ($ZTS), DTE Energy ($DTE), Verisk Analytics ($VRSK), Ralph Lauren ($RL), Tapestry ($TPR), Viatris ($VTRS) and Evergy ($EVRG)
After the close: Airbnb ($ABNB), Monster Beverage ($MNST), EOG Resources ($EOG), Simon Property ($SPG), Devon Energy ($DVN), Consolidated Edison ($ED), Microchip Technology ($MCHP), Live Nation ($LYV), Axon ($AXON), Mettler-Toledo ($MTD), Ameren ($AEE), Steris ($STE), Solventum ($SOLV), Regency Centers ($REG), Camden Property ($CPT), Akamai ($AKAM) and Wynn Resorts ($WYNN)
Outside the S&P 500, Sony ($SONY), National Grid ($NGG) and ArcelorMittal ($MT) report before the open, Cloudflare ($NET) after the close, and Toyota ($TM) at a time not yet announced.
Ex-U.S. highlights include U.K. October new car registrations and construction PMI, Japan September labor cash earnings, Germany September factory orders and October construction PMI, France September industrial production, Italy September retail sales, Eurozone September PPI and Sweden October CPI.
Besides the BoE, Norges Bank, Malaysia and Mexico announce rate decisions, ECB President Lagarde speaks, the ECB opens its annual money markets conference, Canada releases its 2026 federal budget and the China International Import Expo begins in Shanghai.
A Democratic sweep of Congress supercharged the rotation trade, with hyperscalers joining a rally that lifted almost everything except semiconductors and AI power and data center names.
Bad news hit these three names and there is more downside to come.
Cisco and Cerebras shares fall, Lenovo’s server demand soars and other headlines moving the market today.