A Pair of Tax Loss Rally Candidates to Consider

Of course, we’re looking at sentiment and the overall market today, but we’ve got trading ideas, too, including two stocks that could bounce once investors take their losses to help out with taxes.
Of course, we’re looking at sentiment and the overall market today, but we’ve got trading ideas, too, including two stocks that could bounce once investors take their losses to help out with taxes.
Brent topped $116 and stocks pulled back on fears of renewed U.S.-Iran hostilities after the midterm elections. For the week, small caps led with the Russell 2000 up 2% while the S&P 500 and Nasdaq slipped.
Elon Musk’s latest move could signal the future of telecom. Here’s how I’m trading the initial reaction.
Amex delivers, OpenAI’s capital raise and a potential one for Meta. Plus other headlines moving the market this morning.
Thursday’s selloff isn’t a signal to cut exposure. It is a signal to look where the money is going.
Blowout SpaceX results lifted a swath of AI names, sending the Nasdaq up over 1%.
– $SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)
– $SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)
– $CRDO +7.2%, $VRT +6.7%, $DELL +6.9%, $LITE +5.6%, $HPE +5.0%, $COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)
– $WDC +4.0%, $SKHY +3.7%, $SNDK +3.7%, $STX +3.6%, $MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)
– $APLD +4.0% (Texas AI data-center agreement and bullish analyst action)
– $INTC +2.3%, AMD +2.1%, $NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)
– $TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)
– $TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)
– $NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)
– $ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)
– $T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)
– $DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)
– $TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)
– $ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)
Super Micro Computer crushes expectations while United Airlines and Alaska Airlines confirm energy input concerns. Those and other headlines are moving the market this morning.
Let’s look at sticky oil prices, even after the flow largely returns from the Middle East. Also, could Tesla merge with SpaceX?
From my evening update:
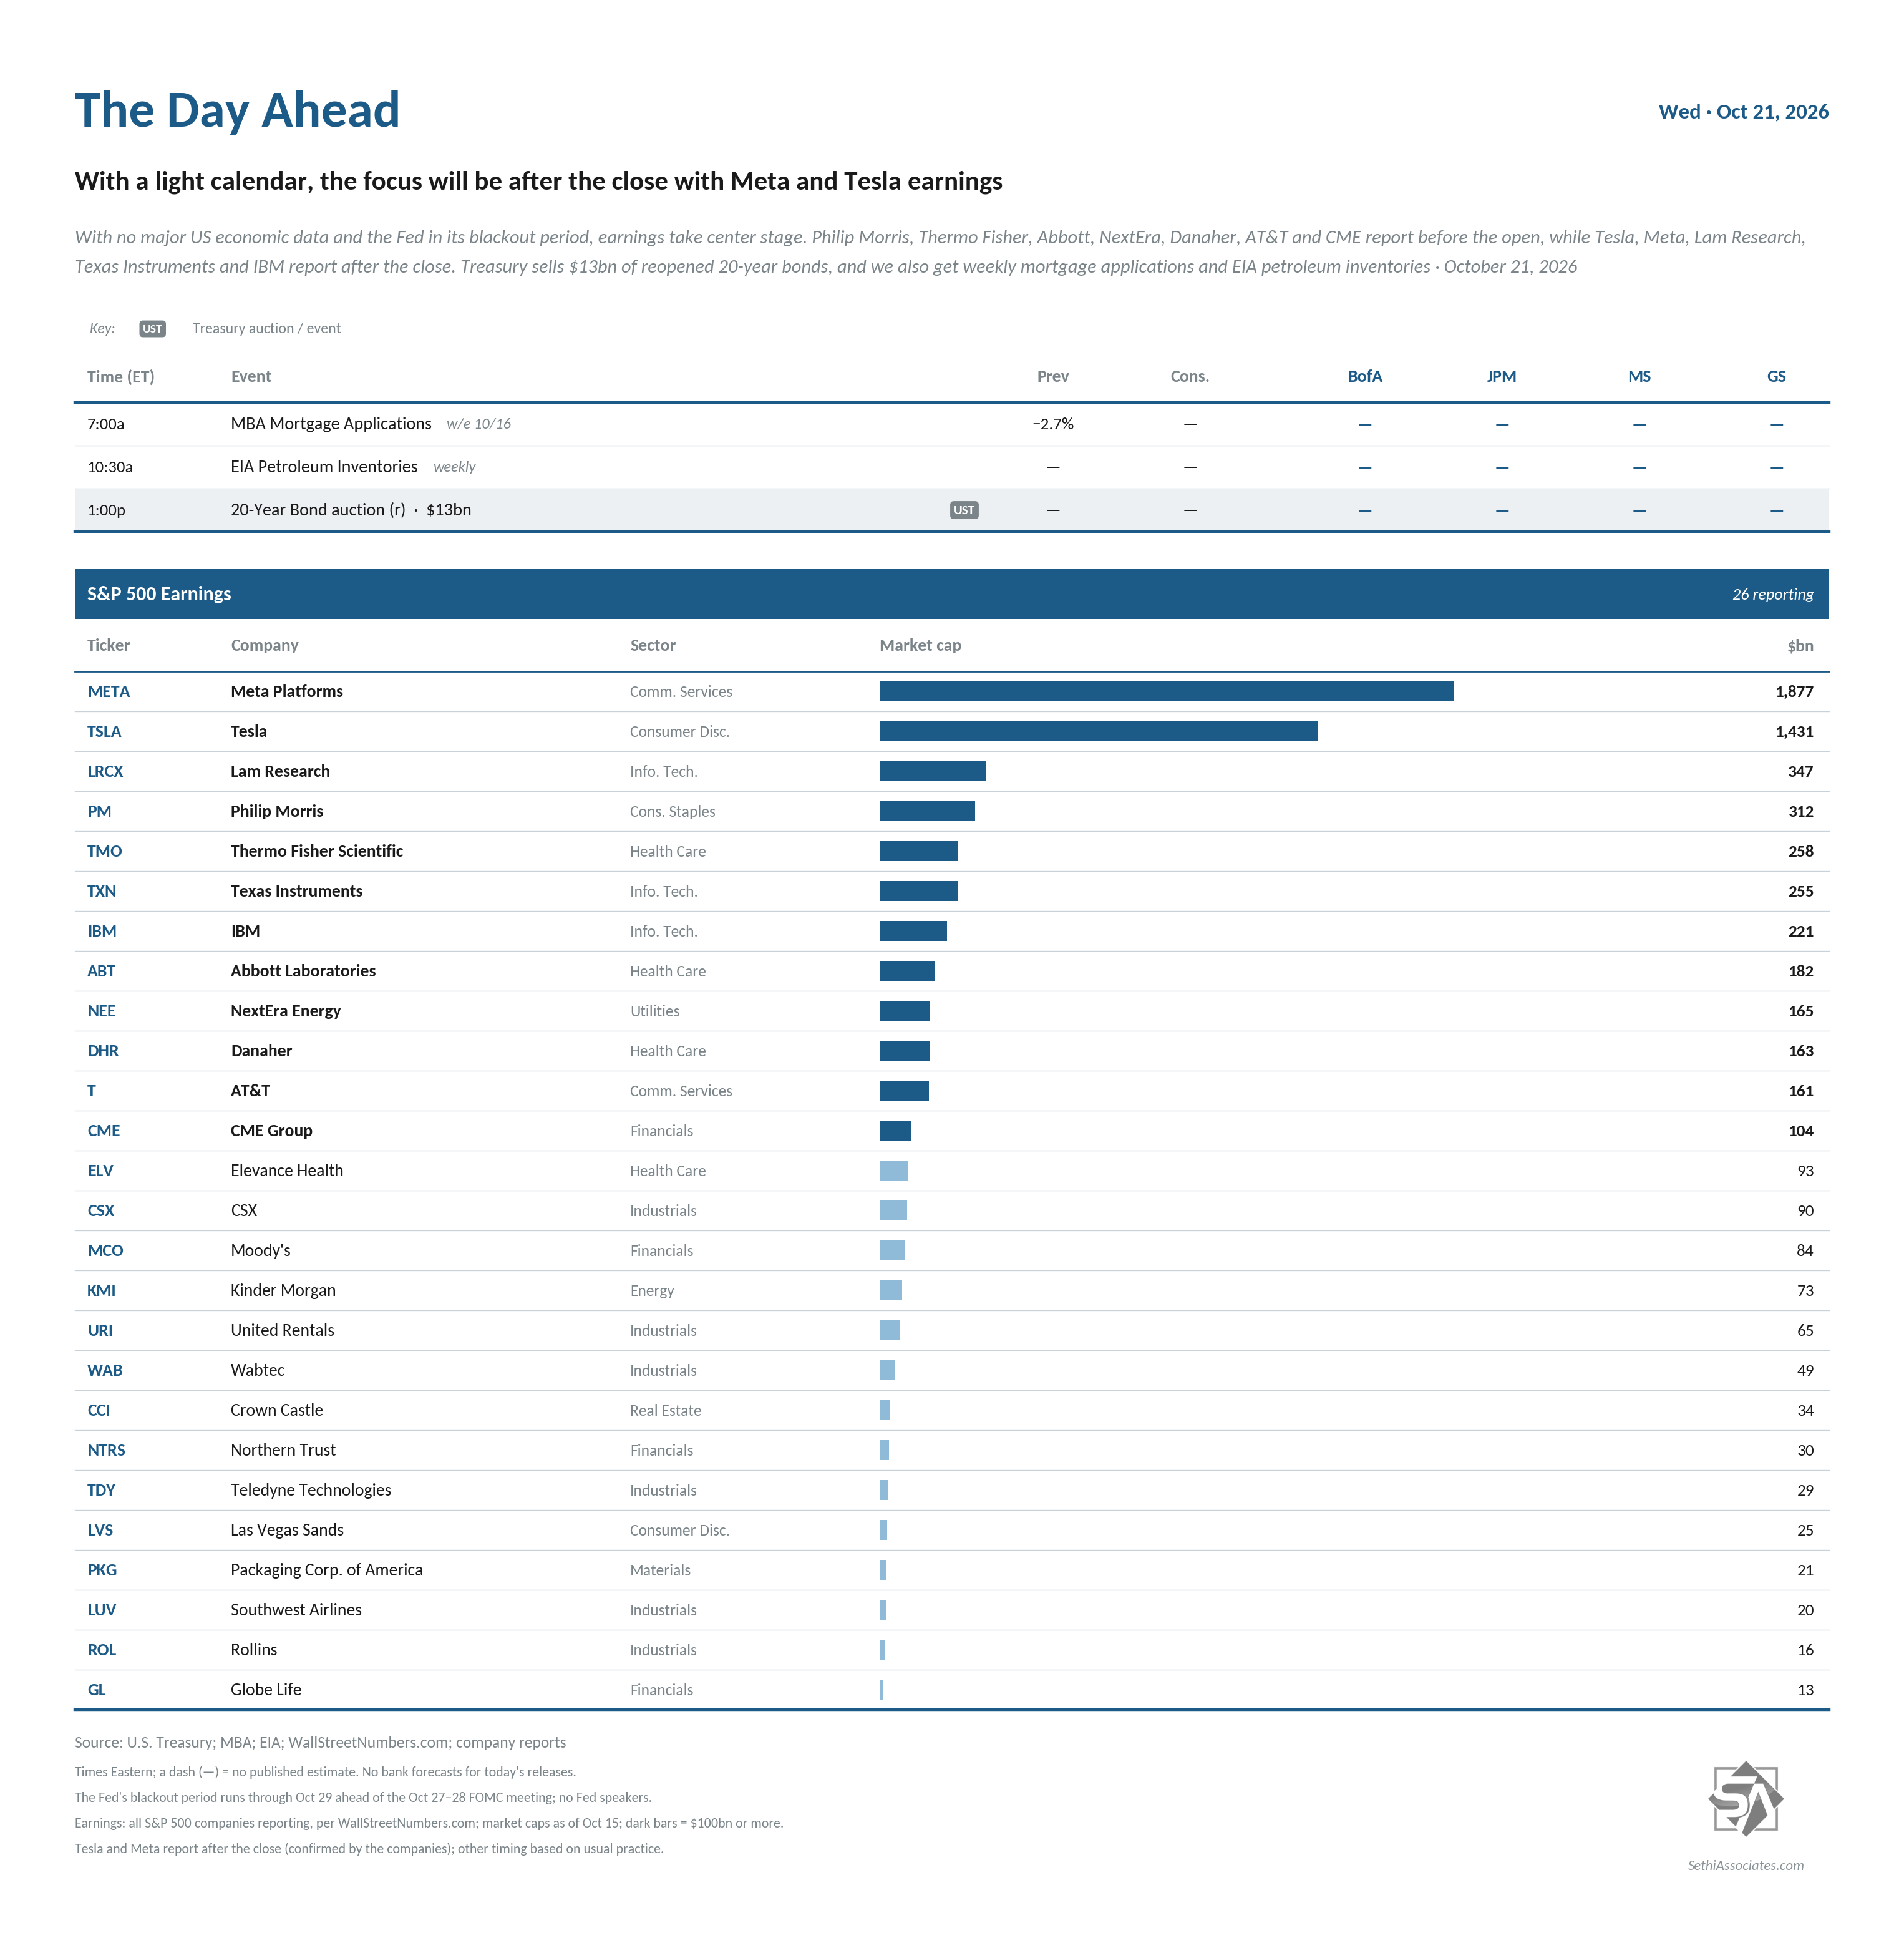
US economic data is light Wednesday, with only weekly mortgage applications and EIA petroleum inventories.
The Fed remains in its blackout period ahead of next week’s October 27–28 FOMC meeting.
Non-Bill (>1yr in maturity) US Treasury auctions resume with a $13B 20-year bond reopening.
Q3 earnings season continues with 26 S&P 500 components including a number of AI-related names: Meta Platforms ($META), Tesla ($TSLA), Lam Research ($LRCX), Philip Morris ($PM), Thermo Fisher Scientific ($TMO), Texas Instruments ($TXN), IBM ($IBM), Abbott Laboratories ($ABT), NextEra Energy ($NEE), Danaher ($DHR), AT&T ($T), CME Group ($CME), Elevance Health ($ELV), CSX ($CSX), Moody’s ($MCO), Kinder Morgan ($KMI), United Rentals ($URI), Wabtec ($WAB), Crown Castle ($CCI), Northern Trust ($NTRS), Teledyne Technologies ($TDY), Las Vegas Sands ($LVS), Packaging Corp. of America ($PKG), Southwest Airlines ($LUV), Rollins ($ROL) and Globe Life ($GL).
Ex-US highlights are UK September CPI, PPI, RPI, public finances, August house price index, Japan September trade balance, New Zealand Q3 CPI.