Upside, Downside Movers in the Morning

Upside

– $ULBI +145% (agrees to be acquired for $16.00 a share in cash)

– $BOOM +21% (Q3 sales and adjusted EBITDA exceeded the high end of guidance as backlog and cash flow strengthened)

– $AXGN +16% (Q3 beat and full-year revenue guidance was raised)

– $VRT +16% (Q3 organic orders more than doubled and full-year sales guidance was raised by $650 million)

– $UCTT +15% (Q3 results and outlook drove a sharp upside reaction)

– $LUNG +12% (Q3 results and outlook drove a sharp upside reaction)

– $GEHC +9.7% (Q3 beat, full-year EPS and free-cash-flow guidance was raised, and a $945 million acquisition was announced)

– $FLEX +9.5% (fiscal Q2 beat and the full-year outlook was raised)

– $LCII +7.6% (confirms an unsolicited $101-a-share cash acquisition proposal)

– $SKHY +7.5% (quarterly revenue exceeded 100 trillion won for the first time)

– $STLA +6.9% (Q3 net loss narrowed about 90% and the 2026 outlook was reaffirmed)

– $ETSY +6.6% (announces a leadership transition)

– $SNDK +4.2%, MU +3.6% (memory names rise after SKHY posted record quarterly revenue)

– $GEV +2.4% (Q3 orders surged 96%, backlog reached $197 billion, cash-flow guidance was raised and the buyback authorization doubled)

Downside

– $RAPP -23% ($350 million of stock and convertible-note offerings priced alongside a $30 million private placement)

– $ENPH -19% (Q3 revenue missed and the Q4 sales guide was roughly 20% below consensus amid weak US residential-solar demand)

– $INTA -17% (quarter beat, but the fiscal-year outlook failed to clear elevated expectations)

– $EDU -13% (fiscal Q1 results disappointed investors)

– $BSX -12% (Q3 EPS missed and Q4 and full-year profit guidance came in below consensus)

– $LOGI -12% (holiday-quarter sales guidance called for a decline and included a $70 million–$80 million supplier-incident hit)

– $SEDG -8.7% (solar-equipment sympathy decline following ENPH’s weak demand commentary and Q4 guide)

– $NXPI -8.1% (Q3 beat, but the Q4 guide was only roughly in line and fell short of elevated expectations)

– $FFIV -7.6% (Q4 beat, but fiscal 2027 growth guidance disappointed and operating margins contracted)

– $HOOD -6.4% (revenue missed as crypto revenue fell 55%, outweighing an EPS beat and record total revenue)

– $GSK -5.8% (headline Q3 beat was offset by weak vaccine sales, soft new-product performance and unchanged guidance)

– $LII -4.7% (Q3 profit fell, segment margin contracted 240 basis points and the full-year EPS outlook disappointed)

– $STX -2.5% (fiscal Q1 results prompted a modest sell-the-news reaction)

– $V -1.7% (fiscal Q4 earnings and revenue missed forecasts despite healthy payment-volume growth and a 16% dividend increase)

Tuesday’s Busy Calendar

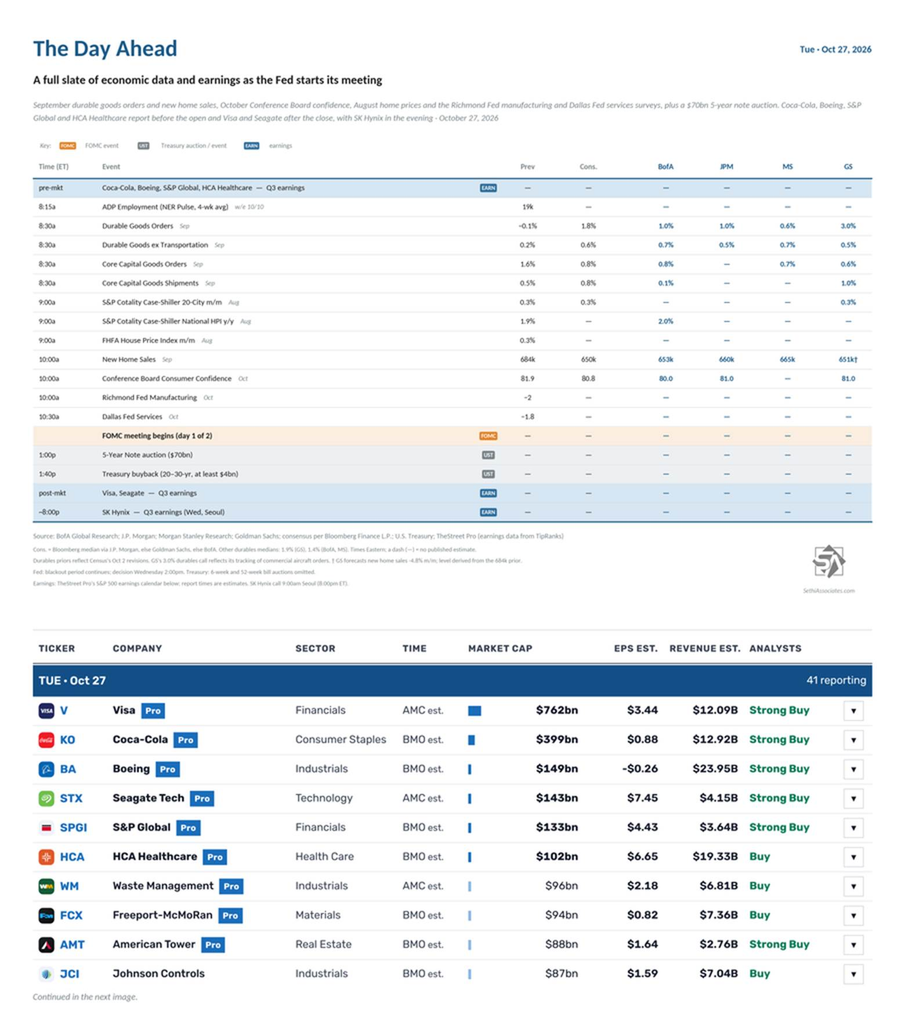
It’s a full slate of economic data and earnings as the Fed starts its two-day meeting.

September US economic reports include durable goods orders and new home sales. October reports include Conference Board consumer confidence and the Richmond Fed manufacturing and Dallas Fed services surveys. For August, we get the S&P Cotality Case-Shiller and FHFA home price indexes. We’ll also get the weekly ADP NER Pulse.

The FOMC begins its two-day meeting, with the decision Wednesday at 2pm ET.

Non-Bill (>1yr in maturity) US Treasury auctions are $70B of 5-year notes. Treasury will also conduct a buyback of 20- to 30-year securities.

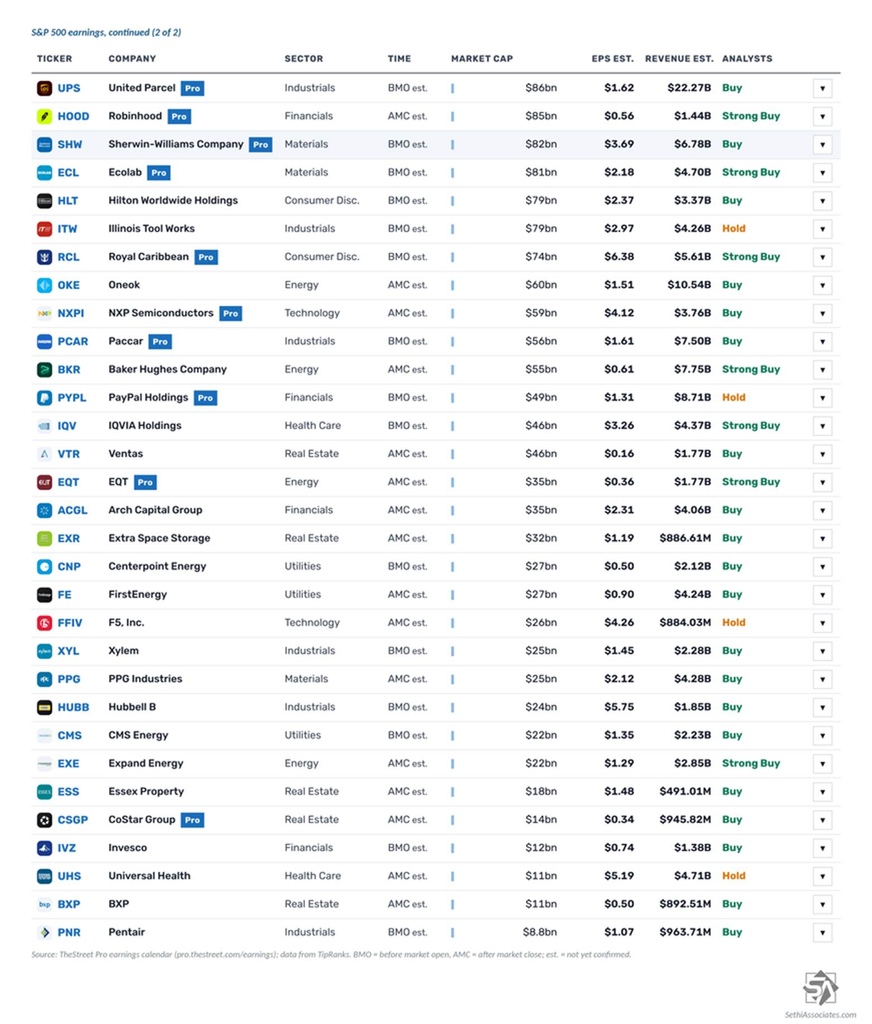
41 S&P 500 components report, six of them with market caps over $100bn:

  • Before the open: Coca-Cola ($KO), Boeing ($BA), S&P Global ($SPGI), HCA Healthcare ($HCA), Freeport-McMoRan ($FCX), American Tower ($AMT), Johnson Controls ($JCI), UPS ($UPS), Sherwin-Williams ($SHW), Ecolab ($ECL), Hilton ($HLT), Illinois Tool Works ($ITW), Royal Caribbean ($RCL), Paccar ($PCAR), PayPal ($PYPL), IQVIA ($IQV), CenterPoint Energy ($CNP), Xylem ($XYL), Hubbell ($HUBB), CMS Energy ($CMS), Invesco ($IVZ) and Pentair ($PNR)
  • After the close: Visa ($V), Seagate Technology ($STX), Waste Management ($WM), Robinhood ($HOOD), Oneok ($OKE), NXP Semiconductors ($NXPI), Baker Hughes ($BKR), Ventas ($VTR), EQT ($EQT), Arch Capital ($ACGL), Extra Space Storage ($EXR), FirstEnergy ($FE), F5 ($FFIV), PPG Industries ($PPG), Expand Energy ($EXE), Essex Property Trust ($ESS), CoStar Group ($CSGP), Universal Health Services ($UHS) and BXP ($BXP)

Outside the US, Novartis ($NVS) and Porsche ($DRPRY) have reported, followed by SK Hynix ($SKHY) tonight.

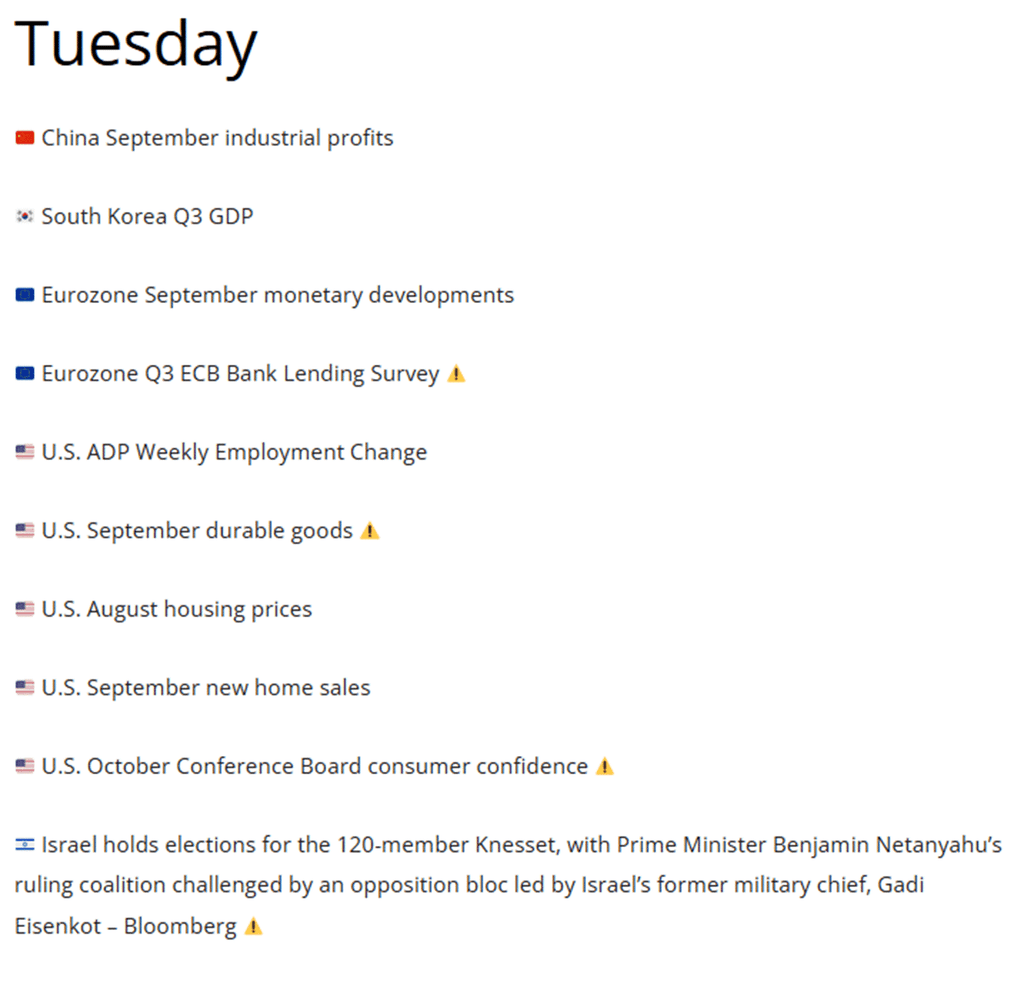
Ex-US highlights include China September industrial profits, South Korea Q3 GDP, France October consumer confidence, Eurozone September M3 and the ECB’s Q3 Bank Lending Survey. Israel also holds parliamentary elections.

From Christophe Barraud’s international Week Ahead rundown:

Netflix Down, SpaceX Up: Upside/Downside Movers in the A.M.

Upside

– $SMCI +12% (preliminary fiscal Q1 revenue outlook was raised well above expectations, with gross-margin upside)

– $SPCX +8.2% (Q3 revenue and profit crushed expectations, marking its first quarterly profit since the IPO, while special committees evaluate a potential TSLA merger)

– $CRDO +7.2%, $VRT +6.7%, $DELL +6.9%, $LITE +5.6%, $HPE +5.0%, $COHR +4.6% (AI-infrastructure suppliers rise as the SMCI outlook and SPCX AI-compute results reinforce data-center demand)

– $WDC +4.0%, $SKHY +3.7%, $SNDK +3.7%, $STX +3.6%, $MU +3.1% (memory and storage names gain on the stronger AI-infrastructure demand read-through)

– $APLD +4.0% (Texas AI data-center agreement and bullish analyst action)

– $INTC +2.3%, AMD +2.1%, $NVDA +2.0% (chip stocks rise as strong AI-compute and server demand updates lift the broader complex)

– $TSLA +1.4% (special committee formed with SPCX to evaluate a potential merger ahead of earnings)

Downside

– $TKNO -30% ($40M primary offering priced at $5 per share, a steep discount to the prior close)

– $NFLX -7.0% (Q3 profit beat, but the Q4 sales outlook missed and the 2026 advertising-revenue forecast was cut to $2.7B from $3B)

– $ISRG -6.7% (Q3 beat, but U.S. procedure growth slowed, instrument pricing reductions were outlined and the high end of the procedure-growth outlook was cut)

– $T -5.6% (Q3 beat and FY EPS guidance was raised, but postpaid phone additions missed expectations amid satellite-competition concerns)

– $DHR -3.6% (Q3 beat and FY EPS guidance was raised, but the Q4 core-growth outlook remained modest with a respiratory-revenue headwind)

– $TMO -3.0% (sell-the-news reaction after a Q3 beat and raised FY guidance)

– $ACN -1.5% (Baird downgrades to Neutral from Outperform on valuation and slower organic growth)

Upside, Downside Movers in the Morning

Upside

– $VFC +4.0% (Piper Sandler and Truist upgrade as signs of Vans stabilization improve turnaround confidence)

– $GS +3.0% (Q3 beat, led by surging equities revenue and stronger investment-banking fees)

– $UNH +2.5% (Q3 beat and 2026 adjusted EPS outlook raised to at least $20.50)

Downside

– $SNDX -17.0% (MAXPIRe Phase 2 axatilimab trial in idiopathic pulmonary fibrosis missed its primary endpoint)

– $S -7.0% ($1.25B convertible senior-notes offering raises dilution and stock-supply concerns)

– $WDC -6.0% (UBS cuts its target on hard-drive capacity and pricing uncertainty, compounding the storage-sector selloff)

– $SNDK -6.0%, $STX -5.5%, $MU -3.5%, $MRVL -2.5%, $AMD -2.0% (memory, storage and chip names slide as reported CXMT advances intensify China-competition fears)

– $JPM -3.5% (Q3 EPS and revenue missed as fixed-income trading weakened despite stronger investment-banking fees)

– $DPZ -3.0% (Q3 beat, but US same-store sales growth slowed sharply, raising demand-recovery concerns)

– $JNJ -3.0% (Q3 beat, but medtech growth was soft and international device sales faced geopolitical disruption)

– $ADBE -1.5% (HSBC downgrades to Hold, citing open-source competition risks)

– $WFC -1.0% (Q3 EPS beat, but revenue and net-interest income missed expectations)