NOW Down, EBAY Up: Upside, Downside Movers in the Morning

Upside

– $GKOS +16% (record Q3 sales and a large FY revenue-guidance raise topped expectations)

– $INSM +14% (BRINSUPRI revenue grew 29% sequentially and guidance was raised for both BRINSUPRI and ARIKAYCE)

– $NCLH +12% (Q3 results topped guidance and the FY EBITDA and EPS outlooks were raised)

– $CVNA +8.4% (large Q3 revenue beat and accelerating retail-unit growth outweighed an EPS miss)

– $CMG +8.3% (Q3 comparable sales beat expectations despite a modest profit miss)

– $DASH +6.9% (record GOV, revenue and net income alongside an agreed $17B acquisition of CART)

– $LITE +6.9% (MRVL is reportedly in advanced acquisition talks, with a deal potentially announced next week)

– $EBAY +6.1% (Q3 revenue and GMV growth accelerated, reinforcing improving marketplace momentum)

– $HII +5.6% (record Q3 revenue, $32.4B of contract awards and higher FY shipbuilding-revenue guidance)

– $LLY +5.1% (annual revenue guidance topped expectations)

– $NVS +3.2% (2026 core operating-income guidance was raised despite a drug-trial write-down)

– $RCL +3.5%, CCL +3.0% (cruise names rise after NCLH beat and raised its FY outlook)

– $MSFT +1.1% (strong cash flow and cloud guidance signaled better returns from heavy AI investment)

Downside

– FTNT -27% (headline beat and raised guidance failed to offset sharply slowing product growth and concerns the refresh cycle is fading)

– NOW -19% (strong topline results were overshadowed by softer forward cRPO expectations and unfavorable renewal phasing)

– HLN -14% (Q3 organic sales missed and FY organic-growth guidance was cut to around 2.5%)

– OSK -13% (quarter missed and FY revenue and EPS guidance were cut as fire-truck production problems persisted)

– MRVL -12% (reported talks to acquire LITE sparked concerns over deal cost and execution risk)

– $CAT -11% (quarter beat, but the margin outlook and durability of AI-infrastructure demand fell short of elevated expectations)

– $GOOGL -11% (Q3 profit and revenue missed as softer search advertising and surging AI spending intensified cash-burn concerns)

– $EGO -10% (2026 gold-production guidance was cut and cost outlooks were raised amid a slower Skouries ramp)

– $CTSH -10% (Q3 beat, but the FY revenue-growth outlook narrowed and Q4 growth guidance disappointed)

– $SCI -8.9% (Q3 earnings missed and guidance was cut)

– $ZS -7.1%, $OKTA -7.5%, $PANW -6.8%, $RBRK -6.8%, $CRWD -6.8%, $SAIL -8.0% (cybersecurity names fall on FTNT’s product-growth slowdown and refresh-cycle concerns)

– $NBIS -6.7%, $CRWV -6.4%, $STRL -6.6% (AI-infrastructure names retreat as $GOOGL’s spending surge renews concerns about monetization and cash returns)

– $HUBS -6.5%, $TEAM -6.9%, $CRM -5.8%, $TYL -5.8%, $WDAY -6.1% (enterprise-software names weaken after NOW’s forward cRPO and renewal outlook disappointed)

SoFI Up, HSBC Down: Upside, Downside Movers in the Morning

Upside

– $MFIC +23% (ARCC agrees to acquire it for $10.88 per share in cash and stock, valuing the transaction at about $2.6B)

– $INIO +14% (record Q3 results and FY26 revenue and EBITDA outlooks were raised)

– $CLS +12% (Q3 beat, FY26 outlook raised and initial 2027 guidance called for 90% revenue growth on accelerating AI-infrastructure demand)

– $SOFI +11% (record Q3 revenue and EBITDA, strong member growth and a raised FY26 outlook)

– $FER +9.9% (no clear fresh catalyst identified; unusually large, liquid move ahead of 9M results after the U.S. close)

– $RCL +5.3% (Q3 beat, bookings remained strong and the full-year profit outlook was raised)

– $CRDO +4.3%, $SKHY +3.2%, $COHR +2.7%, $AMKR +3.6%, $LITE +2.6%, $AVGO +2.9% (AI-chip and optical-connectivity names rise as the CLS outlook reinforces accelerating hyperscaler demand)

– $JCI +4.3% (Q4 beat and the FY27 profit outlook topped expectations)

– $SPGI +3.8% (FY26 outlook raised and a strategic review of Capital IQ businesses was launched)

– $NBIS +3.7%, BE +3.3%, CRWV +3.6%, VRT +2.2% (AI-infrastructure names gain after CLS said customer demand forecasts continue strengthening into 2027 and 2028)

– $NCLH +2.2%, CCL +2.7% (cruise peers rise after RCL beat expectations and raised its full-year profit outlook)

– $CDNS +1.8% (Q3 beat, FY outlook raised, backlog reached a record $8.2B and a $2.5B buyback was added)

– UPS +1.8% (Q3 beat and FY26 revenue and profit forecasts were raised as shipment mix and cost reductions improved)

Downside

– $XYL -8.5% (Q3 update disappointed, with investors focusing on softer revenue expectations)

– $WSO -8.3% (Q3 profit missed expectations)

– $HSBC -6.7% (Q3 revenue and pretax profit missed expectations, outweighing a new $1B buyback)

– $HLT -4.4% (Q3 earnings beat, but revenue missed and the raised RevPAR outlook was not enough for elevated expectations)

– $SHW -3.8% (Q3 results and outlook disappointed as housing-linked demand remained soft)

– $ONON -3.3% (no clear fresh catalyst identified; unusually large, high-volume premarket decline)

– $MAR -2.0% (hotel peer slips in sympathy with HLT after its revenue miss)

Tuesday’s Busy Calendar

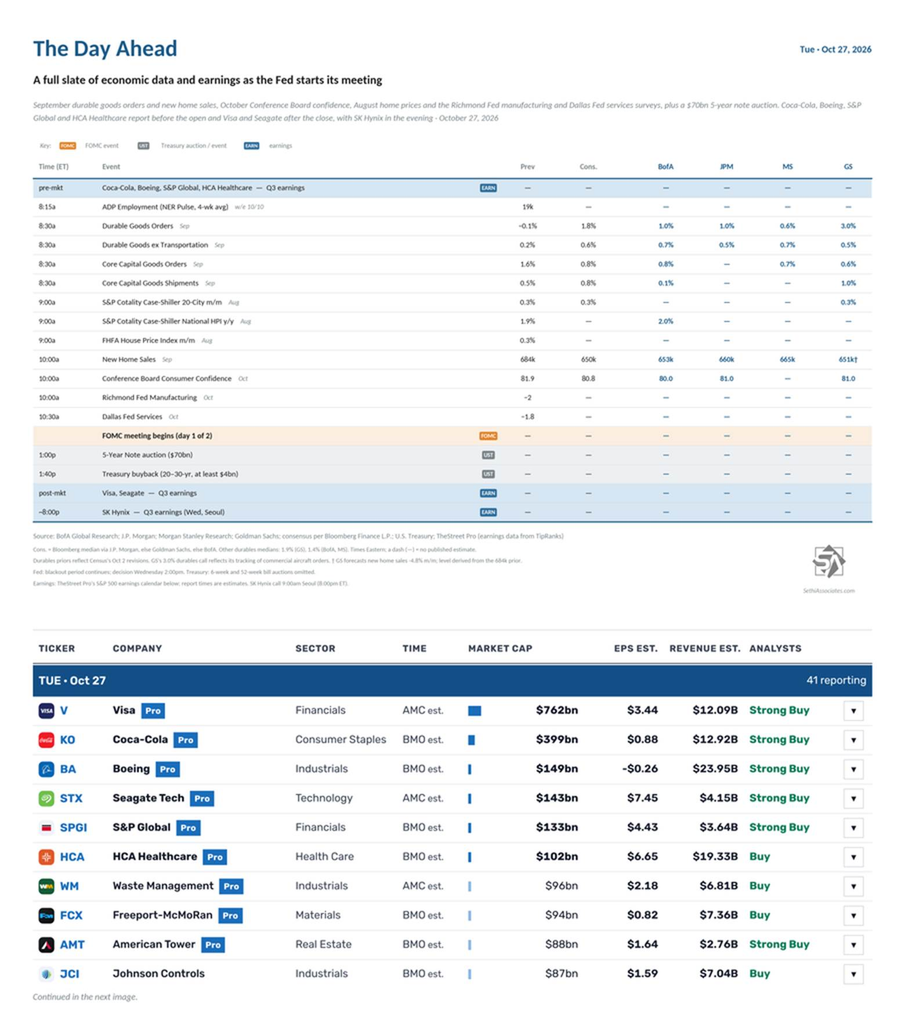
It’s a full slate of economic data and earnings as the Fed starts its two-day meeting.

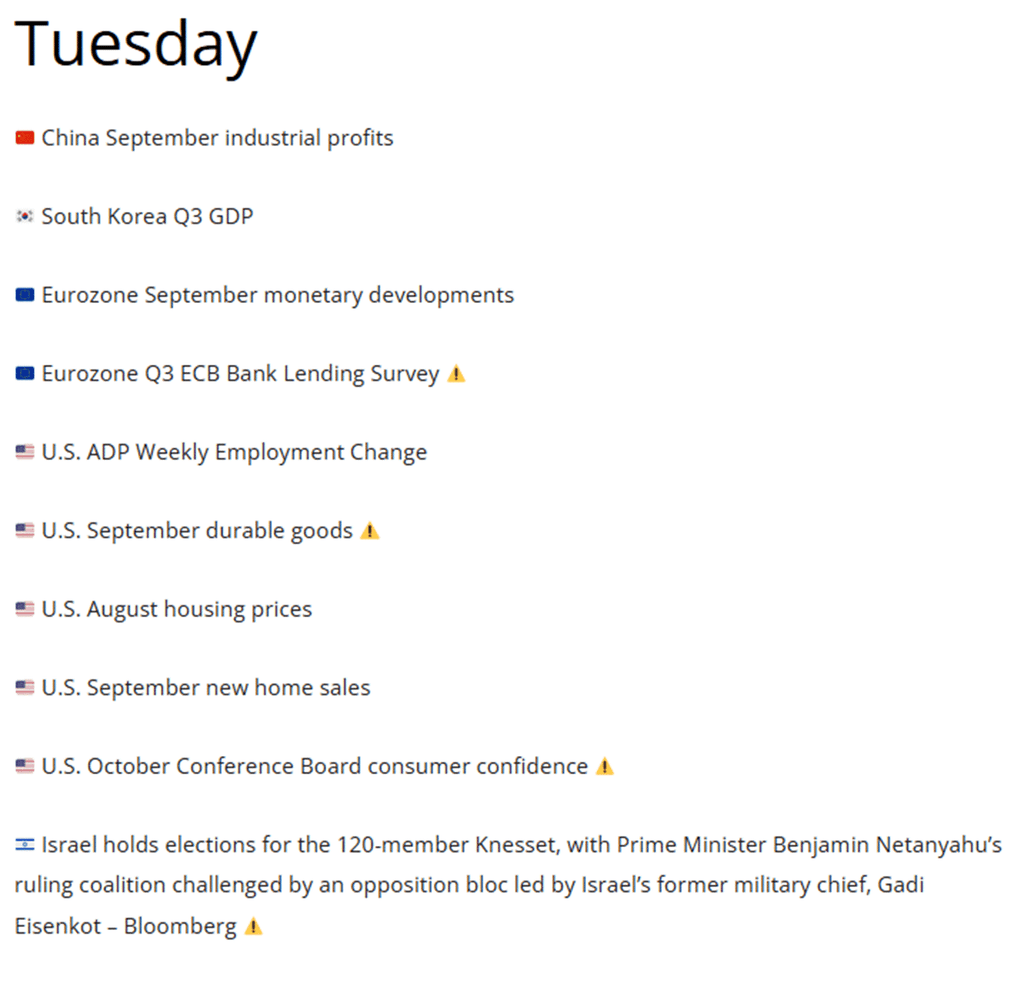
September US economic reports include durable goods orders and new home sales. October reports include Conference Board consumer confidence and the Richmond Fed manufacturing and Dallas Fed services surveys. For August, we get the S&P Cotality Case-Shiller and FHFA home price indexes. We’ll also get the weekly ADP NER Pulse.

The FOMC begins its two-day meeting, with the decision Wednesday at 2pm ET.

Non-Bill (>1yr in maturity) US Treasury auctions are $70B of 5-year notes. Treasury will also conduct a buyback of 20- to 30-year securities.

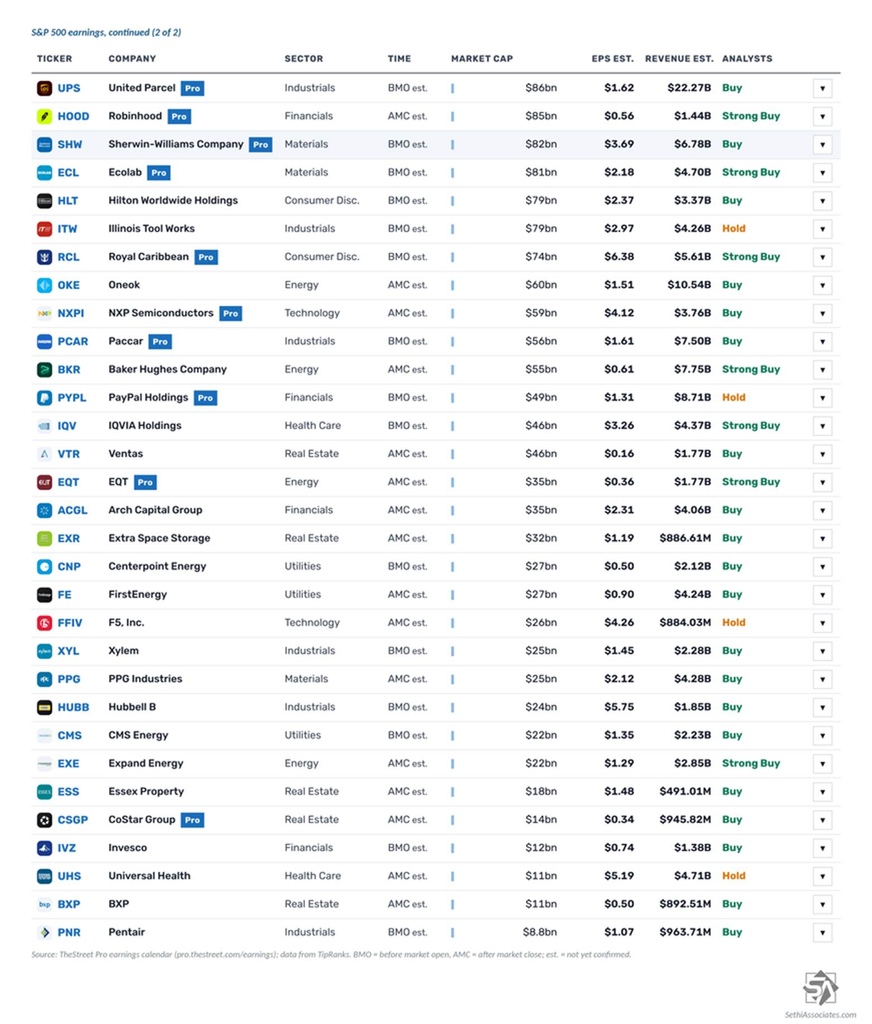
41 S&P 500 components report, six of them with market caps over $100bn:

  • Before the open: Coca-Cola ($KO), Boeing ($BA), S&P Global ($SPGI), HCA Healthcare ($HCA), Freeport-McMoRan ($FCX), American Tower ($AMT), Johnson Controls ($JCI), UPS ($UPS), Sherwin-Williams ($SHW), Ecolab ($ECL), Hilton ($HLT), Illinois Tool Works ($ITW), Royal Caribbean ($RCL), Paccar ($PCAR), PayPal ($PYPL), IQVIA ($IQV), CenterPoint Energy ($CNP), Xylem ($XYL), Hubbell ($HUBB), CMS Energy ($CMS), Invesco ($IVZ) and Pentair ($PNR)
  • After the close: Visa ($V), Seagate Technology ($STX), Waste Management ($WM), Robinhood ($HOOD), Oneok ($OKE), NXP Semiconductors ($NXPI), Baker Hughes ($BKR), Ventas ($VTR), EQT ($EQT), Arch Capital ($ACGL), Extra Space Storage ($EXR), FirstEnergy ($FE), F5 ($FFIV), PPG Industries ($PPG), Expand Energy ($EXE), Essex Property Trust ($ESS), CoStar Group ($CSGP), Universal Health Services ($UHS) and BXP ($BXP)

Outside the US, Novartis ($NVS) and Porsche ($DRPRY) have reported, followed by SK Hynix ($SKHY) tonight.

Ex-US highlights include China September industrial profits, South Korea Q3 GDP, France October consumer confidence, Eurozone September M3 and the ECB’s Q3 Bank Lending Survey. Israel also holds parliamentary elections.

From Christophe Barraud’s international Week Ahead rundown:

Upside, Downside Movers

Upside

– $GRML +44% (extends the high-volume Greenland critical-minerals momentum rally)

– $VKTX +25% (positive VK2735 maintenance data showed strong weight loss and high retention with biweekly and monthly dosing)

– $VICR +8.7% (raises Q3 sequential revenue-growth guidance to more than 20% from nearly 10% on V4PD-license royalties)

– $ONON +8.0% (sets high-teens constant-currency sales growth and 22%+ EBITDA-margin targets through 2029 and authorizes a $1B buyback)

– $SHOP +5.1% (no clear fresh catalyst identified; unusually large premarket move in a highly followed stock)

– $RCL +2.4%, CCL +3.0%, NCLH +2.7% (cruise operators rise as crude drops, easing fuel-cost pressure)

– $FSLR +1.8% (rate-sensitive solar shares benefit as Treasury yields retreat)

Downside

– $CLDX -20% (positive Phase 3 CSU results trigger a sell-the-news reaction after the anticipated binary readout)

– $DAVA -13% (CFO placed on leave amid an internal accounting investigation disclosed in a 6-K)

– $LH -6.2%, DGX -6.9% (CMS proposes laboratory reimbursement cuts of up to 15% beginning in 2027)

– $VLO -2.1%, $PSX -2.0% (energy names fall as crude drops on easing geopolitical risk)

– $STX -1.4%, WDC -1.4% (storage names pull back with the semiconductor complex after the prior session’s AI-driven rally)

SOURCE: Trade The News