PepGen Up, iHeartMedia Down: Upside, Downside Movers in the Morning

Upside

– $PEPG +114% (Phase 2 FREEDOM2-DM1 data showed 46.5% mean splicing correction and functional improvements with no serious or severe adverse events)

– $MNDO +46% (agrees to be acquired for $1.30 per share in cash)

– $SECZ +25% (River One acquisition, $50 million buyback and record tokenized assets accompanied quarterly results)

– $HROW +18% (record revenue and a sharp Q4 profit ramp outweighed a reduced full-year EBITDA floor)

– $KLTR +18% (Q3 exceeded revenue and profit guidance, with record subscription sales and a higher full-year outlook)

– $PDYN +18% (record revenue jumped 895%, the low end of full-year guidance was raised and funded backlog reached $15.3 million)

– $AAON +15% (Q3 crushed expectations and the sales outlook was raised as data-center cooling demand drove BASX growth)

– $QMCO +15% (revenue rose 43%, margins expanded and backlog reached a record of nearly $100 million)

– $SENS +15% (Q3 revenue surged 140% and full-year revenue and gross-margin guidance were raised)

– $SANM +13% (quarter beat and FY27 revenue and profit guidance topped expectations on accelerating cloud and AI demand)

– $ZNTL +11% (Wedbush upgrades to Outperform after ovarian-cancer survival data strengthened the azenosertib case)

– $BW +9.3% (quarterly revenue more than doubled, backlog reached $2.5 billion and management issued a strong 2027 EBITDA target)

– $ASX +5.3% (October revenue increased 47% from a year earlier)

– $TTWO +4.6% (GTA VI preorders were far above initial expectations and the November release date was reaffirmed)

– $VG +4.4% (raises full-year adjusted EBITDA guidance following quarterly results)

Downside

– $IHRT -32% (Q3 adjusted EBITDA fell as persistent radio weakness drove a 43% decline in Multiplatform profit)

– $FF -29% (Q3 remained loss-making with negative EBITDA as chemical-unit downtime and biodiesel derivatives losses weighed)

– $APPS -22% (revenue beat and the sales outlook was raised, but EPS merely matched and FY EBITDA guidance was only maintained)

– $THRY -21% (SaaS revenue declined and the full-year SaaS revenue and EBITDA outlooks were lowered)

– $GILT -19% (Q3 sales missed and the full-year revenue outlook was cut as terminal deliveries and satellite-equipment orders shifted out)

– $GRPN -19% (Q3 sales missed and Q4 and full-year revenue guidance fell well short of expectations)

– $WGS -14% (profit missed, full-year testing-growth targets were cut and revenue is expected near the low end of guidance)

– $GFL -12% (rejects a reported $52-per-share takeover proposal and ends its strategic review without a sale)

– $JBI -11% (Q3 missed broadly and full-year revenue and EBITDA guidance was sharply reduced)

– $RKLB -8.2% (loss was wider than expected and the first Neutron launch was delayed until at least 2027)

– $LIF -6.7% (strong subscription growth was offset by a reduced advertising outlook and continued hardware weakness)

– $TTD -5.9% (quarter beat lowered expectations, but revenue declined year over year, margins contracted and the Q4 growth outlook remained subdued)

– $QLYS -4.9% (beat-and-raise quarter was overshadowed by margin contraction and a Q4 revenue-growth slowdown)

– $ONON -4.1% (headline earnings beat was driven by a one-time tariff refund while underlying margins and core guidance underwhelmed)

– $WIX -2.7% (Q3 beat, but the free-cash-flow margin outlook was cut and Partners growth softened)

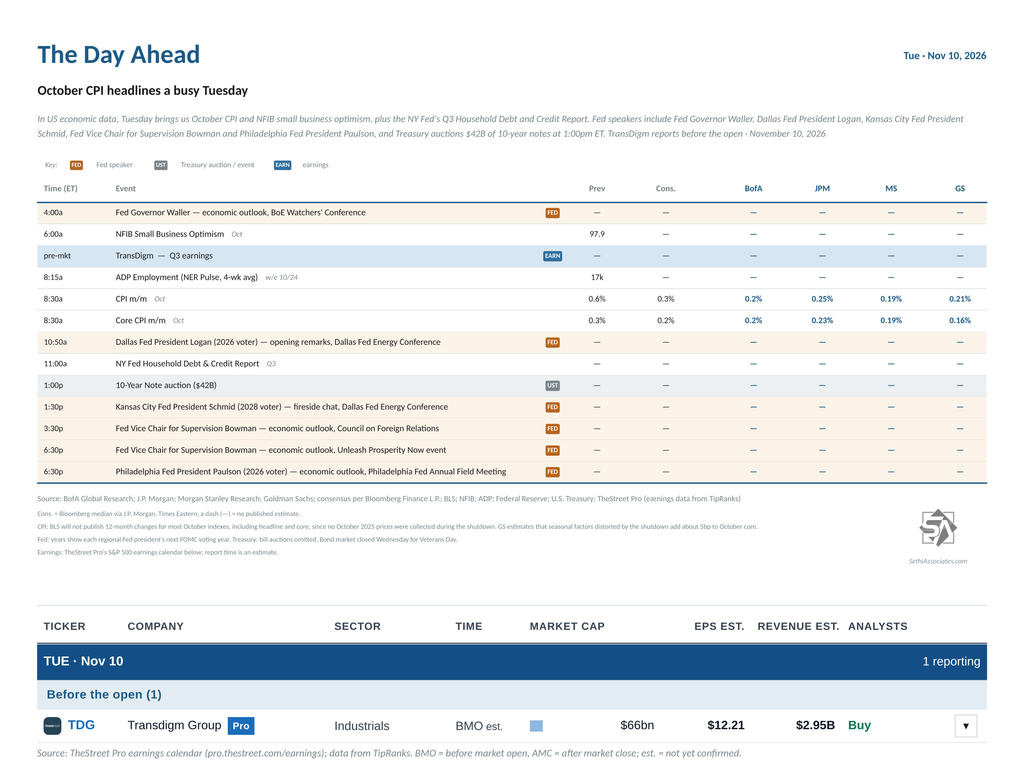
The Day Ahead — October CPI Headlines a Busy Tuesday

In US economic data, Tuesday brings us October CPI and NFIB small business optimism, plus the NY Fed’s Q3 Household Debt and Credit Report. Note that BLS won’t publish 12-month changes for most CPI indexes, including headline and core, since no October 2025 prices were collected during the shutdown. For a CPI preview, see CPI Preview: Cooler, but Probably Not Enough to Stop a December Hike.

Fed speakers include Fed Governor Waller, Dallas Fed President Logan (2026 voter), Kansas City Fed President Schmid (2028 voter), Fed Vice Chair for Supervision Bowman and Philadelphia Fed President Paulson (2026 voter).

Non-Bill (>1yr in maturity) US Treasury auctions bring us a $42B 10-year note sale at 1:00pm ET.

One S&P 500 component reports:

-Before the open: TransDigm ($TDG).

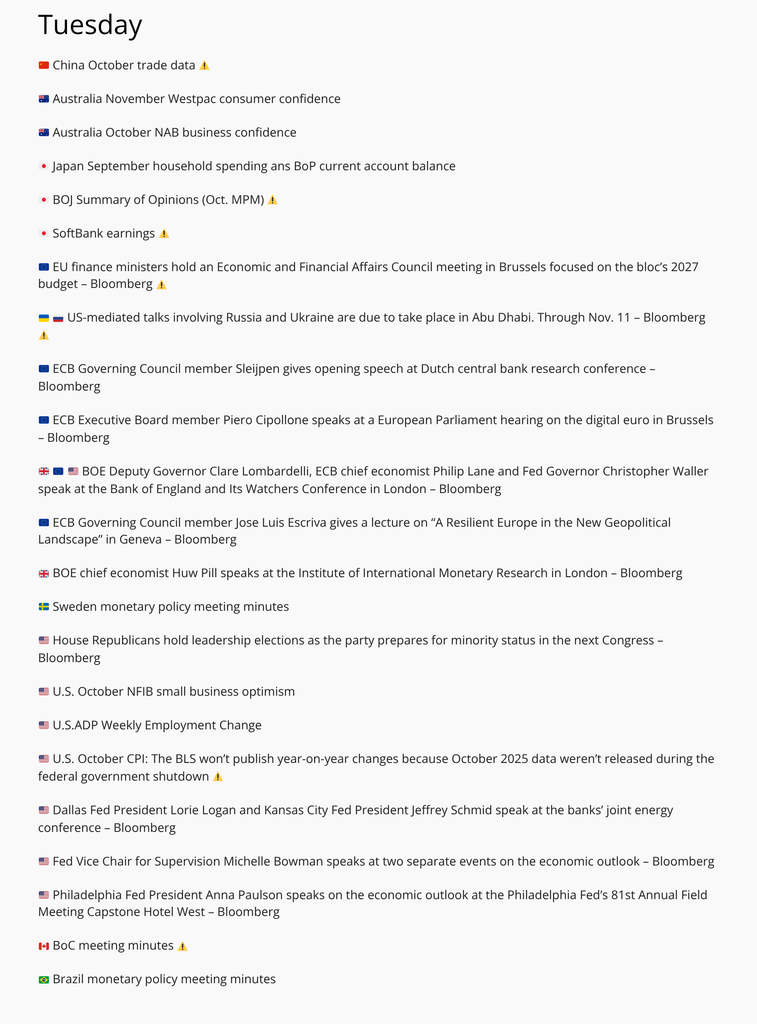
But outside the S&P 500 a lot of focus will be on CoreWeave ($CRWV). We’ll also hear from Petrobras ($PBR), Sea ($SE), Vodafone ($VOD), Venture Global ($VG), and On Holding ($ONON).

Ex-US highlights include China’s October trade balance, Japan’s October Economy Watchers survey and September household spending, and October CPI in Norway and Denmark. The Bank of Canada releases the Summary of Deliberations from its last meeting (1:30pm ET) and Brazil’s central bank its Copom minutes, while the ECB’s Cipollone, Lane and Escriva and the BoE’s Lombardelli and Pill speak. US-mediated talks between Russia and Ukraine are expected Tuesday and Wednesday.

From Christophe Barraud’s international Week Ahead rundown:

SoFI Up, HSBC Down: Upside, Downside Movers in the Morning

Upside

– $MFIC +23% (ARCC agrees to acquire it for $10.88 per share in cash and stock, valuing the transaction at about $2.6B)

– $INIO +14% (record Q3 results and FY26 revenue and EBITDA outlooks were raised)

– $CLS +12% (Q3 beat, FY26 outlook raised and initial 2027 guidance called for 90% revenue growth on accelerating AI-infrastructure demand)

– $SOFI +11% (record Q3 revenue and EBITDA, strong member growth and a raised FY26 outlook)

– $FER +9.9% (no clear fresh catalyst identified; unusually large, liquid move ahead of 9M results after the U.S. close)

– $RCL +5.3% (Q3 beat, bookings remained strong and the full-year profit outlook was raised)

– $CRDO +4.3%, $SKHY +3.2%, $COHR +2.7%, $AMKR +3.6%, $LITE +2.6%, $AVGO +2.9% (AI-chip and optical-connectivity names rise as the CLS outlook reinforces accelerating hyperscaler demand)

– $JCI +4.3% (Q4 beat and the FY27 profit outlook topped expectations)

– $SPGI +3.8% (FY26 outlook raised and a strategic review of Capital IQ businesses was launched)

– $NBIS +3.7%, BE +3.3%, CRWV +3.6%, VRT +2.2% (AI-infrastructure names gain after CLS said customer demand forecasts continue strengthening into 2027 and 2028)

– $NCLH +2.2%, CCL +2.7% (cruise peers rise after RCL beat expectations and raised its full-year profit outlook)

– $CDNS +1.8% (Q3 beat, FY outlook raised, backlog reached a record $8.2B and a $2.5B buyback was added)

– UPS +1.8% (Q3 beat and FY26 revenue and profit forecasts were raised as shipment mix and cost reductions improved)

Downside

– $XYL -8.5% (Q3 update disappointed, with investors focusing on softer revenue expectations)

– $WSO -8.3% (Q3 profit missed expectations)

– $HSBC -6.7% (Q3 revenue and pretax profit missed expectations, outweighing a new $1B buyback)

– $HLT -4.4% (Q3 earnings beat, but revenue missed and the raised RevPAR outlook was not enough for elevated expectations)

– $SHW -3.8% (Q3 results and outlook disappointed as housing-linked demand remained soft)

– $ONON -3.3% (no clear fresh catalyst identified; unusually large, high-volume premarket decline)

– $MAR -2.0% (hotel peer slips in sympathy with HLT after its revenue miss)

Upside, Downside Movers

Upside

– $GRML +44% (extends the high-volume Greenland critical-minerals momentum rally)

– $VKTX +25% (positive VK2735 maintenance data showed strong weight loss and high retention with biweekly and monthly dosing)

– $VICR +8.7% (raises Q3 sequential revenue-growth guidance to more than 20% from nearly 10% on V4PD-license royalties)

– $ONON +8.0% (sets high-teens constant-currency sales growth and 22%+ EBITDA-margin targets through 2029 and authorizes a $1B buyback)

– $SHOP +5.1% (no clear fresh catalyst identified; unusually large premarket move in a highly followed stock)

– $RCL +2.4%, CCL +3.0%, NCLH +2.7% (cruise operators rise as crude drops, easing fuel-cost pressure)

– $FSLR +1.8% (rate-sensitive solar shares benefit as Treasury yields retreat)

Downside

– $CLDX -20% (positive Phase 3 CSU results trigger a sell-the-news reaction after the anticipated binary readout)

– $DAVA -13% (CFO placed on leave amid an internal accounting investigation disclosed in a 6-K)

– $LH -6.2%, DGX -6.9% (CMS proposes laboratory reimbursement cuts of up to 15% beginning in 2027)

– $VLO -2.1%, $PSX -2.0% (energy names fall as crude drops on easing geopolitical risk)

– $STX -1.4%, WDC -1.4% (storage names pull back with the semiconductor complex after the prior session’s AI-driven rally)

SOURCE: Trade The News