Tech Bounces, but the S&P 500 Still Has Its Worst Week Since April 2025

Tech got a bounce but finished well off the highs and most stocks slipped as yields and the dollar rose after a blowout employment report.
Tech got a bounce but finished well off the highs and most stocks slipped as yields and the dollar rose after a blowout employment report.
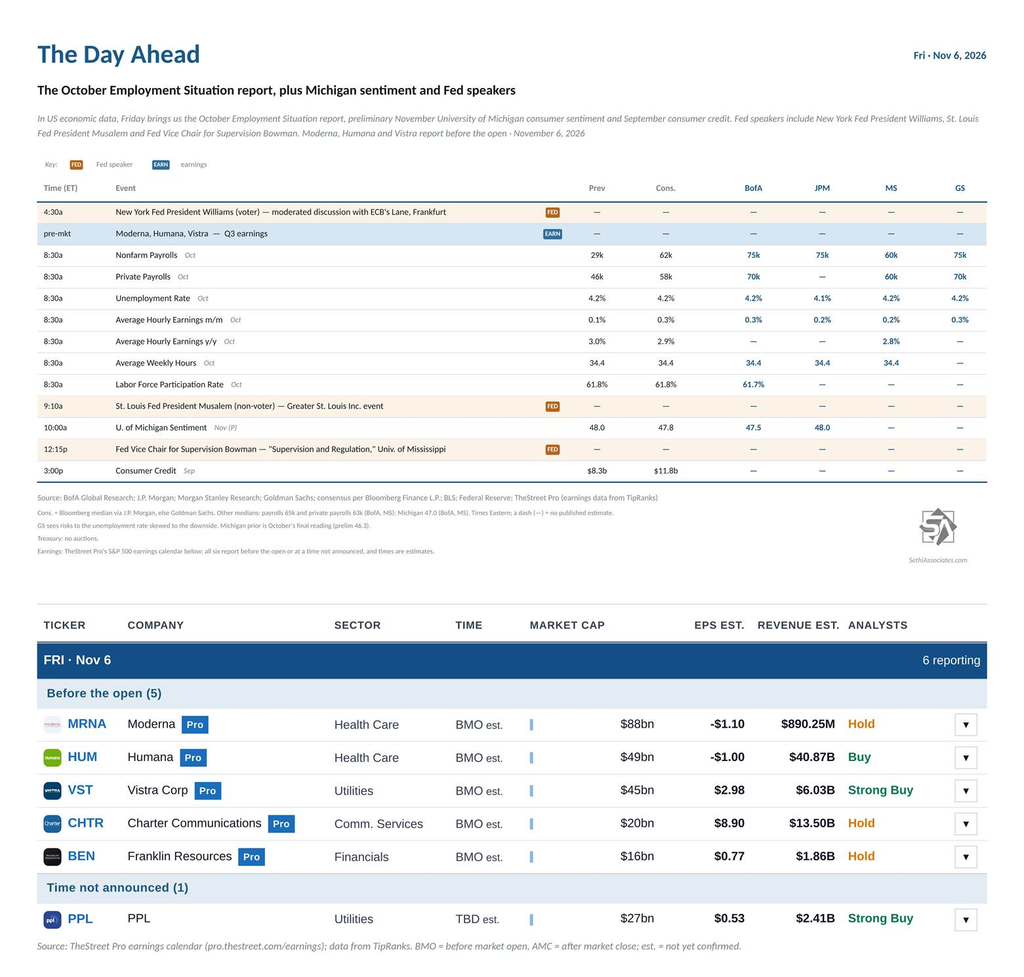
In US economic data, Friday brings us the October employment report and preliminary November University of Michigan consumer sentiment, plus September consumer credit.
In Fed speakers, New York Fed President Williams (voter) joins the ECB’s Lane for a moderated discussion in Frankfurt at 4:30am ET, St. Louis Fed President Musalem (non-voter) speaks at a Greater St. Louis Inc. event at 9:10am ET, and Fed Vice Chair for Supervision Bowman discusses supervision and regulation at the University of Mississippi at 12:15pm ET. Also, the Justice Department and lawyers for Fed Governor Lisa Cook are due to file a report with a federal judge on how to proceed with her lawsuit challenging President Trump’s attempt to remove her, per Bloomberg.
There are no non-Bill (>1yr in maturity) US Treasury auctions.
Six S&P 500 components report, none with market caps over $100bn:
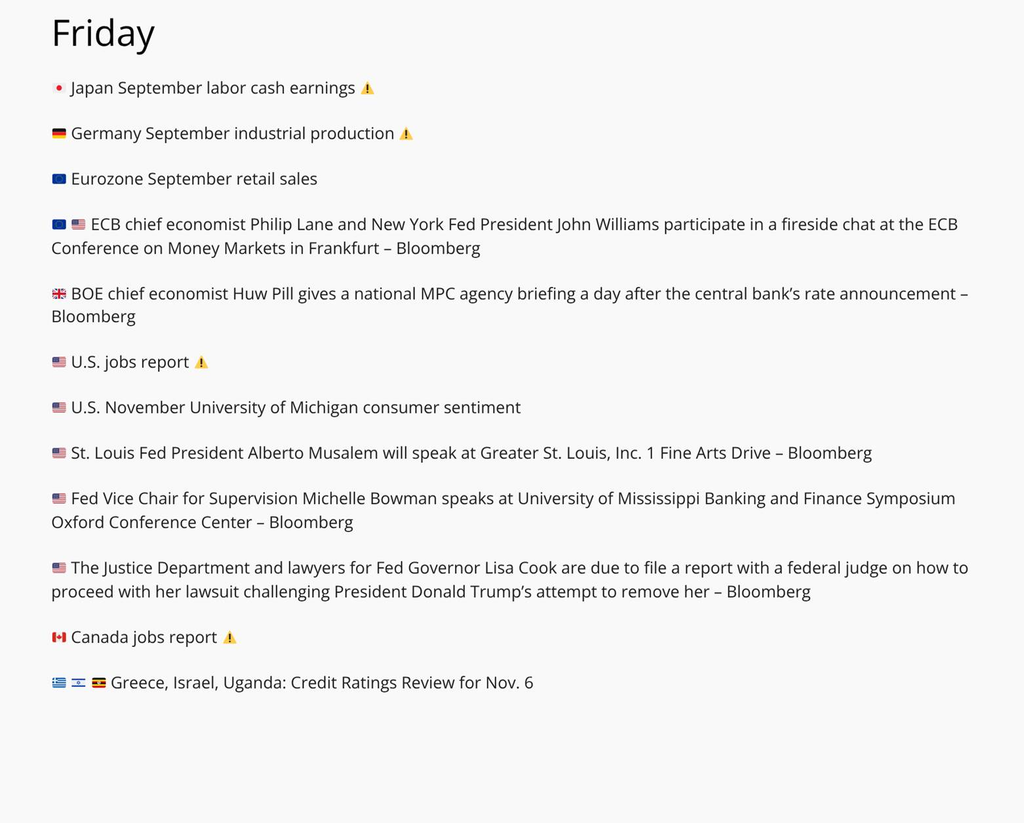
Ex-US highlights include Japan September labor cash earnings, Germany September industrial production, France’s September current account and trade balances and Q3 wages, Eurozone September retail sales and Canada’s October Labour Force Survey. The BoE’s Huw Pill also gives a briefing the day after the bank’s decision, and Greece and Israel face credit rating reviews.
From Christophe Barraud’s international Week Ahead rundown:
Worries that Democrat political gains will slow the AI buildout morphed into a broader selloff Thursday pulling every sector lower, led by Tech.
Subscriber jryan (below) delivered some reasonable comments and criticism yesterday in the Comments Section.
Basically he said he is “getting sick of reading about cannabis and Fin TV commentary” — and he wants more (long) stock suggestions, etc.
I wanted to respond in the first column of the day.
* Few longs have represented value to me as I have been unduly negative for a lengthy period of time. I take ownership of that.
* The stocks that I have owned have recently been Staples ($KO, $PEP, $PG and $KMB), selected cannabis names and some others. The consumer nondurable stocks have been fine recently (and I have taken profits in them). We shall see about cannabis — a speculative sector and my focus has been intermediate-term based on the improved likelihood of rescheduling and other factors clearly delineated in my Diary.
*As to the CNBC constructive criticism. I point these out not only as an advocate of the retail viewer that should see timestamps (panelists taking ownership) and observe better company interviews, but so they can evaluate the merits and process of the panelists’ recommendations and become better-informed investors through more hard-hitting interviews (that serve more than as a marketing tool of companies).
* But the criticism directed to Fin TV also is intended to highlight investment recommendations from panelists and guests that I strongly disagree with. Choosing stocks to avoid (in that FIN TV criticism) can be as valuable or even more valuable than choosing stocks to buy. Consider my negative comments towards $BA, $BABA, $META, $UBER, $NFLX, $RDDT, $TTAN, $DIS, $CLF, $MRNA and $UNH (a few years back) etc. that were mostly confidently and strenuously recommended on CNBC.
* My “More Tales From Nvidia” series is intended to deliver the idea that the functionality, productivity and ROIC on the enormous capital spend may disappoint the many and multitude of optimists on AI. I have felt that my contrarian and non herd-like observations were valuable in a backdrop of near-universal bullishness (that is readily and frequently available from the buy/sell sides, panelists and guests). My view was that dwelling on “More Tales” had statistical value in that over 40% of the S&P is comprised of large-cap tech.
* As to specific AI beneficiaries, I have admitted (often) of missing $MSFT and $GOOGL. The valuation on $AAPL seems foolish to me — the shares have prospered and I have been wrong. But the others ($META, $AMZN and even $NVDA) have not set the world on fire this year. As to memory and chip stocks, they have been “the world’s fair” up until the summer but awful since late June. Not only do I think these companies are “overearning,” but the volatility is not for me and not consistent and doesn’t conform with my appetite for risk.
* The financial stocks were quite strong until early summer. I repeatedly cautioned not to embrace banks, brokers and private equity shares (I successfully shorted $BX, $KKR and $APOL since then). Viewed by panelists as perhaps the best “value play,” financials have been dismal over the last four months. We avoided this decline (in $C, $JPM, $BAC, $GS, $MS et al).
* The stocks that I have been short in the AI sphere have been terrific (to the downside) — $ORCL and $CRWV. (Avoiding them as longs has also been a valuable contribution.) My recent foray into shorting NVDA was profitable also.
* As to my preoccupation with CNBC I suggest taking the number of words written about FIN TV and divide it by the number of words written on other subjects daily. You will find my criticism is dwarfed by my other columns. In the scheme of things my criticism is de minimis.
* Finally, to jryan I say there are many other contributors that actively recommend longs and provide a valuable service.
All this said I am imperfect.
I take ownership of my mistakes.
The transparency of my Diary exposes my blemishes.
I believe jryan has some good points and I will purposefully look for more long ideas in the future.
I truly appreciate jryan’s comments and I have tried to respond to his concerns:
jryan
Just a thought. There used to be a lot of different investment ideas, stock suggestions etc., but all it seems to be now is cannabis and CNBC commentary, which I don’t watch anyway. Kind of getting sick of it, especially the cannabis info, is it ever going to pay off? Likely, but it will be quite a while from today, if ever. But at least it’s easier to scroll through the commentary and use less time.
Position: Long KO (VS), PG (VS), KMB (VS), MSOS common (VL) and calls (VS), VRNO (VS), GLAS (S), GTBIF (S), TRLV (VS), CURLF (VS); Short AAPL (S)
– $XNCR +32% (Phase 1 XmAb819 kidney-cancer data showed a 45.5% confirmed response rate and 82% six-month PFS at the proposed Phase 3 dose)
– $RENT +30% (no clear fresh catalyst identified; unusually heavy premarket volume extends Friday’s surge)
– $SGRY +24% (report of late-stage talks for Bon Secours Mercy Health to acquire a controlling stake at about $20 a share)
– $RRC +11% (EQT agreed to acquire it in a 0.987-share all-stock deal)
– $MACI +10% (shareholders approved the Everli business combination)
– $ROST +3.4% (UBS upgrades to Buy)
– $AVBP +3.3% (initial Phase 1 ARR-217 data showed a 44.8% response rate in colorectal cancer at the selected dose)
– $TSLA +2.3% (Barclays upgrades to Overweight, citing improving auto fundamentals, robotaxi momentum and potential SpaceX-combination upside)
– $XP -48%, $STNE -39%, $PAGS -32%, $BBD -30%, $ITUB -26%, $NU -26% (Brazil-linked financials plunge after leftist incumbent Lula won the presidential election over Flávio Bolsonaro)
– $BAK -34%, $PBR -19%, $VALE -4.9% (Brazil commodity names fall on the election shock and policy-risk repricing)
– $MRNA -8.1% (sell-the-news unwind continues after Phase 3 melanoma-vaccine data, with expectations elevated following the prior rally)
– $EQT -6.8% (falls as the acquirer in the all-stock purchase of RRC)
– $EFX -3.5% (RBC downgrades to Sector Perform on mortgage weakness concerns)
– $NTAP 3.0% (Guggenheim initiates coverage at Neutral)
– $CRWV -2.2%, $IREN -2.0% (neoclouds fall after SpaceX closed a $40B debt raise to buy Nvidia GPUs, signaling a large captive AI-compute build)
Let’s look at the sentiment cycle chart to see where we are. Hint, while we’re not at ‘enthusiasm,’ we’re also not at ‘panic.’
– $CCI +11%, SBAC +9.9%, AMT +8.5% (tower operators rise after a report that SpaceX is discussing infrastructure partnerships for a nationwide wireless buildout)
– $NOK +5.2% (Q3 profit beat as AI-and-cloud sales more than doubled and order intake surged)
– $LITE +3.5%, AAOI +2.3%, COHR +2.3% (optical-networking names gain on read-through from Nokia’s sharp AI-and-cloud order growth)
– $BAH +1.9% (Q2 profit beat offset a slight revenue miss)
– $TECK +1.7% (copper-linked stocks rise as copper prices advance)
– $FLG -8.3% (Q3 profit and revenue missed expectations)
– $DECK -8.2% (quarterly sales missed and the FY sales outlook was cut, while the higher EPS guide relied partly on tariff refunds)
– $INFY -8.2% (FY revenue-growth guidance was cut to 1%-2% despite strong large-deal wins)
– $ALV -5.2% (Q3 profit and sales missed as cost headwinds weighed on results)
– $CRDO -4.6% (AI-infrastructure hardware weakness continues amid concerns over the pace and returns of sector spending)
– $TMUS -4.5%, T -4.4%, VZ -3.9% (wireless carriers fall after a report that SpaceX is pursuing a nationwide cellular-infrastructure program)
– $BE -3.9% (record results and raised guidance were not enough after a major AI-power rally)
– $MRNA -3.7% (extends losses following leaked cancer-vaccine data that disappointed investors)
– $FIX -3.1% (earnings beat, but the CFO retirement and elevated expectations drive a sell-the-news reaction)
– $ACN -2.7%, $CTSH -2.0% (IT-services names fall after Infosys cut its FY growth outlook)
– $WDC -1.9%, STX -1.4% (storage names retreat despite WDC’s beat-and-raise report as elevated expectations trigger profit-taking)
Worries about the sustainability of the AI trade surfaced once again, driving down a swath of related stocks, but other stocks rallied as Treasury yields dropped the most since August 2025, seeing equal-weight vs cap-weight the most extreme since 2024.
Nine of 11 sectors rose, powering the S&P higher despite semiconductor weakness. Small-caps, though, posted a fifth straight weekly loss for the first time since 2022.
Long-end yields again hit multi-decade highs before a historically strong 10-year auction pulled them back, letting large-caps pare losses.