Apple Price Target Cuts, Palantir Earnings Reaction: 8 Key Items Shaping the Stock Market Tuesday

Eaton’s earnings, S&P 500 and Nasdaq Composite levels and other headlines are moving the market this morning.
Eaton’s earnings, S&P 500 and Nasdaq Composite levels and other headlines are moving the market this morning.
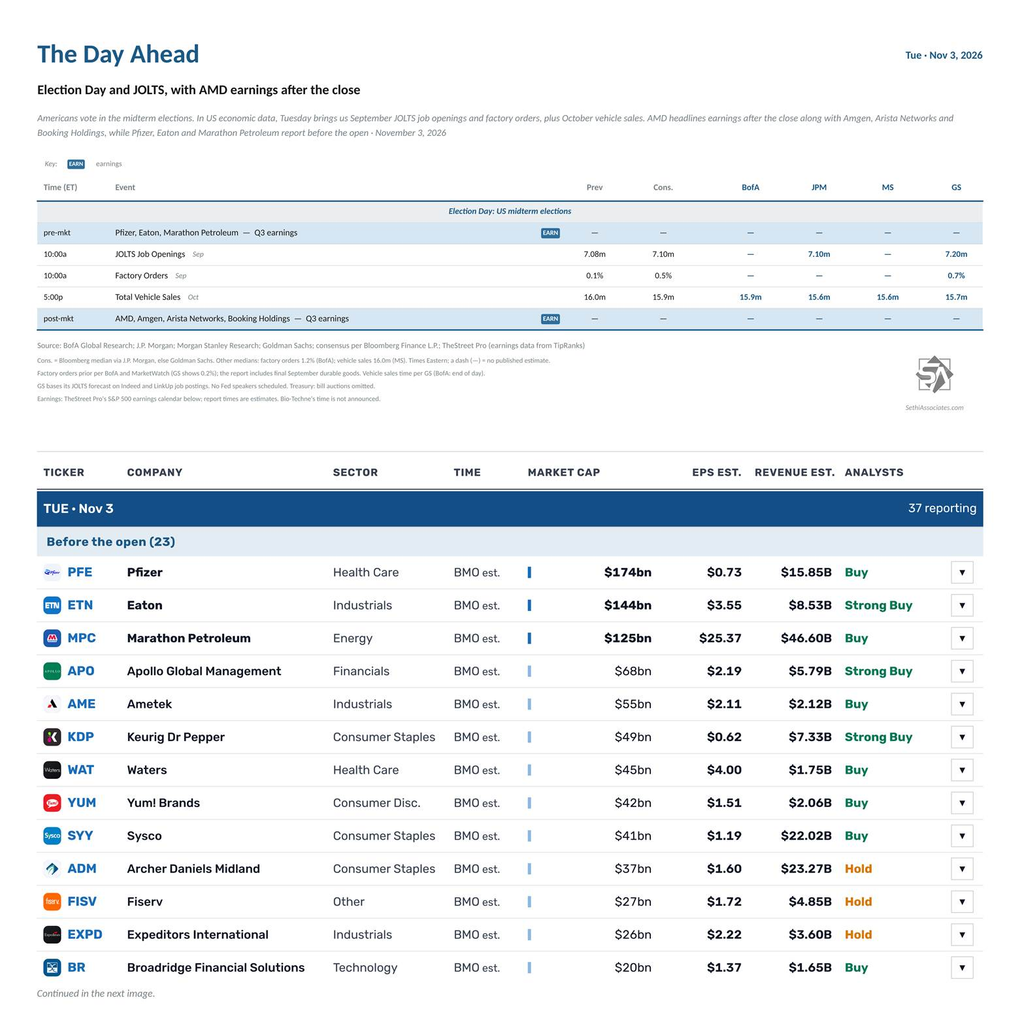
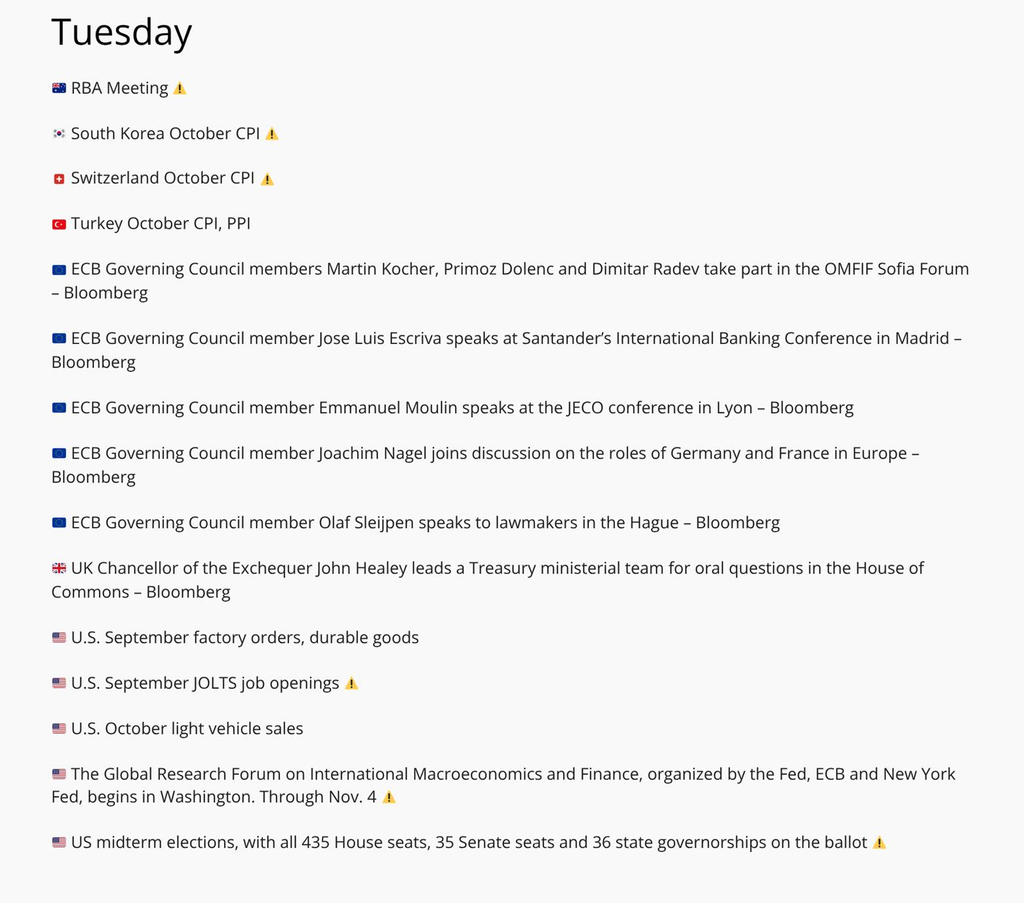
It’s Election Day, with Americans voting in the midterm elections (all 435 House seats, 35 Senate seats and 36 governorships are on the ballot).
In US economic data, Tuesday brings us September JOLTS job openings and factory orders (which include final durable goods), and October vehicle sales.
There are no Fed speakers scheduled, although the Global Research Forum on International Macroeconomics and Finance, organized by the Fed, ECB and New York Fed, begins in Washington (through November 4), so there may very well be media interviews.
There are no non-Bill (>1yr in maturity) US Treasury auctions this week.
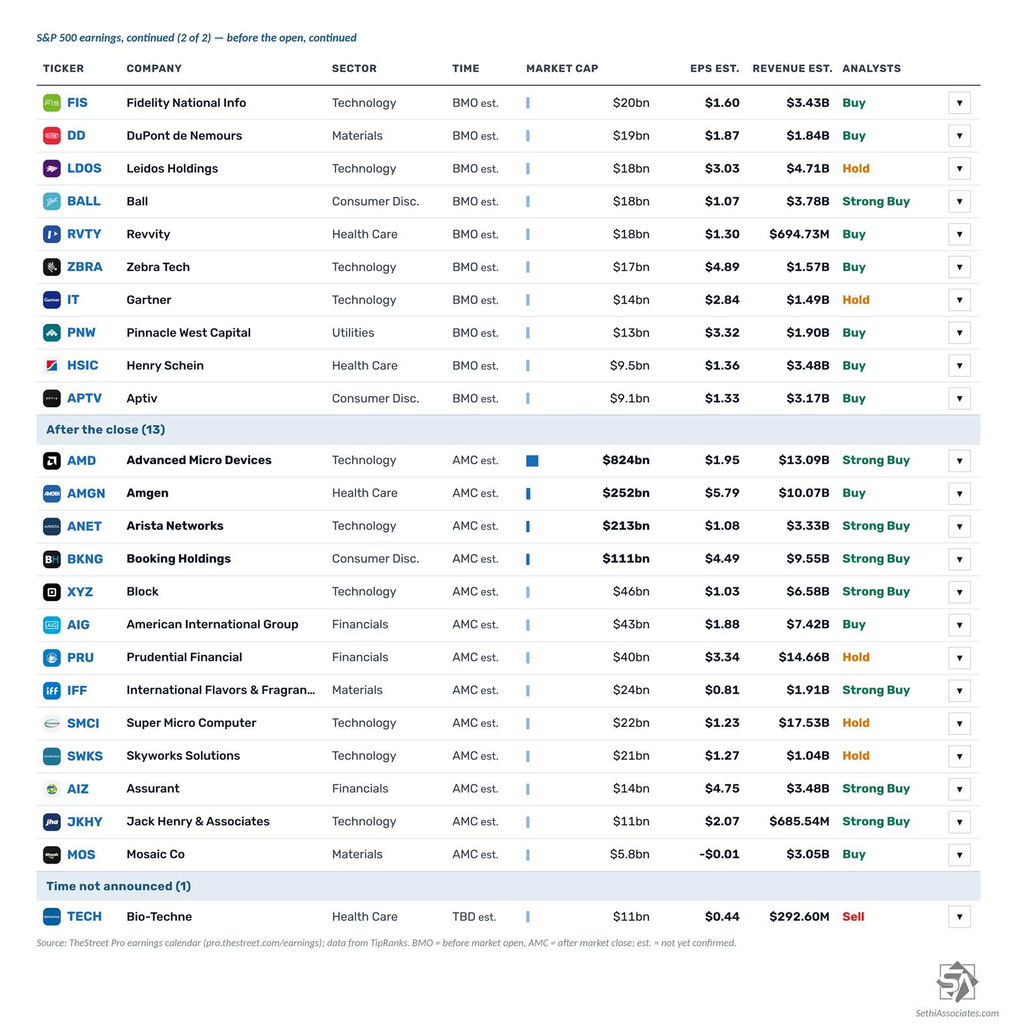
37 S&P 500 components report, seven of them with market caps over $100bn:
After the close: AMD ($AMD), Amgen ($AMGN), Arista Networks ($ANET), Booking Holdings ($BKNG), Block ($XYZ), AIG ($AIG), Prudential Financial ($PRU), International Flavors & Fragrances ($IFF), Super Micro Computer ($SMCI), Skyworks Solutions ($SWKS), Assurant ($AIZ), Jack Henry & Associates ($JKHY) and Mosaic ($MOS)
Before the open: Pfizer ($PFE), Eaton ($ETN), Marathon Petroleum ($MPC), Apollo Global Management ($APO), Ametek ($AME), Keurig Dr Pepper ($KDP), Waters ($WAT), Yum! Brands ($YUM), Sysco ($SYY), Archer-Daniels-Midland ($ADM), Fiserv ($FISV), Expeditors International ($EXPD), Broadridge Financial ($BR), Fidelity National Information Services ($FIS), DuPont ($DD), Leidos ($LDOS), Ball ($BALL), Revvity ($RVTY), Zebra Technologies ($ZBRA), Gartner ($IT), Pinnacle West ($PNW), Henry Schein ($HSIC) and Aptiv ($APTV)
Time not announced: Bio-Techne ($TECH)
Outside the S&P 500, Shopify ($SHOP), Energy Transfer ($ET), Ferrari ($RACE), Bayer ($BAYRY) and Intesa Sanpaolo ($ISNPY) report.
Ex-US highlights include the Reserve Bank of Australia’s decision (10:30pm ET Monday; Deutsche Bank expects a hold), October CPI from Switzerland, South Korea and Turkey (plus Turkey PPI), New Zealand’s Q3 labor force survey, Japan’s October monetary base and France’s September budget balance. ECB Governing Council members Kocher, Dolenc, Radev, Escriva, Moulin, Nagel and Sleijpen speak, as do the Bank of Canada’s Macklem and Rogers, and UK Chancellor of the Exchequer Healey takes oral questions in the House of Commons.
Japanese markets are closed for Culture Day.
From Christophe Barraud’s international Week Ahead rundown:
Another drawdown in Tech, following its worst month since March 2025, overshadowed six sectors advancing more than 1%.
Jim Cramer, founder of TheStreet, once coined the term “accidental high yielder,” which means simply that a stock that has fallen so much that the yield versus earnings has become increasingly attractive. Companies have options for their cash flows, that would be pay a dividend, buy back shares or simply reinvest in the business and retain those earnings (rather than paying them out). Cramer knew that fundamentally sound companies were being temporarily punished but at the same time they became attractive to another style of investor — the dividend player or the value player.
Mosaic ($MOS) fits the bill here, sporting a 4.5% to 4.9% yield now as the stock has fallen to levels not seen since 2020! It’s a nice catch here. That seems hard to believe but fertilizer companies are the furthest thing from AI that you can imagine. Hence, the stock is not showing all that much growth here. High energy prices used to be a big thing for the fertilizers, but apparently this time around, it’s not happening. How strong is the Mosaic dividend? Demand for fertilizer still seems strong though pricing is a challenge, customers are still buying but input prices are rising, too. Cash flows are strong, I do not think this payout is in jeopardy.
Cargill created Mosaic in 2004 and spun off its shares in 2011, so this company is on its own these days. But with a strong yield even as the stock is down hard it may pay to wait, the stock can be volatile but at a five-year low it seems to be a low risk entry point.
At the time of publication, Lang was long MOS.
The megacap growth sectors went from worst (Friday) to first (Monday) as chipmakers snapped an eight-session losing streak, but rising Treasury yields left seven sectors, the Dow Jones Industrial Average, and the equal-weight S&P 500 lower.
Let’s dig in to the sentiment, options, and momentum indicators.
What to watch with SpaceX earnings, U.S munition pain point, Duke Energy’s capital plan, and other headlines are moving stocks this morning.