Japan’s Treasury Buying Nearly Dries Up as America’s Allies Pull Back

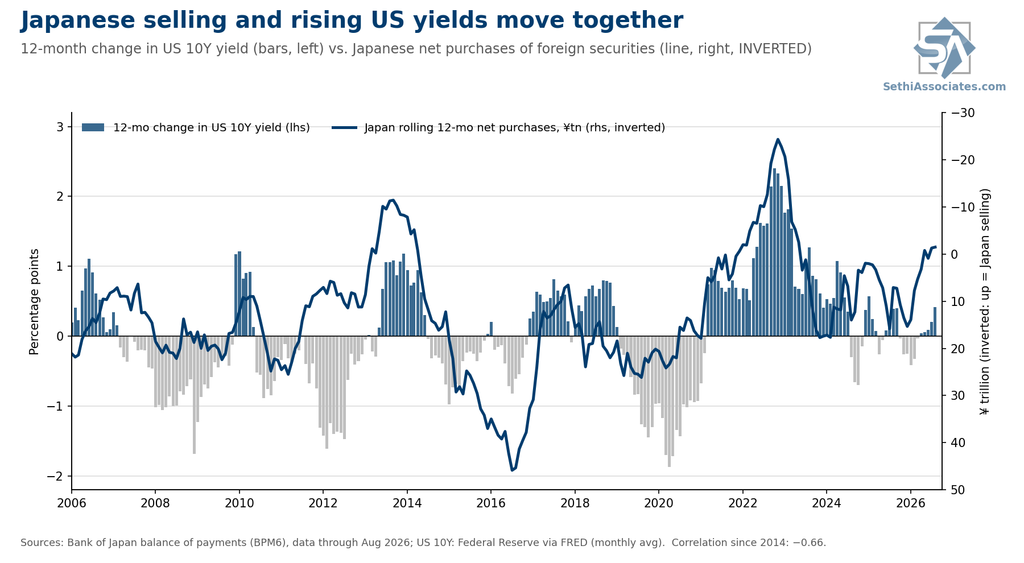
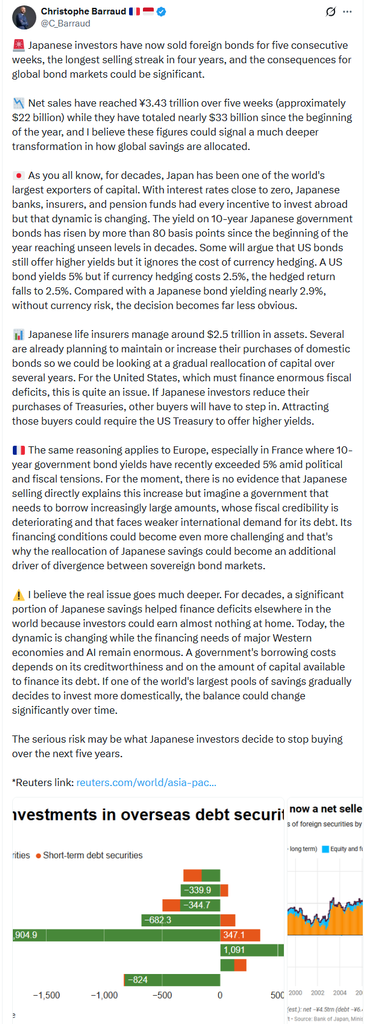
On Monday, I asked whether Japanese selling of Treasuries is a risk. Today, Bloomberg reported that the risk may be much broader than just Japan.
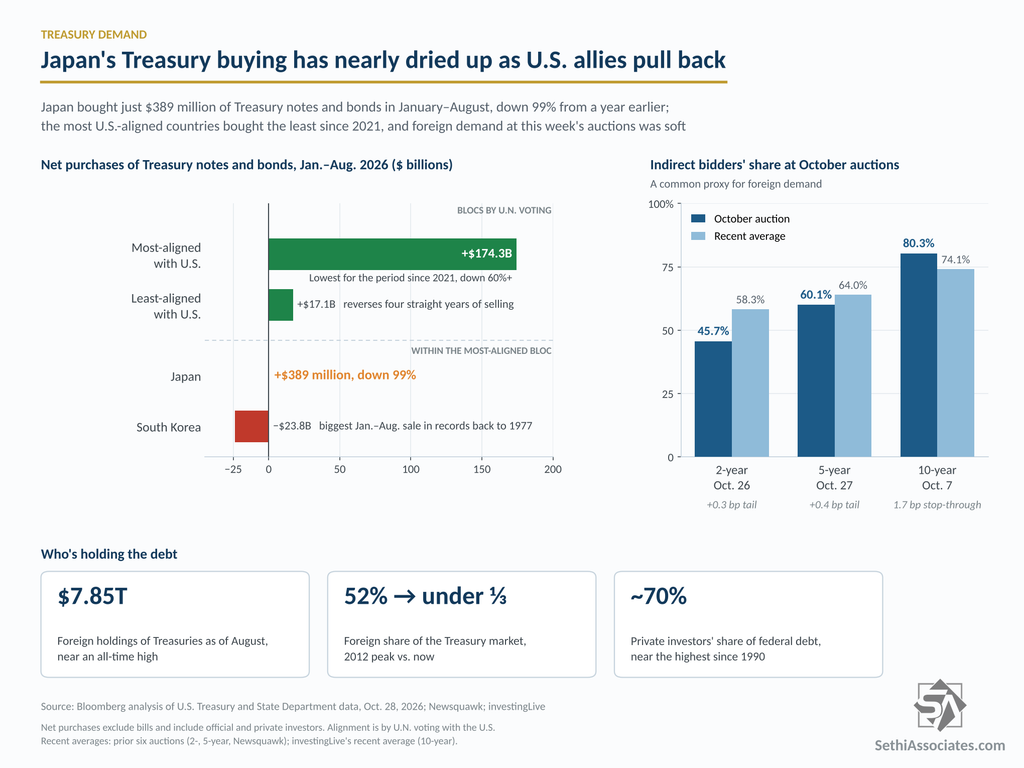
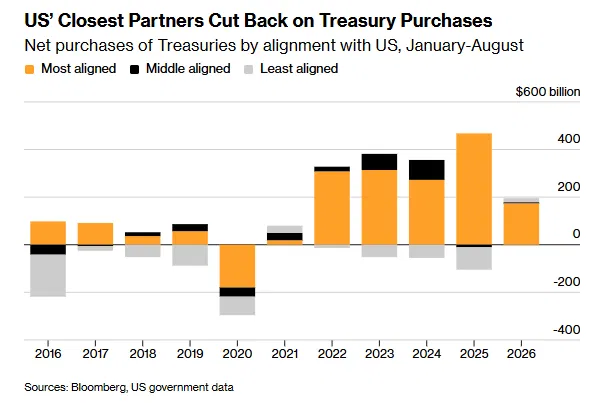
Countries most aligned with the U.S. bought a net $174.3 billion of Treasury notes and bonds in the first eight months of 2026, according to Bloomberg’s analysis of Treasury and State Department data. That’s the least for the period since 2021 and down more than 60% from a year earlier. Bloomberg ranks alignment by how often countries vote with the U.S. at the United Nations.
Asia led the retreat:
- Japan, the biggest foreign holder, bought just $389 million, down 99% from a year earlier.
- South Korea sold $23.8 billion, the most for the period in records going back to 1977.
- Taiwan was also a net seller.
The least-aligned countries bought $17.1 billion, reversing four straight years of selling over the same period. China remained the biggest seller, while the UK, Hong Kong and India were the biggest buyers. The data cover both government and private investors, and Bloomberg notes that holdings can be credited to the country where they’re held through custodians rather than to the actual owner.
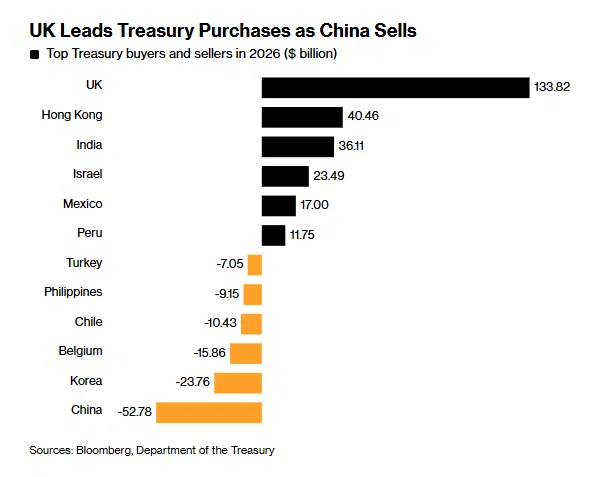
Bloomberg cites weak currencies, rising yields at home, growing demand for stocks and unease over U.S. policy as possible factors. The yen hit a four-decade low this year, and the won fell to its weakest since 2009.
“The Treasury market isn’t losing foreign buyers — it’s losing automatic buyers,” Masahiko Loo, a senior fixed-income strategist at State Street Investment Management, told Bloomberg.
Private investors, including hedge funds, banks and mutual funds, have stepped in, lifting their share of federal debt to about 70%, near the highest since 1990. Foreigners still owned $7.85 trillion of Treasuries as of August, near a record. But their share of the market has shrunk to less than a third, from a peak of 52% in 2012.
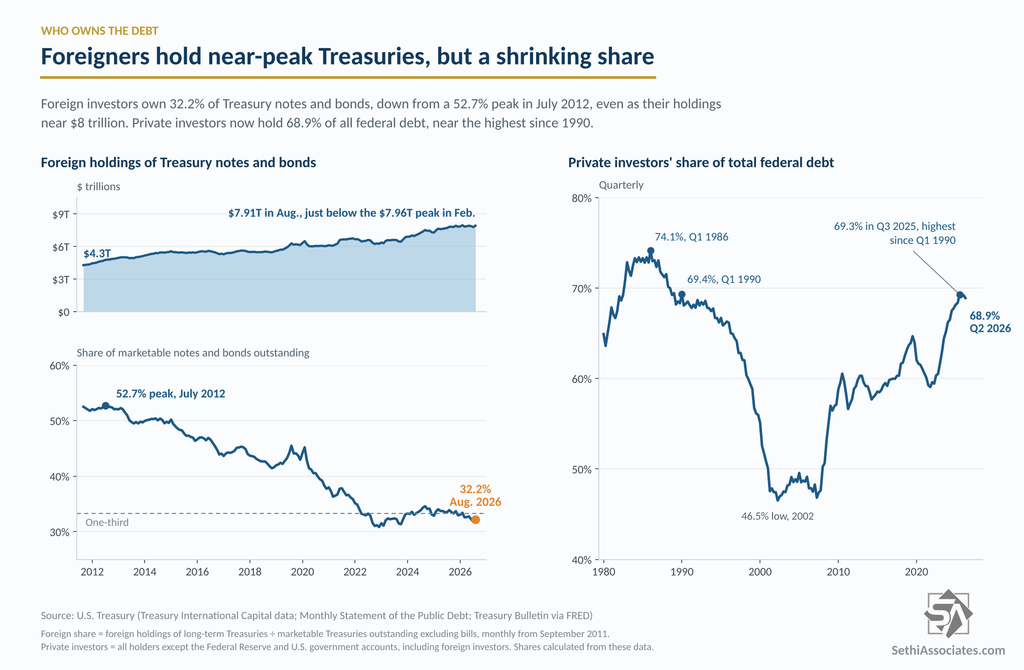
The tradeoff is price. “The Treasury will fund itself — the question is the price and the volatility of the price,” said Shoki Omori, Deutsche Bank’s chief fixed-income strategist for Japan..